
Have you ever looked up at a sleek new passenger jet and assumed it would keep flying for twenty or thirty years? Most of us do. These machines are engineering marvels designed for long careers. Yet right now something odd is happening in the aviation world. Perfectly good airplanes, some only three or four years old, are being torn apart for their parts instead of returning to the sky. It feels almost wasteful at first glance. But dig a little deeper and the logic becomes clearer, even if it still leaves a strange taste.
The Unexpected Early End For Modern Jets
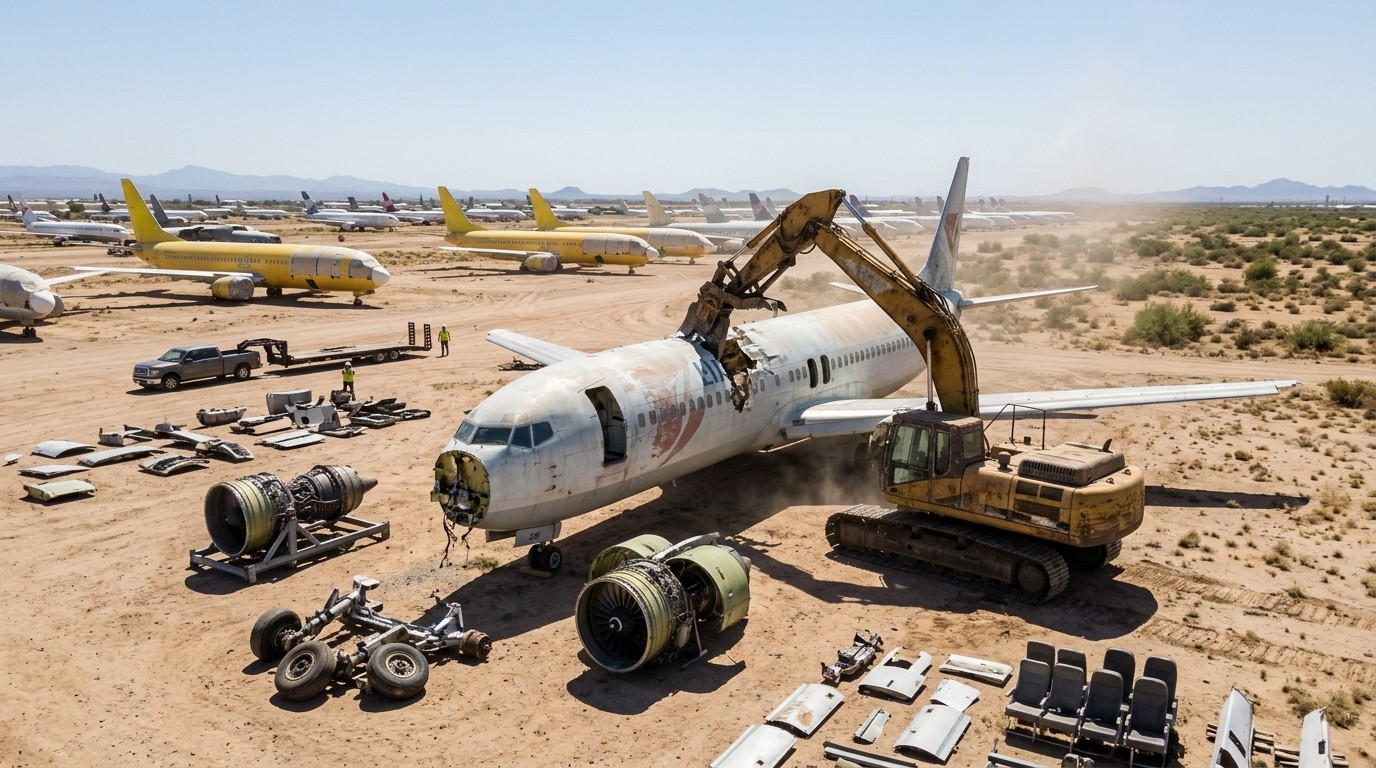
Picture an Airbus A320neo rolling off the production line in the summer of 2022. Bright paint, brand-new engines, built to carry passengers for decades. Less than four years later that same airframe sits in the Arizona desert while heavy machinery rips through its fuselage. The engines are gone. The landing gear has been carefully removed. Even smaller components like antennas and interior fittings are stripped for resale. What remains gets crushed and sent off for recycling. This is not an isolated case. Industry people who have spent entire careers around aircraft say they have never seen so many young planes heading for the scrap yard so quickly.
The average age of these recent teardowns sits around six and a half years. Compare that with the traditional retirement age for narrow-body jets, which used to hover near twenty-two years. The gap is striking. Owners are making cold calculations. Storage fees pile up. Waiting for scarce engines or critical parts can stretch into multiple years. In some cases the value locked inside the components simply outweighs the cost and uncertainty of putting the airplane back into service. I have found that conversations with people who handle these decisions keep returning to the same blunt advice: never fall in love with the metal.
Why Engine Problems Changed Everything
At the heart of this shift sits a stubborn shortage of jet engines and the parts that keep them running. Newer engines that promise better fuel burn also run hotter. That heat takes a toll. Maintenance intervals that operators expected to stretch further are arriving sooner than planned. Repair shops, whether run by the big manufacturers or independent specialists, now face long queues. Airlines and lessors hunt for spare engines anywhere they can find them. The result is a red-hot secondary market where prices have climbed sharply.
One popular engine family for the A320neo series saw values jump roughly sixty percent at the upper end compared with levels from a few years earlier. Monthly lease rates for these powerplants now sit in the range of one hundred sixty to one hundred eighty thousand dollars. Competing engines are not cheap either, often falling into a similar band. A single fan blade can cost fifty thousand dollars or more. Larger discs inside the engine might run between one and two million. When an airplane carries a pair of these high-value engines, the temptation to harvest them becomes hard to ignore.
A manufacturing issue discovered a few years ago only made the pressure worse. Contaminated material in certain engine parts triggered a recall that grounded hundreds of aircraft worldwide. Some operators felt the impact more than others. Planes sat idle while the overhaul pipeline stayed clogged. For owners already facing storage bills, the math shifted. Why keep paying to park a jet that might wait years for its engines when those same engines and hundreds of other components can generate immediate cash?
Anytime the market softens around aircraft or engine availability, investors start looking at other options. We always tell our traders not to fall in love with the metal.
That mindset has become widespread. Firms specializing in asset management and parts trading have started buying aircraft younger than five years old, something many veterans say was almost unheard of earlier in their careers. They pay single-digit millions for the airframes, then carefully extract more than a thousand individual parts. Even coffee makers sometimes find buyers. After the valuable pieces are gone, the remaining shell gets crushed and sold to metal recyclers. One executive described the final stage with a mix of pragmatism and quiet melancholy: once the useful equipment is stripped, what is left is essentially a metal carcass headed for the smelter, perhaps destined to become beer cans someday.
Storage Costs Versus Parts Value
Desert storage facilities in places like Arizona and similar arid regions have long served as parking lots for aircraft waiting out soft markets. The dry climate helps limit corrosion, so planes can sit for years or even decades if needed. Yet storage is never free. Fees vary by aircraft type and facility, but they add up month after month. For a lessor or owner facing an uncertain timeline for engine repairs, those ongoing costs start to look painful.
Some operators describe the situation as playing an elaborate game of Legos. Engines move from grounded airplanes onto active ones so that the fleet can keep flying while overhauled powerplants slowly return from the shop. That temporary shuffle works for a while. Eventually, though, certain airframes become more valuable as parts donors than as potential flying machines. The decision to tear them down is rarely emotional. It is arithmetic.
In my own conversations with people close to these operations, the same theme keeps appearing. A one-year wait might feel manageable. Stretch that to three or four years and the calculation changes. Owners who took delivery of aircraft in recent years suddenly find themselves staring at long delays. Rather than hope the supply chain improves, some choose to unlock the value sitting inside the airframe today.
What Happens After An Airline Collapse
When a major low-cost carrier ceased operations earlier this year, it dumped a large number of relatively young Airbus jets onto the market almost overnight. Many of those airplanes already carried the scars of the earlier engine recall. Some had been sitting in storage for months. Overnight the question became sharper for the lessors and owners: keep paying storage and hope for a buyer who wants a complete airplane, or begin harvesting components while demand for engines and other parts remains intense?
Not every airframe meets the same fate. Some will eventually fly again for other operators, perhaps after interior reconfiguration to offer more comfortable seat pitch. Others stay in the desert, preserved and waiting. A noticeable portion, however, follows the path of systematic disassembly. Visiting one of the facilities shortly after the collapse revealed rows of yellow-painted jets still containing safety cards and pilot manuals in the cockpits. The sense of sudden interruption was hard to miss. Former crew members occasionally stopped by simply to see the airplanes they once flew.
The aftermarket for used parts has responded with energy. Landing gear, avionics, actuators, even cabin fittings find ready buyers. Companies that specialize in this work report higher volumes of younger aircraft than they have ever handled before. One executive noted that watching a nearly new jet get reduced to scrap still feels a little melancholy, yet there is also a certain professional satisfaction in seeing the process executed cleanly and efficiently.
The Broader Ripple Effects Across The Industry
This wave of early teardowns does more than clear a few airframes from the desert. It feeds a secondary market that has become critical for keeping the rest of the global fleet airborne. Airlines that cannot wait for new engines or overhauled units turn to these harvested components. The practice helps bridge gaps created by production delays and maintenance bottlenecks further up the supply chain.
At the same time, the trend raises longer-term questions. Manufacturers continue to ramp up production of more efficient models. Older jets have always been retired to make room for them. Accelerating the retirement of relatively young aircraft, however, changes the usual rhythm. It can tighten the supply of used aircraft available for secondary operators or emerging markets that traditionally rely on older equipment. It also concentrates more value in the parts business relative to the complete-airframe market.
Perhaps the most interesting aspect is how quickly the industry adapted. Traders and asset managers who once focused almost exclusively on mid-life or end-of-life aircraft now evaluate nearly new jets through a different lens. The question is no longer simply “How many more years can this airplane fly?” It has become “What is the net present value of its engines and major components versus the cost and risk of returning it to service?”
- Engine lease rates remaining elevated for extended periods
- Repair shop backlogs measured in years rather than months
- Storage expenses that continue without clear end dates
- Strong residual demand for specific high-value components
- Uncertainty around future production rates for both airframes and engines
All of these factors feed into the same decision tree. When several of them align at once, the teardown option moves from last resort to rational choice.
Human Moments In A Technical Business
It is easy to discuss these issues purely in financial terms. Dollars per month for storage. Millions for an engine. Thousands of parts catalogued and sold. Yet the physical reality still carries weight. Watching an excavator tear into a fuselage that only recently carried passengers produces a visceral reaction. People who work in the desert facilities acknowledge that feeling. They also point out that the alternative—leaving a serviceable airplane to sit indefinitely while its value slowly erodes—can feel equally wasteful.
One facility operator described the process as sometimes delivering a strange thrill: seeing how quickly a complete aircraft can be reduced and sent to the recycler. That mix of practicality and quiet regret seems common among those closest to the work. They are not destroying airplanes for the sake of destruction. They are responding to market signals that have become unusually strong.
Former flight crew members who visit stored fleets often express a different emotion. The airplanes they once commanded sit silent under the desert sun, still bearing traces of their previous life. Safety cards remain in seat pockets. Manuals rest in the cockpit. Those details make the transition from flying machine to parts donor feel more personal than the balance-sheet analysis might suggest.
Looking Ahead At The Market Dynamics
Will this pattern of early teardowns continue? Much depends on how quickly engine overhaul capacity expands and how soon production of new powerplants catches up with demand. If wait times shrink meaningfully, more owners may choose to keep airframes intact and wait out the delays. If bottlenecks persist, the economic case for harvesting young aircraft will remain compelling.
In the meantime the aftermarket for engines and components shows no sign of cooling. Prices stay elevated. Lease rates for spare powerplants remain high. Airlines continue to shuffle engines between airframes to maximize daily utilization. The system works, but it is stretched. Early retirements of nearly new jets form one visible symptom of that stretch.
I keep returning to a simple observation. These airplanes were designed and certified for long service lives. The decision to end those lives early is not a reflection of any design flaw. It is a response to temporary but intense imbalances in the support infrastructure that keeps modern fleets flying. When the support system lags, even the newest metal can become more valuable in pieces than as a whole.
That reality may feel counterintuitive. It also illustrates how tightly connected the various parts of commercial aviation have become. A problem in engine manufacturing or maintenance capacity does not stay confined to the engine shops. It ripples outward, influencing storage decisions, residual values, lessor strategies, and ultimately the physical fate of individual airframes sitting in the desert.
Practical Lessons From The Current Cycle
For anyone following the commercial aviation sector, several takeaways stand out. First, residual value assumptions that worked in previous cycles may need adjustment when maintenance backlogs grow unusually long. Second, the secondary parts market has matured into a critical safety valve for the entire industry. Third, storage is not a free option; prolonged parking carries real costs that can tip the scale toward teardown when other factors align.
Operators and lessors already factor these realities into their planning. Investors evaluating aircraft assets now routinely stress-test scenarios that include multi-year engine wait times. The firms that specialize in acquiring and dismantling airframes have refined their processes to extract maximum value from even young airframes. The ecosystem has adapted with surprising speed.
None of this means every young airplane faces the scrap yard. Far from it. The majority will continue flying for many years. But the threshold at which teardown becomes rational has moved. Airplanes that once would have been stored without question now receive closer scrutiny. When the numbers favor parts over preservation, the excavators move in.
Standing in the desert heat and watching the process unfold leaves a lasting impression. The scale of modern commercial aircraft still impresses even in disassembly. The care taken to remove high-value components before the final crush shows respect for the engineering that went into them. And the speed with which the remaining structure disappears into recycling streams reminds everyone how thoroughly the industry can repurpose its own assets when market conditions demand it.
The story of these early retirements is still being written. Engine production rates, overhaul capacity, airline traffic growth, and future fuel-price trends will all influence how long the current pattern lasts. For now, though, the sight of nearly new jets being reduced to components and scrap metal has become an unexpected feature of the landscape. It is a clear signal that the aviation industry is navigating a period of unusual constraints, and that those constraints are reshaping even the most basic assumptions about aircraft life cycles.
In the end the decision remains pragmatic. Owners weigh storage costs against parts values, wait times against immediate cash flow, and long-term residual assumptions against present-day market realities. When the balance tips, the metal that was never meant to be loved too much meets its early end. The engines keep other airplanes flying. The smaller components find new homes. The aluminum and steel return to the material stream. And the industry continues adapting, one carefully dismantled airframe at a time.
What once seemed almost unthinkable has become a practical response to the pressures of the moment. Young airplanes, built for decades of service, are leaving the fleet years ahead of schedule. The reasons are complex, the calculations cold, and the visual result still capable of surprising even seasoned observers. Yet within that surprise lies a clear illustration of how tightly the modern aviation ecosystem is connected, and how quickly it can reallocate value when circumstances demand it.
The desert facilities will continue their quiet work. Some airframes will wait patiently for better days. Others will yield their components and disappear into the recycling stream. Both outcomes serve the larger goal of keeping as many airplanes as possible airborne under difficult supply conditions. In that sense the early teardowns, however counterintuitive they may appear, form part of a broader effort to stretch limited resources across a global fleet that still needs to fly.
Watching the process up close leaves little room for romantic notions about aircraft longevity. The metal is a tool. When the tool’s highest remaining value lies in its individual pieces rather than its assembled form, the industry acts accordingly. That clarity of purpose may be the most human element of all in what otherwise looks like a purely technical and financial story.