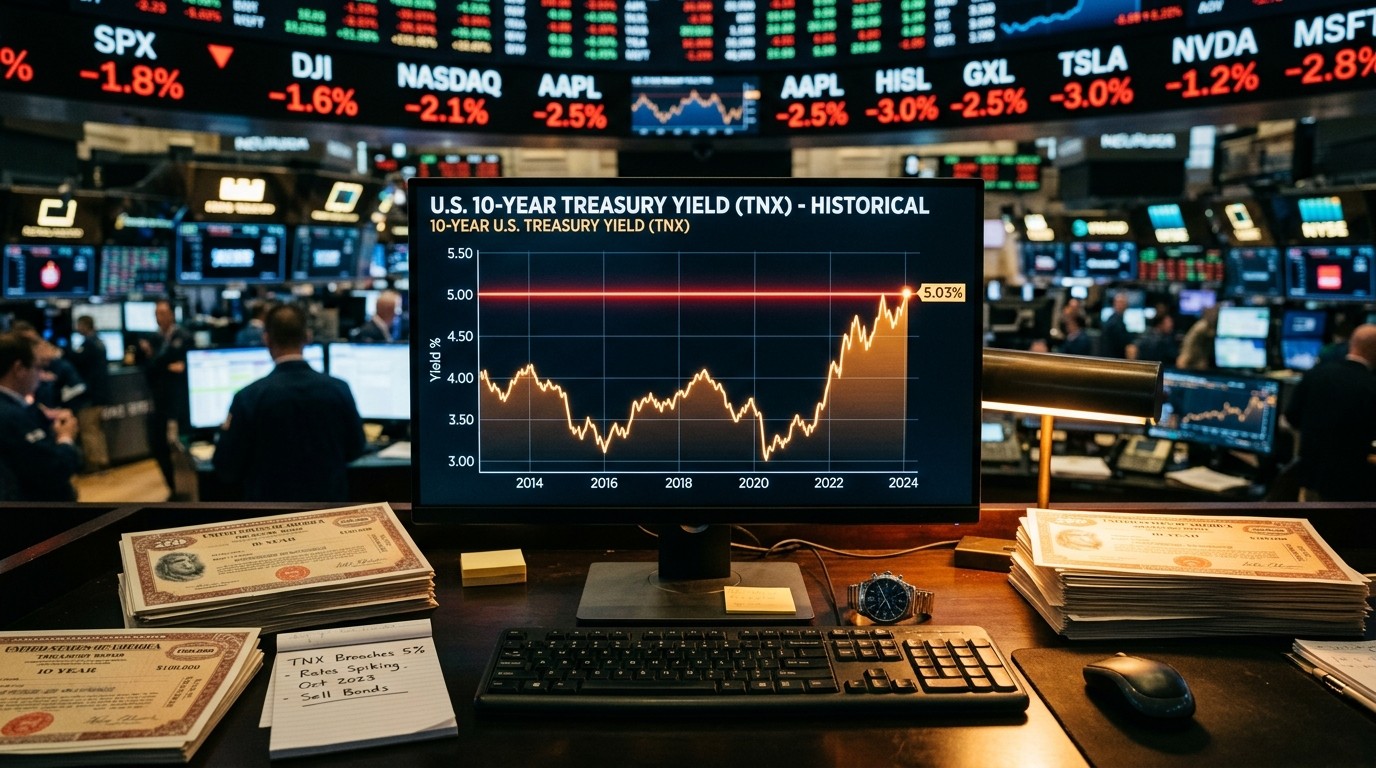

Have you ever watched a single number on a screen change the mood of an entire trading floor? That is how the 10-year Treasury yield feels right now. It is not flashy. It does not trend on social feeds the way a mega-cap earnings beat does. Still, it quietly prices mortgages, car loans, corporate borrowing, and the present value of every future profit investors hope to collect. When that yield flirts with 5%, people stop talking about easy money and start asking a harder question: what happens to stocks if this line actually breaks?
Why The 10-Year Yield Still Runs The Room
I keep coming back to a simple idea. Equities are a story about tomorrow. Bonds are a price on today. The 10-year note sits in the middle of that argument. It is long enough to matter for growth and inflation, short enough to move when policy or geopolitics shifts. Call it the world’s most important reference rate if you like. I do, at least on days when it jumps and risk assets look suddenly expensive.
That is not poetry. It is plumbing. When the 10-year rises, the discount rate used to value distant cash flows rises with it. A software platform promising fat profits in 2030 is worth less at 5% than it was at 3%. Same company. Same product. Different math. The AI trade lives on that distant cash-flow story more than almost any other corner of the market. So yes, a breakout in yields can hold stocks back even if earnings stay decent.
Earlier this week the yield tagged 5% and printed a level not seen in about nineteen years. It later eased a handful of basis points, settling near 4.94% on Thursday. A pullback is not a reset. It is a pause. Markets love pauses. They also love to treat a pause as proof that the danger has passed. I am not so sure.
The Five Percent Line Is More Than A Round Number
Round numbers are psychological. Five percent is also statistical. Some veteran investors argue that once the 10-year moves decisively above 5%, the usual inverse relationship between stocks and bonds can flip. Below that zone, falling yields often support equities. Above it, both can sell off together because the cost of money is simply too high for risk assets to shrug off.
If we do move into a new interest rate regime, where we decisively break 5% on the 10-year, that will pose a problem for equity markets in general and the AI trade.
– Market strategist commenting on valuation risk
Another way to say it: for yields north of roughly 5.25%, equity prices have historically struggled. That is not a law of physics. It is a pattern. Patterns break. They also repeat often enough that ignoring them feels sloppy. In my experience, sloppy is expensive.
How Higher Yields Hit Stock Valuations
Think of a stock as a bundle of future cash. You pull those cash flows back to today with a discount rate. Raise the rate and the bundle shrinks. Growth stocks shrink faster because more of their value sits far out on the calendar. That is why a yield breakout can look like a valuation tax on the most loved names in the tape.
It is not only about multiples. It is about competition. A 5% government yield is a risk-free alternative that did not exist, in practical terms, for years. Why stretch for a richly priced equity when a Treasury note pays you to wait? Some investors will still stretch. Others will not. The second group does not need to be huge to change the bid.
- Higher discount rates reduce the present value of long-dated earnings.
- Safer bond income competes with equity risk premia.
- Corporate borrowing costs climb, which can slow buybacks and capex.
- Household credit gets pricier, which can cool spending at the margin.
None of that means markets crash on a single print. It means the path of least resistance can flatten. Rallies get sold. Bad news gets punished faster. Good news needs to be better. That is a different market than the one that rewarded every dip for years.
Energy Shocks, Sticky Inflation, And The Policy Bind
Yields do not rise in a vacuum. Oil has been part of the story. Brent crude pushed through $100 last week. Diesel has been even more painful in some regions. Energy is not a side dish in inflation math. It is an ingredient that shows up in freight, food logistics, and household budgets. When energy inventories look tight and geopolitics looks messy, markets start pricing a longer inflation tail.
Inflation has now sat above the official 2% target for five years. That sentence should make anyone who lived through the last cycle sit up. The central bank lifted the policy rate by a quarter point this week, into a 3.75% to 4% range. Officials left the door open to another move later this year. The chair’s message was blunt enough: prices remain too stubborn.
Here is the awkward part. Policy makers have also sketched a path where inflation stays above target into 2029. If that forecast is even half right, the idea of a swift, clean cutting cycle looks optimistic. Markets can handle high rates if they believe the next step is down. They hate high rates that might still go up.
What Changes For The AI Trade
The AI complex is not a cartoon bubble in every name. Earnings have been real. Demand for compute is real. Capex is also real, and it is enormous. That last point matters more as the cost of capital rises. Building data centers, power, and chips is not a light-asset software story anymore. It is heavy industry with a software wrapper.
Research notes this week made a point that stuck with me. Higher cost of capital plus greater capital intensity can shrink the value of future cash flows even when current earnings look strong. In plain language, you can grow and still get a lower multiple. Some mega-cap names already trade closer to the market’s average forward earnings multiple than the premium they enjoyed when money was cheap.
There is another wrinkle. These companies are issuing more debt to fund infrastructure. That is rational if returns on invested capital stay high. It is less charming if yields keep climbing and free cash flow gets eaten by buildout. I have found that markets forgive ambitious spending in a falling-rate world. They get picky when the 10-year is knocking on 5%.
The combination of a higher cost of capital and greater capital intensity has reduced the value of future cash flows even as reported profits remain solid.
Fiscal Math Makes The Bond Market Less Patient
Public debt is no longer a background statistic. Servicing more than $40 trillion gets expensive fast when the 10-year jumps. Interest expense crowds other priorities. It also means the government is a larger, more persistent borrower. That competes with companies that need the same bond market.
Compare the 1990s, loosely. The public balance sheet was leaner. Corporate issuance exploded during the tech boom, but the sovereign bid for savings was not as heavy. Today the sovereign is three times more bloated by that older standard. If the 10-year gets “unhinged,” to use a phrase I heard this week, fiscal stress and market stress can feed each other.
Does that mean a crisis tomorrow? No. It means the margin for error is thinner. A yield spike that once felt like a trading event can start to look like a solvency conversation for the budget, even if default risk stays theoretical for a reserve-currency issuer.
Corporate Balance Sheets Are A Real Cushion
Fair is fair. Many large companies refinanced when rates were low. Interest coverage is healthier than it was in some prior tightening cycles. That is an important difference. A yield shock can reprice assets without immediately breaking the corporate sector.
Still, cushions expire. Floating-rate borrowers feel it first. Refinancing walls arrive later. Private credit and lower-rated issuers tend to show the bruises before the mega-caps do. If you only watch the biggest names, you can miss the stress until it migrates.
| Yield Zone | Typical Equity Mood | What Investors Watch |
| Below 4.5% | Supportive for duration-sensitive growth | Soft landing narratives |
| 4.5% to 5.0% | Choppy, valuation debates intensify | Inflation prints and issuance |
| Above 5.0% | Risk of joint stock-bond pressure | Discount rates and fiscal supply |
| Above 5.25% | Historically tougher for equity prices | Whether the break holds |
Mortgages, Autos, And The Everyday Economy
Wall Street talks in basis points. Households talk in monthly payments. The 10-year feeds mortgage pricing. It feeds auto loans. It feeds the hurdle rate for a small firm thinking about a new warehouse. If yields stay high, demand does not need to collapse to slow down. It just needs to hesitate.
Housing is the classic example. Affordability was already strained. A yield breakout does not help. Even if home prices stall rather than fall, transaction volumes can freeze. That hits related stocks: builders, brokers, lenders, furnishers. It is not dramatic. It is grinding. Grinding is how expansions lose momentum.
Perhaps the most interesting aspect is how uneven the pain can be. High-income households with fixed-rate debt keep spending. Younger buyers and rate-sensitive industries pull back. The average looks fine until it does not.
When Tightening Ends Booms
A lot of market booms rhyme. They do not end because a slogan gets old. They end when money gets expensive and the last buyer needs leverage. Monetary tightening is the common thread. That does not require a repeat of any single historical crash. It only requires that cheap capital stop papering over weak unit economics.
AI may still be the defining technology of the decade. I think it is. Technology leadership and market timing are different jobs. The first can be right while the second is early. Yields are one of the clocks that tell you whether you are early.
- Watch whether the 10-year can close and hold above 5%.
- Track real yields, not just the nominal headline.
- Compare mega-cap free cash flow with capex guidance.
- Listen to refunding calendars and auction tails in government bonds.
- Keep an eye on credit spreads, not only equity indexes.
Correlation Risk Is The Quiet Problem
Portfolio theory loves the idea that bonds rally when stocks fall. That hedge has been unreliable in inflationary regimes. If yields and equities start moving the same direction for the wrong reasons, a 60/40 mix behaves like a more concentrated bet. That is when “balanced” accounts feel anything but balanced.
I have sat through enough committee meetings to know how this conversation goes. Someone says diversification still works. Someone else pulls a chart from 2022. Then the room argues about whether this cycle is different. The honest answer is that it can be different until the 10-year decides it is not.
What A Breakout Would Actually Look Like
A brief poke through 5% is a headline. A breakout is a regime. You want to see acceptance: closes above the level, failed retests that bounce, auctions that need a higher yield to clear. You also want a reason that does not vanish in a week. Sticky services inflation. A hotter energy complex. Heavier Treasury supply. A central bank that cannot ease because the data will not let it.
If those pieces line up, equity leadership often narrows first. Then it rotates. Then it fades. Defensives can look boring and still win relative performance. High-duration growth can look brilliant on product news and still lose on multiple compression. That mix confuses people who only watch the index level.
How I Would Think About Positioning Without Playing Hero
This is not a call to abandon stocks. It is a call to stop treating 5% as trivia. Quality balance sheets matter more when discount rates rise. Cash-flow visibility matters more. Capex that earns its cost of capital matters more. Stories that require perfect conditions matter less.
Duration in the equity book is a real risk factor. So is refinancing risk in credit. So is fiscal supply in the bond market. You do not need a dramatic forecast to respect those three. You need humility about how fast valuations can reset when the risk-free rate jumps.
Simple yield checklist:
  1. Is 5% a spike or a floor?
  2. Are real yields still rising?
  3. Is AI capex self-funded or debt-funded?
  4. Is inflation cooling in the right places?
  5. Are credit spreads confirming the equity smile?
If the answers stay messy, cash is not a four-letter word. Dry powder is a position. So is patience. The market will offer better entry points if the 10-year truly breaks. If it does not, you can re-risk. That optionality is worth more than a heroic forecast.
The Human Side Of A Cold Number
It is easy to treat yields as an abstraction. They are not. They decide whether a family refinances. They decide whether a founder delays a hire. They decide whether a pension can meet a promise without taking extra equity risk. When commentators say the 10-year is the most important asset in the world, this is what they mean. It is the price of waiting, and waiting is most of economic life.
I still believe innovation can outrun a higher cost of capital over a long horizon. I also believe long horizons get interrupted by mark-to-market years. Those years are when people remember that valuation is not a vibe. It is arithmetic with a mood.
So keep the chart up. Watch 5%. Watch 5.25%. Watch whether stocks can make progress while that benchmark refuses to settle down. If they can, the market is telling you earnings power is strong enough to absorb the tax. If they cannot, the market is telling you the discount rate is back in charge.
That is the whole argument, stripped of theater. A breakout in the 10-year Treasury yield does not guarantee a bear market. It does change the burden of proof. Stocks, and the AI trade in particular, have to work harder for every extra multiple. In a world of sticky inflation, heavy public borrowing, and energy aftershocks, that extra work is no small thing.
Will the yield fail at the door and slip back? Maybe. Markets love to scare you and then apologize. I would rather plan for the case where it does not apologize. That plan starts with respecting the level everyone is already staring at, and with remembering that the cost of money is still the boss of almost every other story on the screen.