

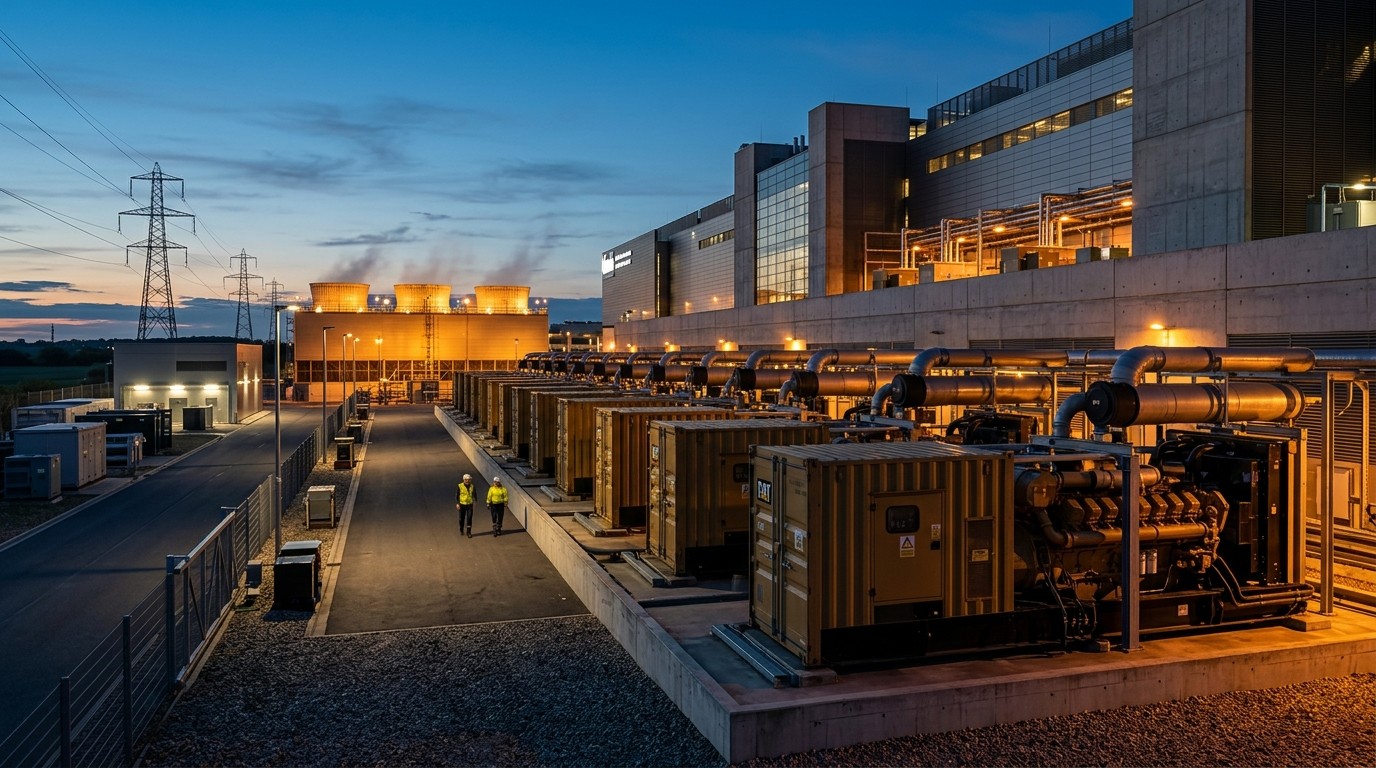

Have you ever watched a stock sit in a holding pattern for months, then snap awake because one contract suddenly made the whole story look different? That is roughly what happened with Generac stock after news of a long-term generator agreement tied to a major cloud operator. I have covered industrial names long enough to know that a headline can be louder than the cash flow. Still, this one feels heavier than a typical supply win. It is not just about machines. It is about who keeps the lights on when the grid cannot keep up with the next wave of compute.
Why The Amazon Generator Pact Hit Generac So Hard
Premarket trading did not wait for a polite explanation. Shares jumped by more than a third at one point, the kind of move that, if it holds through the close, would stand out as the largest one-day gain in years of available history. That is not a modest rerating. That is the market admitting it had been pricing almost no extra data center upside into the name.
The agreement itself is a multiyear supply arrangement for backup generators used at data centers. Warrants were issued as well, allowing the customer to buy up to about 1.69 million shares at a strike near $201. Those warrants vest as cumulative generator purchases climb, with a path that can reach as much as $8 billion of spend. About 18 percent of the warrants vest at signing. Initial deliveries are expected around $2.4 billion across 2027 and 2028, or roughly $1.2 billion a year.
In my experience, warrants are the part retail investors skim. They should not. A structure like this is a handshake that says the relationship is meant to last longer than the first two delivery years. Full vesting only arrives if purchases keep stacking toward that $8 billion figure. That is a long runway, not a one-off purchase order.
Visibility is the rarest asset in a capacity boom. A multiyear power contract is one of the few ways a supplier can turn a rumor into a schedule.
What The Numbers Actually Change
Before the announcement, one industrials desk had been modeling something north of $1 billion a year from the first wave of hyperscale and colocation work. The new initial schedule already sits above that older baseline. More important, the stock had been trading as if extra wins were optional. At roughly $175 before the news, some coverage argued the shares were worth closer to $185 if the company merely held a $1 billion annual run rate from early large-format deals. In other words, the tape was not paying for the next contract. Then the next contract arrived, and it was huge.
Another shop called the seven-year framework a massive win and estimated it could add more than 20 percent to total company EBITDA by 2028. That is the kind of increment that forces model rebuilds, not just a line-item tweak. Management had already said it wanted to triple large-format generator manufacturing capacity by August 2027. Investors had been asking a blunt question: who is going to buy all of that iron? This pact answers a chunk of that question in public.
Valuation context matters here. Prior to the announcement, the shares were changing hands near 10 times 2027 EBITDA even while some forecasts still pointed to more than 20 percent EBITDA growth over several years. Cheap growth is either a trap or a gift. After a contract of this size, the market usually spends a few sessions deciding which one it is.
Why Data Centers Suddenly Need So Many Generators
People talk about chips as if power were an afterthought. It is not. A modern training cluster does not politely wait for the local utility to finish a substation. Operators want backup that starts fast, scales in modular blocks, and sits on site before the next rack hall goes live. Diesel generator sets remain the workhorse for that job, even as longer-term conversations drift toward gas, batteries, and on-site generation of other kinds.
I keep coming back to a simple picture. Compute spending has been the loud part of the cycle. Power infrastructure is the quieter cousin that now has to catch up. When a thematic investor says reindustrialization is already underway and will take trillions, the public conversation usually jumps to factories and semiconductors. Fair enough. But factories do not run if the feeder lines and backup plants are missing. Data halls are even less patient.
- Hyperscale campuses are clustering in regions where interconnection queues already stretch for years.
- Backup generation is treated as insurance and as a construction milestone, not as a nice extra.
- Large-format units require factory space, engines, controls, and testing bays that cannot be improvised overnight.
- Customers want multiyear visibility so they can sequence halls without betting the schedule on a single shipment window.
That last point is why a seven-year outline matters more than a single quarter of bookings. Construction calendars in this industry slip. Permits slip. Transformers slip. A supplier that can point to a funded path through 2027 and 2028, with an implied tail beyond that, looks less like a cyclical toy and more like part of the buildout.
The Warrant Structure Is Not Window Dressing
Let us linger on the equity kicker, because it tells you how both sides think about duration. The customer can earn the full warrant package only if cumulative diesel generator purchases reach that $8 billion mark. A slice vests immediately. The rest is earned. That is alignment, not charity.
From the supplier side, you accept some potential dilution in exchange for a demand signal that justifies factory expansion. From the buyer side, you lock in a preferred manufacturing partner and pick up optionality on the equity if the relationship scales. I have found that markets often price the first-year revenue and ignore the optionality. That is a habit worth breaking on deals like this.
Does dilution matter? Of course it does. About 1.69 million shares is not nothing. But if the spend materializes toward the high end, the earnings power attached to those generators should swamp the extra share count. If the spend stalls after the initial $2.4 billion, the unvested portion never fully arrives. The structure is less a blank check than a scoreboard.
Capacity Expansion Suddenly Looks Less Reckless
Tripling large-format output by late summer 2027 sounded aggressive when the order book was still a patchwork of smaller wins and management color. It sounds less like a leap after a named, multiyear framework with a path to $8 billion. Factories are expensive. Idle bays are worse. The market had been applying a discount rate that assumed a decent chance the expansion would sit half-used. This announcement is designed to shrink that discount.
There is a practical layer too. Large generators are not assembled like consumer products. Lead times on engines, switchgear, and specialized labor can stretch. If you wait for every purchase order to land before you pour concrete, you miss the cycle. If you pour concrete too early, you burn cash. A contract with staged deliveries is the closest thing this industry has to a weather forecast.
The risk in a boom is not only missing demand. It is building the wrong amount of capacity for a demand path that was never written down.
I would still watch execution. Expanding output by that magnitude means hiring, training, quality control, and logistics. A missed delivery window on a data center campus can sour a relationship faster than a price dispute. The stock pop celebrates the booking. The next two years will celebrate, or punish, the shipping.
What The Market Had Been Worrying About
The shares had lagged for reasons that had little to do with residential standby generators, the product line many investors still associate with the brand. Policy noise around foreign-sourced grid equipment and engine supply had been hanging over the industrial book. Some coverage pointed to engine sourcing as a specific overhang. When a stock is already carrying that kind of political discount, a clean commercial win can look even larger because it changes the conversation.
There is also the broader debate about whether data center capital spending stays this hot. Skeptics argue that power constraints, higher rates, or a pause in model training could cool the boom. Bulls argue that the bottleneck has already moved from chips toward electricity, which would keep generator, switchgear, and turbine vendors busy even if server growth slows a notch. This pact does not settle that debate. It does show that at least one of the largest buyers is willing to pre-commit real money to backup power years ahead of delivery.
| Item | What Was Known | What Changed |
| Near-term deliveries | Loose estimates above $1B a year | About $2.4B slated for 2027-28 |
| Longer horizon | Unclear duration | Path toward $8B of cumulative spend |
| Equity overlay | None of note | Warrants vesting with purchases |
| Factory plan | Triple large-format capacity by 2027 | Demand now more visible against that plan |
| Street stance | Mostly constructive, some caution | Pressure for higher estimates and a lower risk premium |
How Analysts Are Framing The Rerating
Coverage on the name has been friendly for a while: a large cluster of buy ratings, a smaller group of holds, and no formal sells in the snapshot that circulated with the news. The average twelve-month target sat near the high $200s even before this pop. That gap between the old tape and the published targets is why the premarket move looked violent. The market was catching up to a story some desks had already sketched, then adding a new chapter on top.
One note stressed that the stock had not been reflecting much incremental data center value. Another argued the agreement should drive estimate revisions and a lower discount rate because visibility improved. Both can be true at once. Revisions lift the earnings path. A lower discount rate lifts the multiple applied to that path. Stack those two and you get a move that looks oversized if you only stare at next quarter.
Perhaps the most interesting aspect is not the day-one percentage. It is whether the multiple can stay richer if investors start treating large-format generation as a multiyear infrastructure sleeve rather than a storm-season afterthought. That shift in identity is worth more than a single print.
Residential Roots Meet Industrial Scale
A lot of long-time holders still think of the company as the brand on the pad next to a suburban house. That business still matters. Storm seasons, aging grids, and home backup remain real. But the valuation argument now leans harder on industrial and data center work. Mixing those two stories in one ticker is both a gift and a headache. The gift is diversification. The headache is that the market sometimes values the whole company on whichever segment disappointed last.
I have found that hybrid industrials get mispriced when a new end market arrives faster than the financials can show it. Early revenue looks small. Gross margins can wobble during ramp. Then, almost overnight, the new book becomes large enough to dominate the conversation. We may be in that awkward middle inning. The Amazon-linked volumes, if delivered on time, pull the industrial mix forward.
That does not make the residential franchise irrelevant. If anything, grid stress that pushes data centers toward on-site generation is the same grid stress that keeps homeowners shopping for standby units. Different customer, same underlying frustration: the wires are not keeping up.
Power Infrastructure Is Becoming The Real Bottleneck
Walk through any recent buildout discussion and you hear the same list: land, permits, substations, transformers, switchgear, generation. Chips still get the magazine covers. Electricity gets the construction meetings. Backup generators sit in a strange place on that list. They are not the long-term answer to baseload. They are the bridge that lets a campus open while the utility work crawls forward.
That bridge can last years. Interconnection queues in several U.S. regions are not a one-winter problem. If operators keep leasing and building ahead of firm utility capacity, on-site generation stays strategic. That is why a diesel-heavy contract in 2026 can still sit inside a decarbonization narrative. The machines are a schedule tool. The greener stack can arrive later without killing the current hall.
- Secure a site and a power story that lenders will accept.
- Order long-lead electrical gear and on-site generation in parallel.
- Energize halls in phases while the wider grid project continues.
- Revisit fuel mix, batteries, and longer-term generation once the campus is live.
Seen that way, the deal is less a bet on diesel forever and more a bet on construction physics. Physics is stubborn. Marketing slides are not.
Risks That Do Not Vanish After A 34 Percent Pop
It would be sloppy to treat this as risk-free. Customer concentration rises when one buyer can drive billions of spend. Execution risk rises when factories triple output. Policy risk does not disappear because a commercial contract was signed. Engine sourcing, emissions rules, and equipment-origin debates can still trip an industrial supplier.
There is also cycle risk. If data center construction pauses, the later years of an $8 billion path can stretch or shrink. Warrants that never vest are not a tragedy, but a factory built for a peak that never arrives is. I would rather see management keep some flexibility in the expansion plan than treat every square foot as destiny.
Currency of expectations is another quiet risk. After a gap-up like this, the stock starts needing clean updates. A delayed shipment, a softer residential quarter, or a cautious comment on 2029 could hit harder than the same news would have hit last month. That is the tax on a narrative upgrade.
How I Would Read The Next Few Updates
First, watch the conversion from announcement to backlog that actually ships. Dollar figures in a framework are not the same as units leaving the dock. Second, watch mix and margin. Large-format work can carry different profitability than residential standby, especially during a ramp. Third, watch commentary on additional hyperscale conversations. One landmark deal can be a beachhead or an island. The market will try to decide which.
I would also listen for language around service, parts, and long-term maintenance. Generators are not a fire-and-forget product on a campus that cannot go dark. A services tail would make the $8 billion story more than a capex spike. It would turn it into a relationship with recurring work attached.
Simple checklist after the pop:
  Delivery timing versus the 2027-28 window
  Margin through the factory ramp
  Extra large-format wins beyond the first buyer
  Policy and engine-supply headlines
  Whether the multiple holds after the first quiet week
What This Says About The Broader Trade
Investors have spent two years crowding into anything that touches compute. That crowded trade is now leaking into the unglamorous kit that keeps compute alive. Switchgear, transformers, turbines, fuel cells, and backup generators are no longer side notes. They are becoming the constraint trade. You can like that shift or distrust it. You cannot really ignore it if you care about industrial equities.
Is every power-adjacent stock a winner because one generator maker booked a landmark account? No. That would be lazy. Some firms have no capacity. Some have the wrong product. Some are already priced for perfection. The useful question is narrower: which suppliers can actually deliver large equipment on a data center clock, with a balance sheet that survives a lumpy ramp?
This particular name now has a public proof point. That proof point will be picked apart. Good. Markets should pick it apart. A 34 percent premarket burst is an invitation to do the work, not a reason to stop thinking.
A Cleaner Way To Think About The Stock From Here
Strip away the noise and you are left with three moving pieces. One, a visible slug of large-format revenue in 2027 and 2028. Two, a contractual path that can grow far beyond that slug if purchases keep accumulating. Three, a factory plan that now has a named source of demand sitting next to it. Everything else is interpretation.
I do not need the most optimistic case to find the news important. Even if cumulative spend stops closer to the initial delivery block than the $8 billion ceiling, the company has still converted a fuzzy data center narrative into something an auditor can eventually trace. That conversion is rare. It is also why the tape reacted the way it did.
Will the shares keep every point of that premarket gain? Maybe not. Opening spikes fade. Targets move. Competing suppliers will not sit still. Still, the underlying point survives a messy session: the power layer of the data center buildout is no longer a footnote. It is a procurement line item large enough to reprice an entire industrial name in a single morning.
If you follow Generac stock for the storm business alone, this is the moment to update the file. If you follow it as a proxy for on-site power at scale, this is the moment the proxy got a lot less theoretical. Either way, the next test is dull and decisive. Build the units. Ship the units. Keep the relationship from becoming a one-chapter story.
Contracts do not generate electricity. Factories do. The market just paid up for the belief that both sides of that sentence can stay in sync.
That belief will be tested in public, quarter after quarter. I would rather watch those quarters with a clearer demand map than go back to guessing which campus might place an order. Clarity is not the same thing as safety. It is still a better starting point than rumor, and rumor is what this name had been living on for too long.



