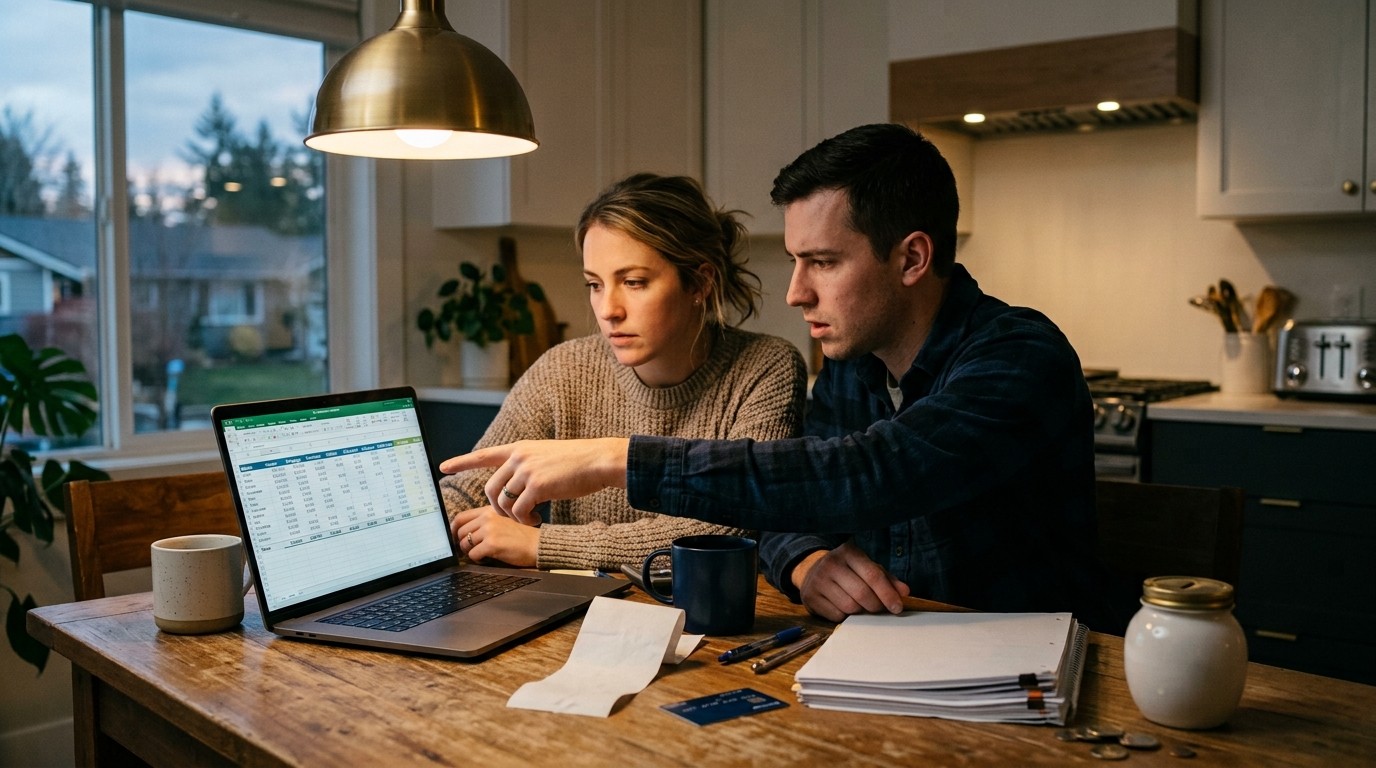

Have you ever looked at a combined household income that starts with a one and a five and still felt broke by Thursday? I have sat with that feeling more times than I care to admit. On paper you are “doing well.” In the grocery aisle, at the gas pump, and when the mortgage draft hits, it does not feel like winning. A millennial woman and her partner of nearly a decade recently described that exact gap. Together they land somewhere between one hundred fifty thousand and three hundred thousand dollars a year. They still pack coffee. She skipped the salon. Retirement contributions for this year? Zero. That last detail is the one that should make anyone pause.
I keep coming back to a stubborn fact. A six figure income used to sound like a finish line. Two decades of price pressure quietly moved the line. Consumer prices overall sit roughly sixty four percent higher than they did twenty years ago. Put another way, one hundred thousand dollars today buys what about sixty one thousand did back then. Groceries alone jumped more than twenty percent in just five years. So yes, the paycheck can look impressive and still leave almost nothing at the end of the month. Recent household surveys even suggest that about two in five people in the one hundred thousand to two hundred fifty thousand band still live paycheck to paycheck, and most of those folks have less than five hundred dollars left when the month closes.
When Good Money Still Feels Like Not Enough
The couple in this story is not reckless in the cartoon sense. They bought a house with less than the classic twenty percent down because that guideline felt like a fairy tale. Her partner asked the question a lot of people whisper: are we actually going to be able to afford this. She said she thought so. Then October mortgage payments started lining up next to more than thirty two thousand dollars in student loans and a three hundred forty dollar car note on a recent compact SUV. None of that is exotic. It is just stacked.
I don’t know how people do it and go on vacations.
That line stuck with me. It is not dramatic. It is tired. Lifestyle creep did some of the damage, sure. Streaming stacks, a gym she barely used, a fitness app that looked productive and felt unused. They cut Apple and Hulu. She canceled the gym. They switched weekly grocery runs for a warehouse club membership and started asking, before every swipe, whether a card would give something back. Small moves. Not glamorous. They still could not fund the future the way textbooks insist you should.
In my experience, the shame around this topic is almost as expensive as the bills. People earning well assume they are not allowed to feel squeezed. So they hide the tightness, keep spending like the brochure version of success, and delay the boring work of building a buffer. I would rather see a household get slightly uncool and slightly liquid than stay polished and one breakdown away from a credit card spiral.
The Quiet Math Behind The Squeeze
Housing ate the first bite. Then transportation. Then food. Then the debt that followed school. None of those categories moved in isolation. When several rise at once, a salary that looked generous five years ago starts acting like a tight costume. Add a partner who worries out loud about the mortgage and you get a household that is technically affluent and emotionally cautious. That combination is more common than dinner party talk admits.
Perhaps the most interesting aspect is how quickly “optional” spending becomes the only lever left. You cannot renegotiate the price of eggs by wishing. You can cancel the app you opened twice. You can stop treating takeout as a personality. You can move idle cash out of a near zero savings account. Those are not moral victories. They are arithmetic.
- Fixed costs rose faster than many raises.
- Student loans and car notes leave less room for error.
- Retirement gets postponed because it feels invisible compared with rent.
- Subscriptions and small treats add up without looking like a crisis.
I have found that couples who talk about money as a shared weather system, not a blame contest, recover faster. One person tracking every receipt while the other pretends the problem is vibes does not work. The pair in this story at least looked at the budget together and named what could leave. That is unglamorous partnership. It is also the start of a buffer.
Tool One: Make Idle Cash Work Harder
Suggesting a savings account to someone living paycheck to paycheck can sound like telling a thirsty person to buy a nicer glass. Hear me out. The point is not that you suddenly have a pile of money. The point is the habit of parking even a thin surplus where it earns something real instead of sitting at a national average rate that barely registers.
Traditional savings yields have hovered near pocket change. High yield accounts commonly sit in a different neighborhood, often around three to four percent. That gap is not theoretical. On a few thousand dollars it will not buy a vacation. On the first emergency it can mean the difference between using a card and using cash you already own. Starting deposits can be tiny. Some accounts open at a dollar. No monthly fee matters more than people admit, because fees are a quiet tax on people who are already tight.
Think of it as a separate pocket, not a second checking account you raid for takeout. Pair it with the bank you already use for bills. Transfer on payday, even if the number looks embarrassing at first. Embarrassing and growing beats proud and empty.
| Feature | Why It Matters When Money Is Tight |
| Higher annual yield | Idle dollars stop losing to inflation as fast |
| Low opening deposit | You can start before you feel “ready” |
| No monthly fee | Earnings are not nibbled away |
| Limited transactions | Friction that protects the buffer |
A dedicated savings pocket with no ATM card attached is, frankly, a feature. If you can tap it as easily as checking, you will. I have done that dance. The money vanishes into “just this once.” Make the once slightly annoying.
Tool Two: Cards That Pay You Back Without Turning Into Debt
The couple in the original story already does a version of this. Before they buy, they ask which card earns something. That question is more powerful than a complicated points spreadsheet. Rising grocery prices make the question urgent. Food at home is not a luxury category. If prices climb and you still pay with a card that gives nothing back, you are volunteering for a worse deal.
There are two useful flavors here. One is a simple flat rate. Two percent back on everything, split between the purchase and the payment, is boring in the best way. No category tracking. No calendar of rotating bonuses. If you pay the statement in full, you just collected a small rebate on life. If you carry a balance, the rebate is theater and the interest is the main character. Do not play that game.
The other flavor is category heavy. Some cards lean hard into supermarket spending, with a high rate up to an annual cap and a lower rate after that. Streaming credits show up on a few products too, which can offset a bill you were going to pay anyway. Caps matter. Read them. A six percent grocery rate that stops after a few thousand dollars is still useful. It is not infinite.
Then there is the emergency card with a long introductory period at zero percent. A broken transmission or a medical bill can wreck a household that has no cash cushion. Stretching repayment without interest for many months can be a bridge. It can also become a trap if the purchase was not an emergency and the balance is still there when the promotional clock ends. I am wary of using cheap credit as a lifestyle patch. I am less wary of using it as a shock absorber when the alternative is a high interest spiral.
- Pay the card in full whenever the purchase was planned spending.
- Use category bonuses on the bills you already have, not new wants.
- Keep one product for true surprises if you lack cash reserves.
- Watch foreign fees and transfer fees; they erase the “win.”
Rewards are not free money. They are a discount you keep only if you stay disciplined. I will say that again because marketing copy pretends otherwise. The household that treats a card like a coupon book does fine. The household that treats it like extra income does not.
Tool Three: Borrowing Against A Home You Already Own
This one is not for renters and it is not for brand new owners with almost no equity. If you have been paying a mortgage for a while, you may have a chunk of value sitting in the walls. A home equity line of credit lets you tap that value as a revolving line rather than a one time lump. Rates are often lower than credit cards because the house stands behind the loan. That is the feature and the risk in the same sentence.
Some lenders now run most of the process online and can fund in a handful of days. Draw amounts can run from modest five figure sums up to very large ceilings depending on value and credit. Draw periods and repayment periods vary. Origination costs, valuation fees, and recording charges are not theoretical. They belong in the comparison before you celebrate the rate.
I get uneasy when people treat home equity like a shopping account. Using a lower rate to clean up high interest debt, fund a necessary repair, or create a controlled bridge can be rational. Using it to paper over a spending problem just relocates the problem onto the roof over your head. Miss those payments and the conversation changes from annoying to existential.
Equity is not a bonus check. It is a second mortgage in nicer clothing.
Availability is not universal. Some states sit outside certain programs. Credit floors exist. Combined loan to value caps exist. The lowest advertised rates usually belong to the strongest files and the shortest terms. Your number will be your number. Shop as if the house depends on it, because in a way it does.
What The Couple Already Changed
They did not wait for a perfect system. They swapped store trips for bulk runs. They killed subscriptions that failed the “do I actually use this” test. They started routing purchases through cards that return something. They accepted that retirement would pause while the new housing cost settled. I do not love that last choice. I understand it. A household staring at a first mortgage payment in a few weeks will protect cash flow before it protects a target date fund. The work is to make the pause temporary, not a new personality.
Money conversations inside a long relationship get weirdly intimate. Who gets to feel scared. Who gets to sound optimistic. He asked if they could afford the house. She said she thought so. That is not a fight. That is two nervous people trying to share a future. Couples who skip that talk tend to invent secret resentments later. Better to be awkward at the table than silent for a year.
Build A Buffer Without Performing Wealth
Nobody needs a lecture about lattes. Plenty of tight six figure households already skipped the latte. The leak is often bigger and duller. Insurance you never compared. A car payment that assumed last year’s optimism. A grocery pattern built for a two person household that still shops like a dinner party is coming. Warehouse clubs help some people and tempt others into bulk waste. Know which one you are.
An emergency fund on a thin margin will not look like the textbook three to six months at first. Fine. Aim at one ugly surprise. A tire. A dental bill. A week of lost hours. Park that in the higher yield pocket. Then grow it. The psychological shift matters as much as the yield. Once you have seen money sit and earn a little, spending it on nothing feels less automatic.
A simple order of operations I keep coming back to:
  1. Stop the obvious leaks
  2. Route spending through rewards you will actually use
  3. Park leftover dollars where they earn
  4. Only then consider cheaper credit or equity
  5. Restart retirement as soon as cash flow allows
Notice retirement is not first. That will annoy some planners. Living people need a floor under their feet before they optimize a distant self. Just do not let “later” become the plan. Later has a habit of arriving overdrawn.
Inflation Changed The Meaning Of Success
We still talk about six figures as if the phrase were frozen in 2006. It is not. The same dollars buy less shelter, less food, less care for a car, less childcare if that is in the picture. Pair that with student debt that followed a generation into their thirties and you get households that look successful on a spreadsheet and exhausted in a kitchen at 9 p.m.
I do not think the answer is to mock people for wanting a house or a reliable vehicle. I think the answer is to stop pretending the old rules of thumb still fit every zip code. Twenty percent down is a nice target. It is not a moral exam. A long introductory rate on a card is a tool. It is not a personality. A high yield account is a habit. It is not a flex.
According to household finance researchers and recent consumer surveys, the paycheck to paycheck pattern now reaches deep into income bands that used to feel insulated. That should change the tone of advice. Less scolding. More mechanics. Less “just earn more” as the only sermon. More “here is how to keep more of what you already earn.”
Talking About Money Without Turning It Into A Scoreboard
If you share a life with someone, the budget is a relationship document whether you admit it or not. One partner doing all the tracking can breed quiet contempt. One partner spending as if the spreadsheet were optional can breed panic. Pick a monthly hour. Not a trial. An hour. Look at the same numbers. Decide what leaves. Decide what stays. Decide what the house is allowed to cost your future self.
I have found that naming a shared goal in plain language helps. “We want three thousand dollars that we do not touch.” That is clearer than “we should be better with money.” Clarity is kinder than vibes.
- Agree on a floor for cash before adding new fixed costs.
- Review subscriptions every quarter like they are on trial.
- Compare grocery tactics without turning dinner into a debate club.
- Write down the date retirement contributions restart.
None of that requires a personality transplant. It requires a little pride swallowed and a little curiosity about where the money actually goes. Most tight high earners are not mysterious. They are busy, slightly optimistic, and late to notice that five small leaks became a drain.
A Note On Debt That Follows You Home
Student loans sitting above thirty thousand dollars are not a side quest. They shape what a household can absorb. A car note on a new vehicle does the same. Neither is automatically foolish. Both reduce flexibility. If you add a mortgage on top, you need a plan for which balance shrinks first when extra cash appears. There is no single correct order for every couple. There is a wrong order, which is “none of them, because we were tired.”
Balance transfer windows and long purchase introductions can help if the fees do not eat the benefit and if the old habit that created the balance is already dead. Otherwise you just relocated the fire.
What I Would Do In Their Kitchen
If I were sitting at that table, I would not start with a lecture about compound interest. I would start with thirty days of ugly honesty. Every recurring charge on one page. Every upcoming draft dated. Then I would move whatever scraps exist into a higher yield pocket the same week. Then I would pick one card for daily spending that returns a flat or grocery heavy rebate and set autopay for the full statement. Then I would leave home equity alone unless a high interest balance or a necessary repair made the math obvious.
I would also put a calendar reminder three months out that says restart the retirement contribution, even at a tiny percent. Futures do not fund themselves. Present-tense fear is loud. Future-tense you has no vote unless you give them one.
Would that make vacations appear tomorrow? No. Would it make the next blown tire less of a personality crisis? Probably. That is the unsexy win available to households that look rich and feel poor.
The Feeling Is Common. The Response Does Not Have To Be Helpless
A six figure income can still feel tight. That sentence should not be controversial anymore. Prices moved. Debt lingered. Housing asked for more. Streaming and apps asked for a little forever. The household that notices and trims can build a sliver of slack. The household that performs ease while running hot will keep wondering why the vacation never fits.
Use the savings account as a habit, not a trophy. Use rewards as a rebate, not a reason to spend. Use equity as a last careful tool, not a lifestyle upgrade. Talk about the numbers with the person who shares the rent. Pack the coffee if that is what the season requires. Just do not confuse temporary austerity with a permanent identity.
The couple in this story wanted room to breathe and maybe, someday, a trip that does not require a spreadsheet apology. That desire is ordinary. The path toward it is a pile of small, slightly boring choices. I will take boring and solvent over impressive and brittle. Most kitchens would too, once the pride cools down.