

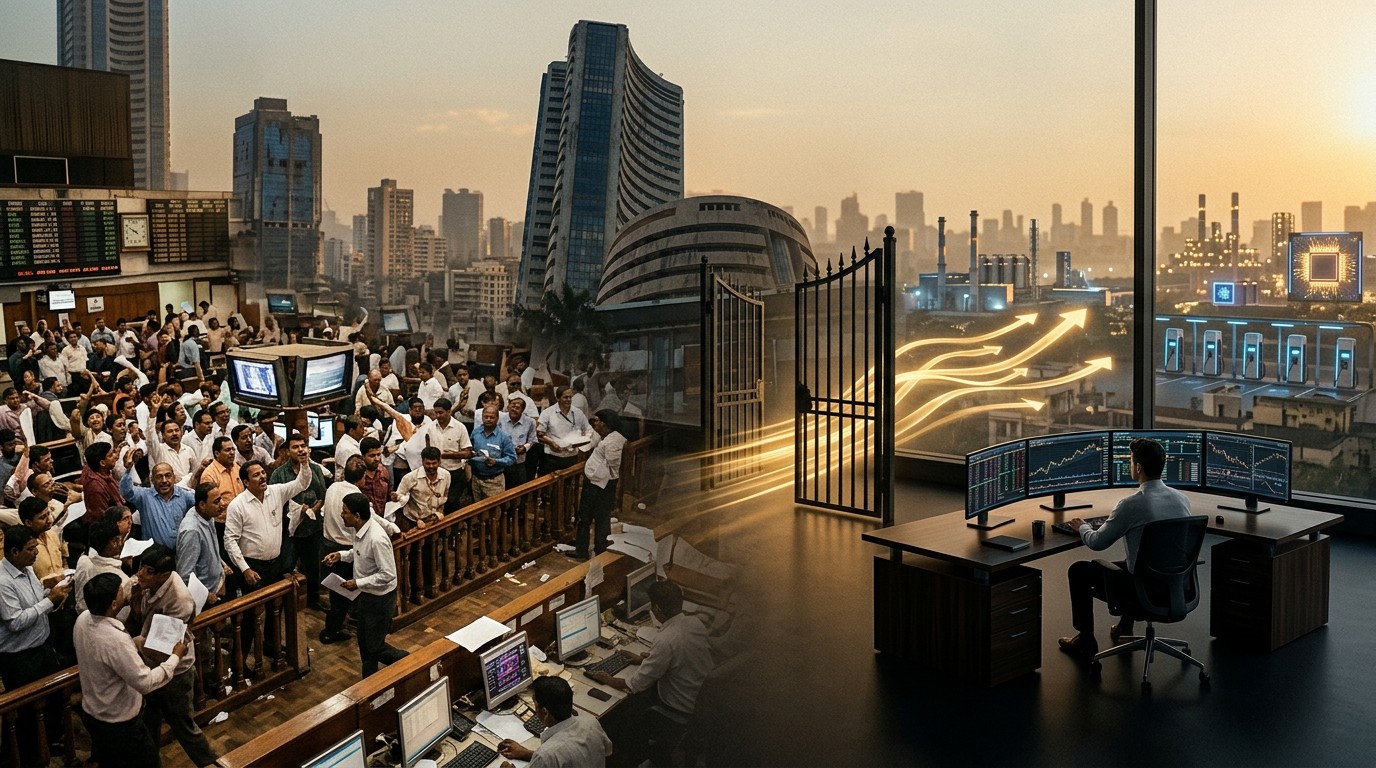

Have you noticed how a country can post impressive growth numbers and still watch its biggest stocks drift lower? That mismatch is sitting right in the middle of the India market debate right now. The economy keeps expanding at a pace most large nations would envy, yet the flagship large-cap names look tired, expensive, and oddly disconnected from the newer parts of the growth story. Foreign investors have noticed. After a short pause, they started selling again.
Why India Large Caps Feel Stuck In An Older Growth Model
I keep coming back to a simple idea. A stock market is not the same thing as an economy. That sounds obvious, but people still treat the two as twins. When the headline growth rate looks strong, the assumption is that the biggest listed companies should automatically enjoy the same lift. In India, that assumption is cracking. Many of the heaviest names in the benchmark were built for a different mix of demand, regulation, and global competition. They still matter. They still generate cash. They just do not look like the companies that will define the next decade.
A recent note from a global brokerage put it bluntly. Too many large corporates, it argued, represent a bygone economic era. The phrase is a little dramatic, sure. It also lands. These businesses are often consolidating what they already own instead of building what the country still lacks at scale: electric vehicles, advanced chips, and other capital-heavy technologies that need patient balance sheets. The deepest pockets are not always the most adventurous ones.
Many of the largest listed companies are protecting yesterday’s advantages rather than funding tomorrow’s capacity.
That is the heart of the current foreign-investor problem. If the index is packed with firms that do not offer the growth needed to justify rich multiples, large institutions start asking a blunt question: why stay?
The Valuation Problem Is Not Subtle Anymore
Indian equities have spent years trading at a premium to most emerging markets. Sometimes that premium made sense. Household formalization was rising. Credit was deepening. A young consumer class was spending more. The trouble starts when the premium stays high while earnings growth in the largest names stays ordinary.
Look at the flagship large-cap index. Since January it has fallen more than 10 percent, putting it among the weaker major markets this year. That is not a rounding error. It is a signal that price and narrative have drifted apart. I’ve found that markets can live with expensive stocks if the growth engine is visible. They struggle when the engine is elsewhere.
Several household names have been hovering near 52-week lows. A giant energy-to-retail conglomerate and the country’s largest private bank are both in that camp. Information technology firms, which still carry meaningful weight in the benchmark, are dealing with slower client spending and margin pressure as global buyers rethink software budgets in an artificial intelligence cycle. None of this means these companies are finished. It does mean the old comfort trade is less comfortable.
Foreign Investors Are Selling Again, And The Pause Was Brief
For two months, July and August, overseas portfolios looked like they might be turning a corner. They bought. Then September arrived and the selling resumed. Direct equity sales this month have already reached about $1.7 billion. For the year, the tally is close to $26 billion, the largest outflow run in the available record.
That number should not be waved away as noise. Foreign money does not need to hate a country to leave it. It only needs a better risk-adjusted story somewhere else, or a weaker one at home. In this case both forces are in play. Global capital has been pulled toward the AI complex in a handful of developed markets. At the same time, India’s most investable large names have not given visitors a clean reason to sit tight.
- Brief buying in midsummer did not reverse the yearly trend
- September selling restarted after that short pause
- Year-to-date foreign exits are near a record high
- The selling is concentrated in the most liquid large-cap names
Perhaps the most interesting aspect is how little the growth headline has helped. If strong GDP alone were enough, this outflow would have faded months ago. It has not.
The Economy Is Fast. The Benchmark Is Not The Same Thing
This is where the conversation usually goes sideways. People hear “fastest-growing major economy” and assume the Nifty-style large-cap basket should roar. But a lot of the activity that is actually changing the production mix sits in manufacturing, consumer technology, fintech plumbing, and smaller industrial suppliers. Those businesses show up more often in mid-cap and small-cap indexes.
Recent quarter numbers make the split hard to ignore. Average earnings growth for the large-cap benchmark landed around 11 percent. Mid-caps printed something closer to 31 percent. That is not a rounding difference. That is two different markets living under one national story.
| Segment | Recent Earnings Growth | What It Captures |
| Large-cap benchmark | About 11% | Established banks, energy, IT services, incumbents |
| Mid-cap cohort | About 31% | Manufacturing, consumer tech, newer demand pockets |
| Small-cap slice | Uneven but often faster | Niche suppliers, early-scale operators |
In my experience, this kind of split lasts longer than people expect. Indexes are sticky. Weightings change slowly. A company can be important to the real economy and still be too small, too illiquid, or too tightly held to become a serious home for global pensions.
Why Mid Caps Look Better But Still Fail The Institution Test
So why not just rotate down the market cap ladder? That is the first instinct, and it is not foolish. The growth is there. The sector mix is fresher. The problem is practical. Large institutional tickets need depth. They need free float. They need research coverage and an exit door that does not smash the price. Plenty of promising mid and small names still fail that test.
They remain sub-scale. Free floats are often thin. Liquidity fades the moment a few big tickets try to enter at once. Coverage is sparse, which makes risk committees nervous. You can admire a company and still be unable to own a meaningful position. That is the quiet constraint sitting behind the brokerage warning.
- Find businesses tied to the newer growth mix
- Check whether the float can absorb large orders
- Ask if daily liquidity survives a bad week
- Only then decide if the name is institution-ready
This is why the “just buy the mid caps” answer feels neat in a conversation and messy in a portfolio. Retail money can nibble. Sovereign-sized money cannot casually nibble.
Incumbents Are Consolidating The Past, Not Always Funding The Future
Let’s talk about behavior, because valuation is only half the story. The critique of large corporates is not that they are lazy in a cartoon sense. Many of them are operationally sharp. They defend share. They squeeze costs. They wait for policy cover when global rivals get too close. That last habit is the one that worries long-horizon investors.
If you expect the state to keep shielding you from competition, you invest differently. You buy what you already understand. You fold in smaller rivals. You do not necessarily build a semiconductor line or an electric-vehicle platform that might lose money for years. Capital stays inside familiar fences.
India still needs scale in those harder industries. Chips do not appear because a speech says they should. Battery supply chains do not assemble themselves. Someone has to write very large checks and live with very long payback periods. The firms with the deepest pockets are the obvious candidates. They have not, as a group, looked eager enough.
Policy can help a sector start. It cannot permanently replace private risk-taking at industrial scale.
One of the country’s most prominent groups is also tied up in a boardroom fight that could complicate plans around a first major fabrication effort. Governance drama is not a strategy. It is a delay with better stationery.
The Anti-AI Trade Tag Is Sticky For A Reason
India is often described as an anti-AI trade. That label is sloppy, but it is not invented out of thin air. There is no widely recognized local champion in frontier model building. The listed IT services complex, long a favorite overseas holding, now sits on the wrong side of a budget shift. Clients are testing tools that compress some of the work those firms used to bill by the hour.
Does that mean Indian software talent is irrelevant? Of course not. The talent pool is deep. The question for listed markets is narrower: which public companies capture the upside instead of eating the disruption? Right now the answer is fuzzy. Fuzzy answers do not attract hurried foreign inflows.
Here is the part people skip. Even if the global AI trade cools, money will not automatically swing back into Indian large caps. That hope is a little too convenient. Capital that left because the local opportunity set looked stale will not return just because another theme got tired. It needs a better local reason.
I’ve heard the opposite claim more than once: wait for the AI fever to break, wait for geopolitical noise to settle, and the bid for India will reappear like a train that was only delayed. Maybe. I would not build a strategy on that maybe.
What Foreign Portfolios Are Really Voting Against
Outflows get described as a mood. They are usually a verdict. The current verdict looks less like “India is broken” and more like “the listed large-cap menu is the wrong proxy for India’s next chapter.” That distinction matters. A country can still attract factories, consumers, and domestic savings while its benchmark struggles.
Domestic investors have often filled part of the gap. Systematic flows, household participation, and local institutions can support prices when foreigners step back. That support is real. It is also not infinite, and it does not erase valuation math. If earnings in the biggest names stay mid-teens at best while multiples stay rich, the market can grind sideways for a long time. Sideways markets feel like punishment when you arrived late.
- Growth is happening, just not evenly inside the index
- Liquidity still clusters in older large-cap names
- Domestic flows can cushion, not rewrite, the earnings story
- Foreign exits are a comment on investability as much as GDP
A Closer Look At The Earnings Split
Eleven percent versus thirty-one percent is the kind of gap that should force a rethink of index construction conversations. It does not mean every mid-cap is a bargain. Plenty of smaller names already price in heroic futures. Some of them will miss. That is how this usually works. The point is exposure. If the national growth mix is shifting toward manufacturing depth, digital consumer rails, and specialized suppliers, then a benchmark heavy on yesterday’s winners will keep disappointing people who bought the country story through that benchmark.
This is also why comparisons with other emerging markets can mislead. Two countries can print similar growth rates and still offer completely different listed opportunity sets. One might have export champions in the sectors investors want. The other might have banks, conglomerates, and service firms that were perfect for the last cycle.
Is that unfair to Indian large caps? A bit. Some of these firms still compound. A few will adapt. Adaptation, though, has to show up in capex choices and product mix, not just in conference-call adjectives.
Capital Allocation Will Decide Whether The Premium Survives
Every expensive market eventually has to answer the same question: what is the incremental dollar doing? If the incremental dollar is buying back the old empire, the premium shrinks. If it is building capacity the economy actually needs, the premium can last. Right now the public case for the second path is thinner than bulls admit.
Electric mobility is a useful example. Demand can rise and still leave listed incumbents poorly placed if the value sits with battery chemistry, power electronics, or software-defined vehicles they do not control. Semiconductors are an even harder test. A fabrication plant is not a press release. It is years of yield pain, talent wars, and customer qualification. You either fund that grind or you watch other countries do it.
What large-cap capital is being asked to do:
  Fund long-cycle industrial capacity
  Accept lower near-term returns
  Compete without assuming permanent policy cover
  Leave room for new listed champions to emerge
That list is easy to applaud and hard to execute. Boards like visible returns. Voters like visible factories. The calendar in between those two wishes is where markets lose patience.
Liquidity, Float, And The Hidden Friction In “Buy India”
People underestimate how mechanical foreign selling can be. A global allocator does not need a poetic thesis to cut an overweight. If the liquid names look expensive, if the mid-tier names cannot take size, and if the currency or relative-performance tape is unhelpful, the position shrinks. No villain required.
Low free float makes this worse. A company can be beloved and still be awkward to own. Promoter control is common. That can be a governance feature or a liquidity bug, depending on the week. Sparse research coverage adds another layer. Risk teams dislike stories that live in footnotes.
So the market ends up with a strange shape: too much money chasing a short list of giants, while the faster-growing layer cannot absorb the money that would validate it. That shape produces exactly what we are seeing. Weak benchmark performance plus a lively debate about “the real India” living somewhere below the top fifty names.
What Would Actually Bring Foreign Capital Back
Not a mood swing. Not a single good month. Not the hope that another region becomes less fashionable. The boring stuff would matter more.
- Clearer capex into technologies that need national scale
- Better float and liquidity in the next generation of listed firms
- Earnings growth in the benchmark that starts to resemble the economy’s faster pockets
- Less reliance on the idea that policy will permanently blunt global competition
- A handful of large, ownable winners in the newer industrial stack
None of that arrives on a timetable that fits a quarterly note. That is precisely why the current outflow can persist even while the macro brochure still looks glossy. Markets do not buy brochures.
Would cheaper valuations help? Obviously. Price is the fastest way to reset a debate. A cheaper large-cap complex would force fewer philosophical arguments. Even then, the structural question would remain: are these the businesses that compound through the next cycle, or the businesses that merely survive it?
How Domestic Investors Should Read The Same Tape
If you live and invest locally, foreign selling can look like an opportunity or a warning, depending on what you own. Blindly catching a falling benchmark because “foreigners are wrong about India” is not analysis. Sometimes foreigners are late. Sometimes they are early to a valuation problem everyone else is too close to see.
A more useful approach is to separate the country from the index. Ask which cash flows are tied to the parts of the economy that are actually gaining share. Ask whether you are being paid to wait in a high-multiple incumbent. Ask whether a mid-cap idea is truly a business or just a narrative with a ticker.
I’ve found that the cleanest mistakes happen when people treat national pride as a portfolio overlay. Pride is a fine feeling. It is a poor risk model.
A strong economy can still deliver a weak index if the index is a museum of the last expansion.
The Middle East Distraction And Other Convenient Excuses
Geopolitics always gets invited into these discussions. Fair enough. Risk premia move when oil spikes or shipping lanes get messy. Still, it would be a stretch to pin India’s large-cap lag mainly on events elsewhere. The more stubborn issue is homemade: the listed giants are not offering enough growth for the price they demand, and the faster names are not built for giant tickets.
Waiting for “the other story to fade” is a passive strategy dressed up as patience. If AI-linked trades cool, capital can go to cash, to other emerging markets, to quality compounders in developed markets, or nowhere in particular. There is no law that says it must visit Indian large caps next.
That is why the brokerage line about folly matters. The idea that money is simply parked outside the gate, engine running, waiting for one or two headlines to clear, flatters the local opportunity set more than the evidence does.
A More Honest Map Of The Opportunity
If I had to sketch the setup without the usual cheerleading, it would look like this. The macro backdrop remains one of the better large-country stories available. Formalization, infrastructure spend, and a young consumer base are not fictional. The public-market translation of that story is uneven. Large caps are carrying yesterday’s sector mix at yesterday’s confidence multiples. Mid caps carry more of the new mix and more of the liquidity headaches. Foreign investors, being size-constrained and relative-performance obsessed, keep choosing the exit.
That map can change. Markets do change when capex turns, when a few new names graduate into true large-cap liquidity, or when valuations finally reset enough to make ordinary growth acceptable again. Until one of those things happens, the gap between the growth brochure and the benchmark tape will keep producing the same argument every few weeks.
Is there room for selective optimism? Yes. Some incumbents will reinvent product lines. Some mid-sized manufacturers will earn their way into deeper institutional ownership. Domestic savings can keep a floor under quality names. Selective is the key word. Blanket optimism about the index is how people end up paying museum prices for companies that are no longer the main exhibit.
Practical Takeaways Before The Next Flow Print
Do not confuse a strong GDP print with an automatic large-cap rerating. Watch whether the biggest balance sheets start funding the hard industries instead of only defending old moats. Treat mid-cap growth as real but not automatically ownable at scale. And stop assuming foreign money is hiding just offstage.
The next flow number will get attention, as these numbers always do. A single week of buying will be called a turning point. A single week of selling will be called proof of collapse. Both readings are usually too loud. The quieter read is the one that lasts: India’s listed large-cap layer has not yet made itself the cleanest way to own the country’s next economic chapter.
That can change. It has not changed yet. And until it does, foreign investors heading for the door are not a mystery. They are doing what large pools of capital always do when growth, liquidity, and price refuse to sit in the same room.



