

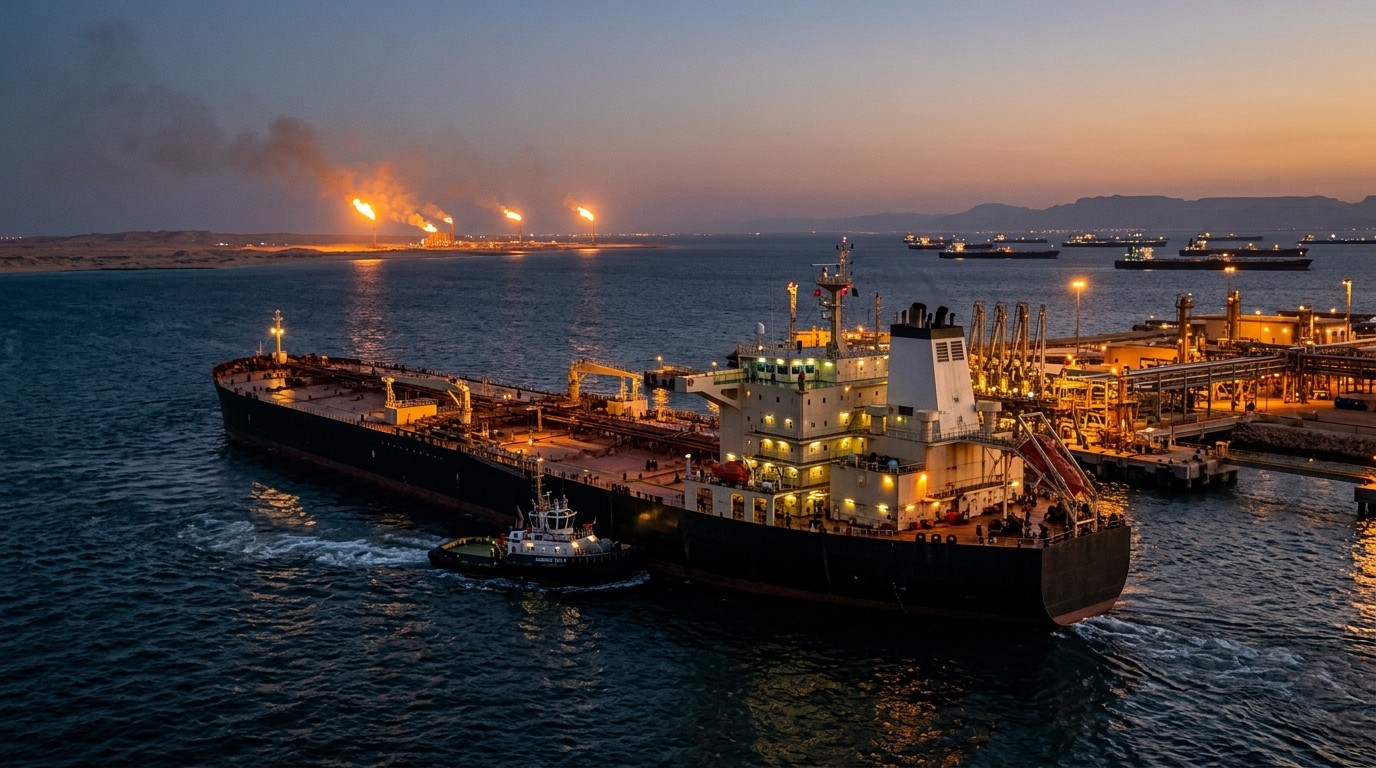
Saudi Arabia Reroutes Oil After Yanbu Port Strikes

Saudi tankers are stacking up in the Gulf while Yanbu sits under fresh threat. Loadings already plunged, Hormuz traffic thinned, and the next routing choice may decide how tight crude markets get.
Financial market analysis from 22/09/2026. Market conditions may have changed since publication.
Have you ever watched a market flinch not because demand vanished, but because one stretch of pipe and one Red Sea dock suddenly looked too risky to trust? That is the uneasy feeling hanging over crude right now. Saudi export planners are quietly pushing barrels toward Gulf terminals, stacking very large tankers where satellite photos can count them like parked trucks, and treating Yanbu as a destination that can no longer be taken for granted.
Why The Sudden Shift In Saudi Crude Flows Matters
I have followed Gulf shipping long enough to know that a routing change rarely arrives as a press release. It shows up as extra hulls at Ras Tanura, thinner crossings through the Strait of Hormuz on some days, and a loading number that looks nothing like the winter peak. The kingdom still has oil. The puzzle is how to get it to buyers without putting another high-value asset in the line of fire.
That puzzle got sharper after strikes linked to Yemen’s Houthi movement hit infrastructure tied to the East-West pipeline and later targeted the Yanbu complex itself. Officials said the Riyadh missile was intercepted and reported no casualties from the port attempt. Fine. Markets do not only price damage. They price the next attempt.
In my experience, energy traders shrug at one incident. They do not shrug when the backup route becomes the new front line. Yanbu was supposed to be the outlet that reduced Hormuz risk. Now the outlet itself is under pressure, and planners are improvising.
What Satellite Pictures And Loading Data Are Showing
Over a recent weekend, imagery of Gulf export terminals showed a cluster of supertankers with combined capacity around 14 million barrels. That is the kind of parking lot you see when barrels are being forced onto a narrower set of docks. It was the highest tanker count observed at those berths since at least June, according to commercial compilations of public satellite passes.
Oddly enough, Hormuz traffic did not surge in lockstep. Commodity vessel crossings fell to about a dozen over the same weekend, down from 35 a week earlier. One Thursday tally dropped to four tankers against a ten-day moving average near 16. That mix — more ships waiting in the Gulf, fewer ships actually leaving the strait — looks like congestion plus caution, not a clean reroute that already works.
Saudi crude moving through Hormuz still averaged roughly 2.9 million barrels a day over a recent six-day window. Analysts called that pivot the most notable among Gulf producers. I tend to agree. Other exporters tweak liftings. Riyadh is rewriting the map.
When the supposed bypass becomes a target, every barrel has to find a second door.
The Pipeline Hit That Forced The Detour
On September 11, drone strikes launched from Iraqi territory knocked the East-West line, also called Petroline, off its normal stride. That artery can move as much as 7 million barrels a day across about 1,200 kilometers from Eastern Province fields to Yanbu on the Red Sea. The attack took an estimated 4 to 5 million barrels a day of that capacity offline.
Total Saudi crude loadings tell the human story better than any slogan. Volumes that sat near 7.5 million barrels a day in January and February slid to about 2.1 million barrels a day by mid-September. That is a drop of more than 70 percent. You do not hide a hole that size in weekly averages.
A senior U.S. energy official said mid-month that the line could restart within days. An industry analyst speaking later was less cheerful: pump stations were destroyed, and a full return could take six weeks or more. I have found that the second estimate usually ages better. Pumps are not light switches.
Perhaps the most interesting aspect is timing. The pipeline was the kingdom’s insurance policy against a Hormuz squeeze. Insurance that fails in public has a way of changing buyer behavior faster than any speech.
Yanbu Under A Second Wave Of Threats
Overnight on September 18-19, the Houthi movement claimed cruise missiles, ballistic missiles, and drones against Riyadh and Aramco facilities at Yanbu. Saudi authorities confirmed that civilian infrastructure at the port — the place where the East-West line terminates — was targeted. They also said the capital-bound missile was intercepted and that neither strike produced casualties or confirmed damage.
That official calm is understandable. It is also incomplete. Yanbu had become the primary outlet after Gulf shipping grew politically expensive. Putting that outlet back in the crosshairs forces a choice: keep loading on the Red Sea and accept another attempt, or shove barrels east and live with Hormuz again.
Right now the eastward shove is winning. Crude is piped to Ras Tanura on the Persian Gulf, moved on smaller vessels into the Gulf of Oman, then transferred onto larger tankers. That relay is being used to shift about 60 million barrels loaded at Ras Tanura for September and October delivery, mainly toward Chinese and South Korean refiners.
Gulf exports as a group have climbed back to an average of 1 million to 1.5 million barrels a day, roughly in line with August. That rebound is real. It is also fragile. A relay involving ship-to-ship transfers is slower, costlier, and easier to snarl with weather, insurance clauses, or one more security scare.
How The New Routing Actually Works Day To Day
Think of Ras Tanura as a crowded train station after the express line closed. Barrels still arrive. Platforms fill. Then staff start using local trains and a transfer platform down the track. It gets the passengers moving. It does not look elegant.
Smaller ships shuttle crude from Gulf berths into deeper water. There, very large crude carriers take the cargo onward. Buyers in East Asia still get molecules. Freight desks get extra days, extra bunkers, and extra risk premia. Refiners get a schedule that slips a week and then another week.
- Pipe crude from eastern fields to Ras Tanura instead of pushing the full slate west.
- Load handy or mid-size tankers at Gulf terminals when VLCC berths are tight.
- Meet larger hulls in the Gulf of Oman for ship-to-ship transfer.
- Keep a smaller Red Sea program only if security desks sign off.
None of that is free. Ship-to-ship work needs calm seas, extra tugs, extra inspectors, and owners willing to put a billion-dollar hull next to another hull in contested water. Some owners will do it for a fatter rate. Some will not. That split alone can cap how fast the workaround scales.
What The Loading Collapse Means For Prices And Buyers
A 70 percent drop in Saudi loadings is not a rounding error. Even if inventories and spare capacity elsewhere cushion the first weeks, the quality mix changes. Asian refiners that booked light Saudi grades for autumn runs now hunt substitutes. Substitutes are not perfect twins. Yields shift. Margins wobble.
I keep coming back to a simple question. If mid-September loadings sit near 2.1 million barrels a day, how much of the lost volume is delayed rather than lost? Delayed barrels still arrive, just later and often on different ships. Lost barrels mean fields throttle or storage fills until something breaks.
Storage can hide a lot. It cannot hide a multi-week pump-station rebuild and a port that attackers have already tried to hit twice in spirit if not always in steel. That combination is why the tanker pile-up in the Gulf matters. It is visible proof that barrels are being forced through a narrower door.
| Checkpoint | Recent reading | Why it matters |
| Winter peak loadings | About 7.5 million bpd | Baseline before the disruptions |
| Mid-September loadings | About 2.1 million bpd | Shows the scale of the squeeze |
| East-West lost capacity | 4 to 5 million bpd offline | Removes the Red Sea escape hatch |
| Hormuz Saudi flow | About 2.9 million bpd recently | Marks the eastward pivot |
| Ras Tanura program | About 60 million barrels queued | Near-term Asian supply bridge |
Hormuz Traffic Looks Thin For A Reason
People sometimes treat the strait like a tap. Open it, close it, done. Reality is messier. Insurers reprice. Naval escorts change patterns. Captains wait for daylight. Charterers delay a fixture rather than send a hull into a week that already looks ugly on the risk memo.
That helps explain why crossings can fall even while terminals fill with waiting tonnage. Ships gather. They do not all leave on the same tide. A dozen commodity vessels one weekend, after 35 the week before, is not a mystery if security desks are staggering departures.
Thursday’s four-tanker print against a 16-tanker average is the kind of print that makes freight desks sit up. One quiet day is weather. A cluster of quiet days is policy, fear, or both.
I’ve found that the market often misreads a quiet strait as “nothing is moving.” Sometimes nothing is moving because everyone is waiting for the same all-clear that never quite arrives.
Who Still Gets The Barrels, And Who Waits
The September-October Ras Tanura program is aimed largely at China and South Korea. That is not an accident. Those systems run large, flexible slates and have spent years building commercial ties that survive ugly headlines. They can absorb a late cargo better than a smaller refiners’ co-op staring at a blank jetty next Tuesday.
European and Red Sea-adjacent buyers sit in a different queue. Yanbu was their convenient door. If that door stays half-shut, they lean on other grades, longer hauls, or inventory. Longer hauls mean more tonnage tied up. More tonnage tied up means freight can firm even if headline crude looks well supplied on paper.
There is a blunt commercial truth here. Priority customers get the workaround. Everyone else gets a phone call and a revised laycan.
Repair Timelines Versus Market Timelines
Official optimism talked about days. Field-level caution talked about six weeks or more. Those two clocks almost never match, and traders live on the second one. A destroyed pump station is civil engineering plus security plus spare parts plus a decision that it is safe enough to put crews back on site.
Six weeks in oil is a full prompt cycle and then some. Refinery maintenance plans, futures rolls, and shipping fixtures all sit inside that window. If restoration slips past the optimistic date — and it often does — the Gulf relay stops looking temporary.
Would I bet the farm on a snap restart? No. I would watch whether tanker counts at Gulf terminals stay elevated after the first promised restart date. Persistence in those photos would tell you more than any podium remark.
Security Risk Is Now Part Of The Freight Bill
War-risk premiums do not need a confirmed hit on a berth. They need a credible claim, a flight path, and a terminal name that underwriters already circle in red. Yanbu now has that circle. Ras Tanura has long had its own. The difference is that Ras Tanura still has water deep enough and customers hungry enough to keep the queue moving.
Crews notice this stuff. So do shipowners’ boards. A vessel that can earn a quieter Pacific run may simply refuse the Gulf of Oman transfer window. That refusal does not show up in a ministerial briefing. It shows up as a fixture that fails and a cargo that sits.
- Underwriters reprice voyages touching Yanbu or the transfer zone.
- Owners demand extra security language in charter parties.
- Some hulls exit the niche, tightening available tonnage.
- Effective freight rises even if the Worldscale print looks sleepy.
That chain is dull until it is not. Then a refiners’ purchasing manager discovers that the cheap option on the screen cannot actually be delivered.
Why This Is Not Just Another Gulf Headline
Gulf producers have lived with security risk for decades. What changed is the pairing of a disabled cross-kingdom pipeline and a follow-up strike package aimed at the Red Sea terminus. One event is an incident. Two events in the same corridor look like a campaign against the bypass.
If the bypass is the target, Hormuz is no longer the only chokepoint that keeps energy desks awake. You now have two doors, and both can be leaned on in the same month. That is a nastier map than the old textbook sketch.
In my view, that is the piece casual coverage keeps underselling. The story is not only “tankers in the Gulf.” The story is that the spare route was supposed to make the first route less scary. Instead, both routes are in the conversation at once.
Redundancy only works when the backup is quieter than the main line. Right now it is not.
Storage, Spare Capacity, And The Limits Of Comfort
Yes, the world has inventories. Yes, other producers can lift a bit more if prices pay them to. Those buffers are why the first week after a disruption often looks strangely calm on the screen. Calm on the screen is not the same as calm in the logistics chain.
Saudi grades have regular buyers for a reason. They are consistent, well understood, and contracted deep into refining systems. Swap them in a hurry and you change hydrogen content, residue yield, and sulfur handling. A procurement team can do it. A procurement team would rather not do it two months in a row.
Spare capacity also has a personality. It is not a tap in a warehouse. It is fields, crews, and politics. Assuming it appears on schedule is how people get surprised in week five.
What To Watch Over The Next Few Weeks
Forget the noise. Watch a short list and you will stay ahead of most recaps.
- Do Gulf terminal tanker counts stay near that 14-million-barrel capacity cluster?
- Does Hormuz crossing traffic normalize toward the prior moving average?
- Do Saudi loadings climb off the 2.1 million barrel-a-day floor?
- Is there hard evidence that East-West pump stations are actually turning?
- Do additional claims against Yanbu appear even if damage is denied?
If tanker counts stay high and loadings stay low, the reroute is still a bottleneck, not a solution. If crossings recover and Yanbu stays quiet, the market will start treating this as a nasty September rather than a new normal. I know which tape I would rather see. I also know which tape we have today.
A Practical Reading For Anyone Holding Energy Risk
You do not need a war room to use this. If you refine, you map which cargoes can slip and which units cannot. If you ship, you price extra days and extra clauses. If you invest, you separate “oil in the ground” from “oil on the water.” Those are different assets this month.
Equity headlines will swing with every intercepted missile. Fair enough. Cash flow, though, will follow loadings, freight, and whether Asian term buyers keep taking Ras Tanura barrels without renegotiating everything in sight.
There is also a quieter second-order effect. When a producer of this size reroutes, smaller Gulf loaders copy the caution even if their own docks were never hit. That is how a local security story becomes a regional shipping story. I have seen that copycat caution before. It is boring until the fixture list thins out.
The Human Side Of A Logistics Problem
It is easy to talk in million-barrel increments and forget the people on the jetties. Terminal staff still clock in. Surveyors still climb tanks. Crews still sleep on vessels that insurers now treat like rolling liabilities. A “no damage, no casualties” statement is good news. It is not the same as a normal night watch.
That human friction slows paperwork. Slow paperwork slows sailings. Slow sailings show up later as a late discharge in Ningbo or Yeosu and a refiner who has to buy a prompt replacement barrel they did not want.
Maybe that sounds small next to geopolitics. It is not small if you are the person who has to explain a missed cargo to a plant manager.
Putting The Pieces Together Without The Hype
Here is the sober version. A major cross-country pipeline lost most of its useful capacity after strikes on pump infrastructure. Loadings collapsed from winter highs. The Red Sea terminal that was meant to replace Hormuz exposure then drew its own claimed strike package. Planners answered by crowding Gulf docks, shuttling crude to the Gulf of Oman, and pointing the big ships at East Asia.
Hormuz did not suddenly become busy in a healthy way. Some days it looked almost empty. That is the tell. The system is moving barrels, but it is not moving them with confidence.
Will prices scream higher tomorrow morning solely because of this? Not necessarily. Inventories and demand wobble too. Can the market pretend Yanbu is still a clean insurance policy? Not honestly. That policy just got a deductible the size of a pump station and a premium paid in extra tanker days.
I keep a simple rule for stories like this. If the pictures of parked supertankers and the loading table disagree with the soothing quote, believe the pictures and the table. Right now they both say the same thing. Saudi Arabia is rerouting because the old path looks exposed, and the new path is crowded, slower, and still not safe in any absolute sense.
That is not a reason to panic. It is a reason to stay awake. The next useful signal will not be another slogan. It will be whether those Gulf hulls finally sail, whether Yanbu goes quiet, and whether 2.1 million barrels a day was a floor or a preview.
The successful investor is usually an individual who is inherently interested in business problems.


India Large Caps Lag As Foreign Investors Exit Equities

Hana Bank Upbit Travel Rule Crypto Transfers Explained
Related Articles

Ethereum Price Dips Below $3K: Capitulation Ahead?
Ethereum just slipped below the all-important $3,000 mark, turning a key support into resistance. With bearish structure still dominant and liquidity waiting lower, many are asking: is a sharp capitulation toward $2,500 on the horizon? Here's what the charts are really saying...

White House FBI Probe Into Missing Scientists Raises Questions
The White House just confirmed it's working with the FBI on a full review of multiple cases involving missing and killed scientists who handled highly sensitive nuclear and aerospace materials. With one general vanishing in broad daylight and others dying under strange circumstances, many are wondering if these events are truly random or part of something larger. The latest updates point to...

Lab Leak Proponent Steven Quay Tipped for Fauci’s Former NIH Role
With Tony Fauci facing fresh scrutiny and documents surfacing from his time leading the response, a prominent voice on the lab-leak hypothesis is reportedly in line for his old job at the NIH. What changes could this bring to how America handles risky virus studies?