


Have you ever stopped to think about how a dull grey metal most people never see can quietly decide whether factories, jets, and machine tools keep running? That is where we are with tungsten. South Korea has now given final administrative clearance for commercial processing at the Sangdong mine, and the timing is not subtle. China has been tightening the tap. Western buyers have been hunting for ore that does not arrive with a single-country choke point attached. And one Canadian-listed miner with a Korean asset suddenly looks a lot more relevant than it did two years ago.
Why This Approval Changes The Tungsten Map
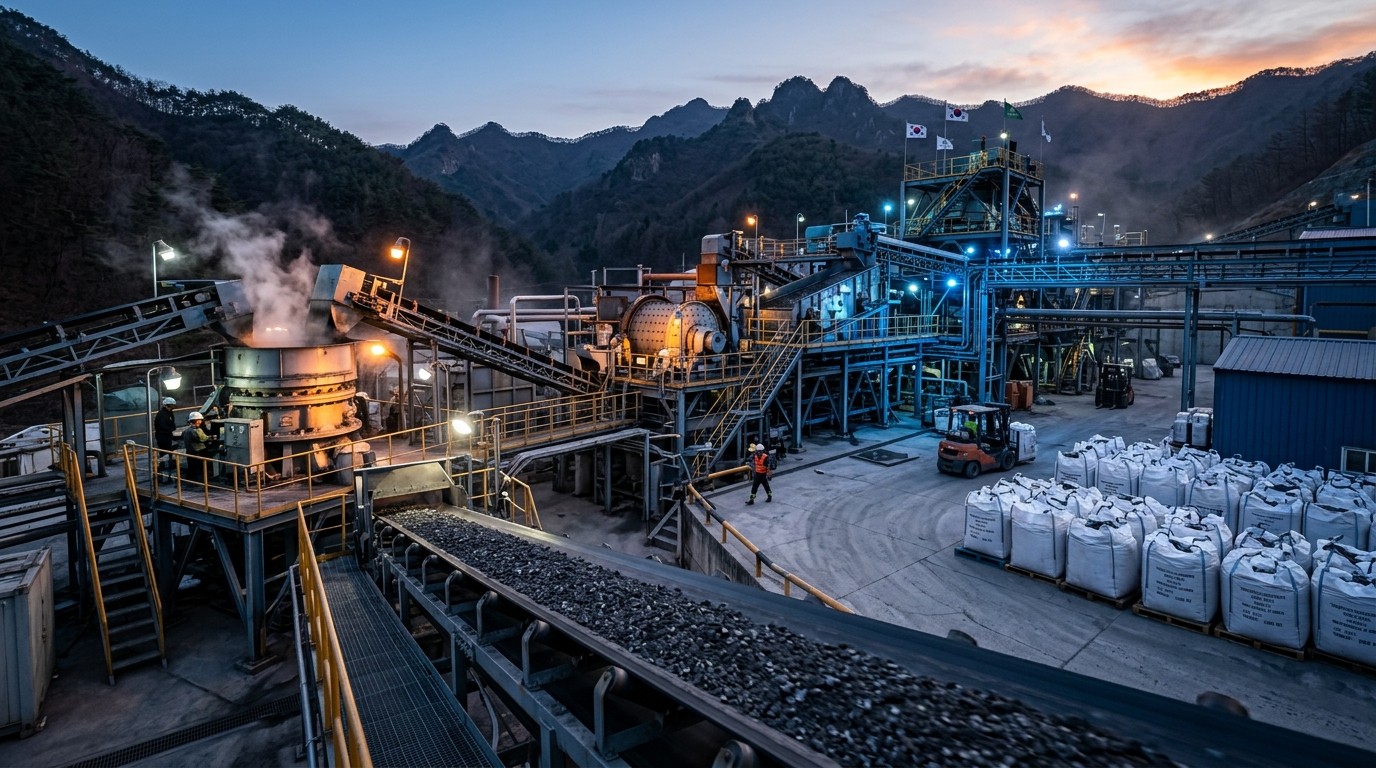
Last week’s inspection certificates were not a ribbon-cutting photo op. They authorize commercial operation of the processing plant and crushing facilities. In plain language, mined rock can now be turned into saleable concentrate for domestic users and, more importantly, for Western customers who have spent the last year and a half watching traditional supply routes get thinner.
I’ve found that people treat mining permits as paperwork. They are not. They are the last gate between a construction site and a business that can invoice. Sangdong has spent years in that awkward middle zone of trial runs and commissioning. The certification is the final step from build-out to commercial production. That sentence sounds bureaucratic. It is actually the difference between a story and a shipment.
A Contract Book That Already Looks Crowded
Here is the part that should make procurement desks sit up. More than 90 percent of Phase I output is already spoken for. A long-term offtake with Global Tungsten & Powders, part of Austria’s Plansee Group, now stretches 21 years from first delivery. Total contracted volume sits at 4.41 million metric tonne units, with minimum annual volumes of 210,000 MTU after ramp-up.
With more than 90 percent of our Phase I production already contracted for 21 years from first delivery, the task in front of us is a simple one: operate the plant safely, ramp it steadily and deliver.
– Company leadership after the certificates were issued
That is not a speculative pitch deck. That is a plant with a buyer list. In my experience, offtake length matters more than a single quarter of headline grade. Twenty-one years is a long time to be wrong about demand. It is also a long time to be useful if Western rearmament and industrial policy keep doing what they have been doing.
China Tightens, Defense Rules Tighten Faster
Tungsten prices have been sitting at historic highs for a reason. Export controls from the dominant producer do not need to be a total ban to scramble markets. A license delay here, a quota there, and suddenly toolmakers and alloy shops start paying up for any parcel that can clear compliance. Add a Western rearmament cycle and you get urgency that geology alone cannot satisfy.
There is another clock. From January 2027, United States defense procurement rules will look all the way back to where the ore was mined. Not just where it was melted. Not just the last processor on the invoice. The mine itself. That is a brutal filter. Few deposits can answer that question with a Western-aligned address and enough scale to matter. Sangdong is being sold as one of those few. I think that claim is directionally fair, even if ramp risk is still real.
What Tungsten Actually Does When Nobody Is Watching
If you only know tungsten from a trivia night about light-bulb filaments, you are missing the industrial plot. The metal’s melting point is extreme. Its density is extreme. Carbides made from it keep cutting tools sharp when steel would surrender. Armor-piercing cores, high-temperature alloys, vibration-damping weights, electronics heat sinks: the list is not glamorous, but it is load-bearing.
That is why a supply squeeze does not show up as a consumer headline first. It shows up as a delayed milling line, a more expensive insert, a longer lead time on a defense part. Perhaps the most interesting aspect is how invisible the metal stays until it is scarce. Then everyone pretends they always cared about concentrate grades and MTUs.
- Cutting tools and wear parts that keep factories moving
- High-temperature alloys used in demanding engines and turbines
- Defense applications where density and hardness are not optional
- Electronics and lighting niches that still need thermal stability
None of that makes tungsten a meme metal. It makes it a bottleneck metal. Bottlenecks get political. They also get priced.
Sangdong’s Place In A Thin Western Roster
Almonty has been framing itself as the leading Western tungsten producer once Sangdong’s Phase II expansion lands and the operating Panasqueira mine in Portugal is extended. That is ambition with a map attached. Phase I processing capacity has been described around an initial 4,000 tons a year of higher-value product, later stretching toward 6,000 tons. Those numbers will be argued over by analysts. The direction is what matters: concentrate first, then more value added on site if the plant behaves.
South Korea is not a casual address for this story. The country sits inside allied security architecture and has a serious industrial base of its own. A mine that can sell locally and still feed Western converters is a different animal from a remote pit that needs three intermediaries and a prayer.
Speed Beats Perfection When The Clock Is Already Late
Last week the company also struck a foothold deal with Rwanda’s government in Africa’s largest tungsten-producing nation and looked again at Spanish mine waste. Those moves are not romantic. They are admissions that greenfield mines take years the market does not have. Waste retreatment and brownfield access are how you put units on a truck while a flagship plant is still learning its own quirks.
The West needed new supply yesterday. That sentence is overused in commodities. In this case it is uncomfortably close to accurate. You cannot legislate a deposit into existence in eighteen months. You can permit a plant that already exists. You can sign offtakes. You can scrape tailings. That is the unglamorous toolkit.
| Lever | Time To First Units | Strategic Value |
| Sangdong commercial plant | Near term after certificates | High volume, allied jurisdiction |
| Portugal mine extension | Measured, existing operation | Western production already running |
| African foothold | Faster than a new pit | Access to a major producing country |
| Spanish waste | Potentially quickest incremental feed | Units without a full mine build |
The Share Price Has Already Had A Mood Swing
Almonty shares pulled back toward the mid-teens after a rally stalled near the high teens. The stock remains well below its April peak in the low twenties and has been living in a restless $15 to $20 band. Premarket trade popped a little over three percent on the approval news. That is not a verdict. It is a shrug that says the market heard the certificates and still wants to see tonnes.
I have watched enough mining names to know the pattern. Permits lift the story. First concentrate tests the story. Steady monthly output either kills the skeptics or feeds them. Anyone treating last week as the finish line is early. Anyone treating it as irrelevant is late.
Ramp Risk Is The Quiet Character In This Play
Processing plants do not always behave on day one. Crushers jam. Recoveries wander. Water balances surprise people who thought the pilot plant told the whole truth. Sangdong now has permission to operate commercially. Permission is not a metallurgical guarantee. The company’s own language is cautious in a useful way: operate safely, ramp steadily, deliver.
That sequence is the whole job. If recoveries hold and the offtake counterparty takes product as written, Sangdong becomes a reference asset for Western tungsten. If the ramp stutters, the 2027 defense clock will feel closer than the press release implied. Both outcomes are still on the table. Pretending otherwise is how retail investors get whiplash.
- Stabilize crush and grind so the plant sees consistent feed.
- Prove concentrate quality that converters will accept without endless penalties.
- Hit the contracted minimums after ramp without heroic one-off months.
- Keep expansion talk tied to actual plant performance, not slides.
Decoupling Is A Slogan Until Someone Ships Concentrate
Everybody talks about decoupling. Few commodities make the slogan this concrete. Tungsten processing and mining are concentrated. When the largest supplier leans on exports, buyers discover how few alternative addresses they actually have. A Korean plant with a long Austrian-linked offtake is not a complete answer to that problem. It is a visible crack in the old pattern.
Will one mine rewrite global trade? Of course not. Will it give toolmakers and defense suppliers a parcel they can put on a form without blinking? That is the more honest prize. Policy people like grand maps. Plant managers like bags that assay clean. Guess which group pays the bills.
Sangdong is one of very few assets anywhere that can answer the origin question with a Western address and the scale to matter.
That line will be repeated. It should be stress-tested against monthly production, not against adjectives.
What Buyers And Investors Should Watch Next
Forget the victory lap. Watch first commercial tonnes, not the certificate date. Watch whether recoveries stay inside the band the feasibility work implied. Watch working capital as inventory builds. Watch whether the company keeps stacking small, faster sources while the flagship learns to breathe.
Also watch policy. Export licensing from the dominant supplier can loosen or tighten without a press conference that matches the market impact. Defense origin rules can be interpreted strictly or with waivers. Either shift moves the scarcity premium. Sangdong’s value is partly geological and partly a function of those rules staying tight.
Simple watchlist after approval:
  1. First saleable concentrate on a schedule
  2. Quality claims versus converter feedback
  3. Ramp versus the 210,000 MTU minimum path
  4. Expansion talk only after the plant is boringly reliable
A Personal Read On The Noise Versus The Metal
I’ll be honest. Critical-minerals coverage gets breathless fast. Every deposit becomes a “West versus the rest” morality play. Most of them are just rocks with a spreadsheet attached. Sangdong is more interesting than average because the jurisdiction is real, the offtake is long, and the policy calendar is not theoretical. That still does not make the equity a one-way ticket. Mining companies are factories with weather, labor, and metallurgy. Factories disappoint.
Still, if you care about industrial metals that actually show up in machines rather than in conference slogans, this approval is one of the cleaner data points of the year. Not because a stock popped before the open. Because a plant can now legally turn Korean ore into a product Western buyers can put on a truck.
The next chapter is dull on purpose. Safe shifts. Steady throughput. Bags that match the contract. If that dull chapter arrives, the louder geopolitical story writes itself. If it does not, all the certificates in the world will not move a single cutting insert.
The Longer Arc For Western Industrial Metals
Tungsten will not be the last metal to get this treatment. Antimony, gallium, germanium, rare earths: the list of quiet inputs has become a political list. Each one has a different geology and a different processing bottleneck. The common thread is origin scrutiny. Once governments start asking where the atoms were dug, mines in allied countries stop being optional color on a slide and start being capacity.
That is why Sangdong’s certificates travel beyond one ticker. They are a small proof that permitting, offtake, and allied geography can still combine into actual product. The proof remains incomplete until the plant is boring. Boring, in this business, is the highest compliment.
So yes, South Korea gave a tungsten plant its final green light. The West gets another address on a very short list. Prices are high. Rules are tightening. Most of Phase I is already sold. Now the unfashionable work begins, the kind that never trends and always decides whether the story was real.



