
Have you ever watched a market swing on a rumor that nobody can quite pin down, then realize the rumor was only half the story? That is the mood around Red Sea oil this week. Traders woke up to talk that Saudi loadings on the western coast might start again for Asian buyers, and the whole energy complex took a breath. Not a victory lap. Just a breath.
Why A Quiet Port On The Red Sea Suddenly Matters Again
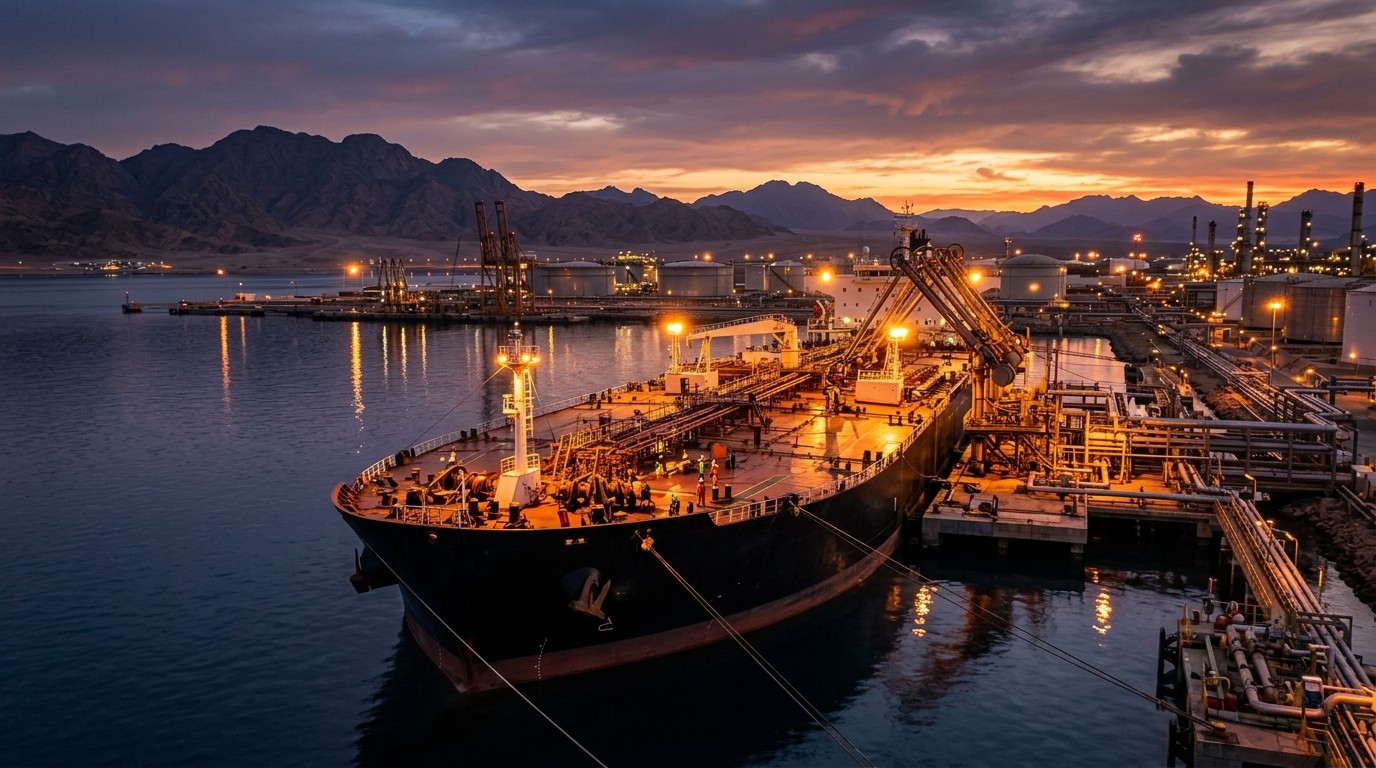
Yanbu is not the name that usually leads dinner conversation. Ras Tanura gets the headlines. Hormuz gets the fear. Yet the Red Sea terminal is the spare lung of the Saudi export system. When the East-West line is healthy, it lets barrels skip the most watched waterway on earth. When it is not, every extra cargo has to squeeze through a much narrower story.
Loadings there stopped after a drone strike on a pumping station earlier this month. The line had been moving a huge volume, roughly in the neighborhood of four million barrels a day. That is not a rounding error. That is a second highway. Asian refiners who expected pickups found empty slots. Some ships sat nearby. Others were still steaming in, hoping the schedule would unfreeze.
Now the message to at least a few Asian refiners is softer. Pickups at Yanbu could resume soon. No official countdown. No press-friendly ribbon cutting. Just a commercial nudge: get ready. In my experience, those quiet commercial nudges move markets faster than speeches.
The Bypass That Makes Hormuz Less Absolute
People talk about chokepoints as if they were on-off switches. Reality is messier. A working East-West system does not erase Hormuz risk. It shrinks the monopoly of that risk. Saudi barrels can still leave the Gulf. They can also leave west, then head toward Asia by a longer loop if buyers accept the extra days and the extra freight.
That flexibility is the point. When the pipeline is dark, flexibility dies. Cargoes pile back onto the Gulf route. Ship-to-ship ideas in the Gulf of Oman start to look less like a workaround and more like the main plan. Freight gets jumpy. Insurance desks get chatty. Refiners in East Asia start counting days of cover with a tighter jaw.
A bypass only works when it actually bypasses. A closed pump station turns a clever map into a postcard.
I have found that markets forgive a lot if they can see a second door. They punish the idea that there is only one door left, even when barrels are still moving. Psychology is not a footnote here. It is the premium.
What Asian Buyers Actually Need From A Restart
Asian refiners do not buy headlines. They buy arrival windows, assay stability, and a loading program that does not collapse two days before a hull is due. Several already missed dates. That is not drama. That is lost runs, swapped grades, and ugly freight on the spot market.
A restart at even half capacity would not fix every hole. It would still change the conversation. Half of a four-million-barrel highway is still a lot of crude looking for a home. It is also a signal that the physical system is being patched, not abandoned.
- Confirmed loading slots instead of open-ended delays
- Clear rules on which grades move west first
- Honest freight guidance if ships must wait or divert
- A sense that security around the line will hold for more than a news cycle
Without those pieces, “soon” is just a polite word. With them, Asian desks can stop treating Yanbu as a museum exhibit and start treating it as a berth again.
The Other Story Running In Parallel
At the same time, chatter about the Strait itself has been noisy. One version said a reopening offer was on the table in exchange for less naval pressure and a looser grip on Iranian ports. Another version, from a semi-official channel, called those reports invalid. If you feel whiplash, you are paying attention.
Brent dipped under one hundred dollars on the hopeful version. That tells you how tightly prices are lashed to a handful of sentences. It also tells you how little buffer the market thinks it has. When a denial can travel as fast as the original leak, you do not get a clean trend. You get a staircase with missing steps.
Perhaps the most interesting aspect is not which rumor wins the morning. It is that both stories exist because the physical map is still damaged. Diplomacy becomes a price input when pipes and pumps cannot carry the full load.
How The Saudis Have Been Keeping Barrels Moving Anyway
The Gulf route did not freeze. Loadings out of the eastern terminals picked up. More tankers have been pointed through Hormuz. Some cargoes have been offered for ship-to-ship transfer in the Gulf of Oman, which is a fancy way of saying: we will get the oil near you even if the original berth is a mess.
That is expensive. It is also imperfect. STS operations add time, weather risk, and a stack of operational paperwork nobody loves. Buyers accept it when the alternative is a dark distillation unit. They do not accept it forever.
Still, give credit where it is due. A producer that can reroute millions of barrels without a theatrical collapse of export numbers is not a producer on the ropes. It is a producer improvising. Markets respect improvisation until they start pricing the cost of improvisation into every quarter.
Why Inventories Still Look Thin After Months Of Trouble
Net supply losses from the wider Middle East story have narrowed from the terrifying early estimates. One widely circulated view now puts the net gap near 4.7 million barrels a day, down from a much larger shock at the start of the conflict. That is progress. It is not comfort.
Months of disruption eat cushions. Stocks that looked merely tight in a calm year look dangerous after a long grind. Refinery maintenance windows get rearranged. Strategic piles get discussed in public more often than governments prefer. Paper markets can look orderly while the physical market is one more incident away from another scramble.
Prices have a long way to go before supply and demand converge if the current pattern of disruption simply drags on.
– Market note circulating among energy desks
That line is blunt on purpose. A dip below one hundred does not settle the argument. It only shows that hope still has a bid. Hope is not a stockpile.
The Uncomfortable Math Behind A Fifty Percent Jump
One bank note floated an upside case in which Brent might need to climb another fifty percent if disruptions persist and buffers stay thin. That is not a base case. It is a warning label. The same shop sketched a much calmer path later in the decade: something like ninety-five in a later quarter of 2026, then a glide toward the eighties through 2027.
Those two pictures can live in the same document because they answer different questions. The glide path assumes the world slowly stitches itself back together. The spike path assumes another shock hits a system that already spent its spare tires.
| Scenario | What Has To Be True | Price Tone |
| Partial Yanbu restart | Half-capacity westbound flows return | Softer risk premium |
| Status quo grind | Gulf route carries the extra load | Sticky, jumpy crude |
| Fresh supply shock | Another facility or waterway hit | Sharp squeeze higher |
| Diplomatic thaw | Chokepoint fear fades for real | Fast giveback in prices |
I do not treat any of those rows as destiny. I treat them as a checklist. If you only trade the hopeful row, you will get run over by the third one. If you only trade disaster, you will miss the day the pumps actually restart.
Politics Is Now A Freight Factor
Energy markets hate admitting this, but voter calendars leak into tanker schedules. Approval numbers, midterm math, and prediction-market odds on a sweeping opposition win all change how long a leader can tolerate a messy war premium at the pump. That is not a partisan sermon. It is a constraint.
When public patience thins, the incentive to show “tangible progress” rises. Progress can mean a real deal. It can also mean a photogenic pause that lasts just long enough for prices to slip and headlines to soften. Traders have seen both. They should not confuse them.
A 65 percent style probability on a clean electoral sweep, if that is what the betting boards keep showing, does not set the price of Dubai crude by itself. It does raise the cost of looking inactive. Watch the gap between talking points and loading programs. The second one pays the bills.
What A Half-Capacity Restart Would Change On The Water
Think in ships, not slogans. Half capacity on that westbound system is still a crowd of very large crude carriers that no longer have to join the Hormuz queue. Some Asian-bound voyages get longer in miles and shorter in political risk. Some European buyers who lost dates might sneak back into the program if grades match.
- Waiting vessels near the Red Sea port get a chance to load instead of ballasting away.
- Gulf of Oman STS demand could ease if original terminals work again.
- Freight on the residual Hormuz route may stop looking like a panic tax.
- Refiners can rebuild a more normal slate instead of living on emergency swaps.
None of that happens in a single tide. Ports restart in layers. Security reviews eat days. Insurers want language. Captains want daylight and a clean notice of readiness. The first cargo off a repaired system is always slower than the spreadsheet promised.
Asian Demand Is Not A Single Buyer With One Mood
It is easy to say “Asian buyers” as if Seoul, Singapore, Mumbai, and the Chinese coast shared a group chat. They do not. Some systems are long on sour barrels and can wait. Some are short and already hunting West African or American substitutes at ugly differentials. A Yanbu reopening helps the second group first.
There is also the quality question. Not every molecule that used to move west is a perfect twin of what a given plant wants next month. A restart that only frees the wrong grade is a headline without a hydrotreater. Watch which crudes get named in the first lifting lists. That list is the real article.
In my view, the refiners who kept optionality on Atlantic Basin barrels will sleep better even if Yanbu stays patchy. The ones who bet the farm on a single Middle East program will keep paying for that concentration.
The Difference Between A Pause And A Repair
Markets are terrible at this distinction. A pause looks like peace on a candle chart. A repair looks boring: extra patrols, rebuilt pumps, redundant power, staff who are not exhausted. Only the second one lasts.
If loadings resume this week and then another incident knocks the station offline again, the risk premium will come back meaner. Traders hate being lured into a short by a two-day thaw. That memory sits in the book for months.
So the test is simple, almost rude. Does the second week of loadings look like the first? Do more than three refiners get the same story? Does the security perimeter stay dull? Dull is good. Dull is how pipelines are supposed to live.
Brent Under One Hundred Is Not The Same As Balance
A print below a round number feels like a verdict. It is usually just a weather report. Consumption has not staged a theatrical collapse. Spare capacity outside the region is not infinite. Product cracks can stay firm even while crude takes a hopeful dive.
If middle distillate stocks in key hubs stay lean, a cheaper barrel of crude does not automatically mean cheaper diesel on the street. The refining system has its own scars. Ignore that and you will misread the next “relief rally.”
Rough mental model:
  Physical barrels available
+ Working bypass capacity
+ Inventory days of cover
- Geopolitical headline risk
= How loud the price can shout
It is not pretty math. It is usable math. Right now the first two lines are improving at the margin. The third is still thin. The fourth is a coin flip dressed up as analysis.
What I Would Watch Over The Next Ten Days
Forget the temptation to live inside every denial and leak. Watch operations. Watch the water.
- Named lifting programs for Yanbu rather than vague “soon” language
- Tanker tracking that shows hulls actually berthing, not just hovering
- Whether Gulf of Oman STS chatter cools or stays bid
- Product cracks in Asia if crude availability really improves
- Any fresh incident near pumping stations or loading arms
If those five items line up kindly, the market can keep walking down the risk premium without pretending the last month never happened. If they do not, yesterday’s dip becomes a gift for the next squeeze.
A Personal Read, Without The Crystal Ball Costume
I have sat through enough energy cycles to distrust both panic and champagne. The encouraging part of this week is commercial, not theatrical. Refiners were told they might pick up crude on the Red Sea again. That is how real systems heal: a phone call, a slot, a ship that finally gets a notice of readiness.
The uncomfortable part is everything around that call. Denials about the Strait. Thin stocks. A political clock that does not care about pump station lead times. Analysts who can sketch eighty-dollar crude in 2027 and a fifty percent squeeze in the same notebook. Both can be honest. They just cannot both be true in the same quarter.
So here is the plain version. A Yanbu restart at half speed would be the first adult piece of news in a story that has been living on adrenaline. It would not end the energy crisis talk. It would make the talk less cartoonish. Asian buyers would get barrels. The Hormuz premium would lose a little of its monopoly. And the rest of us would go back to doing what this market always forces us to do: wait for the next loading list, not the next rumor.
If the first cargoes leave cleanly, remember how fast the mood can swing the other way. If they do not leave at all, remember that “soon” was never a contract. Either way, the Red Sea is no longer a side character. It is one of the few remaining ways this market can prove it still has a spare lung.