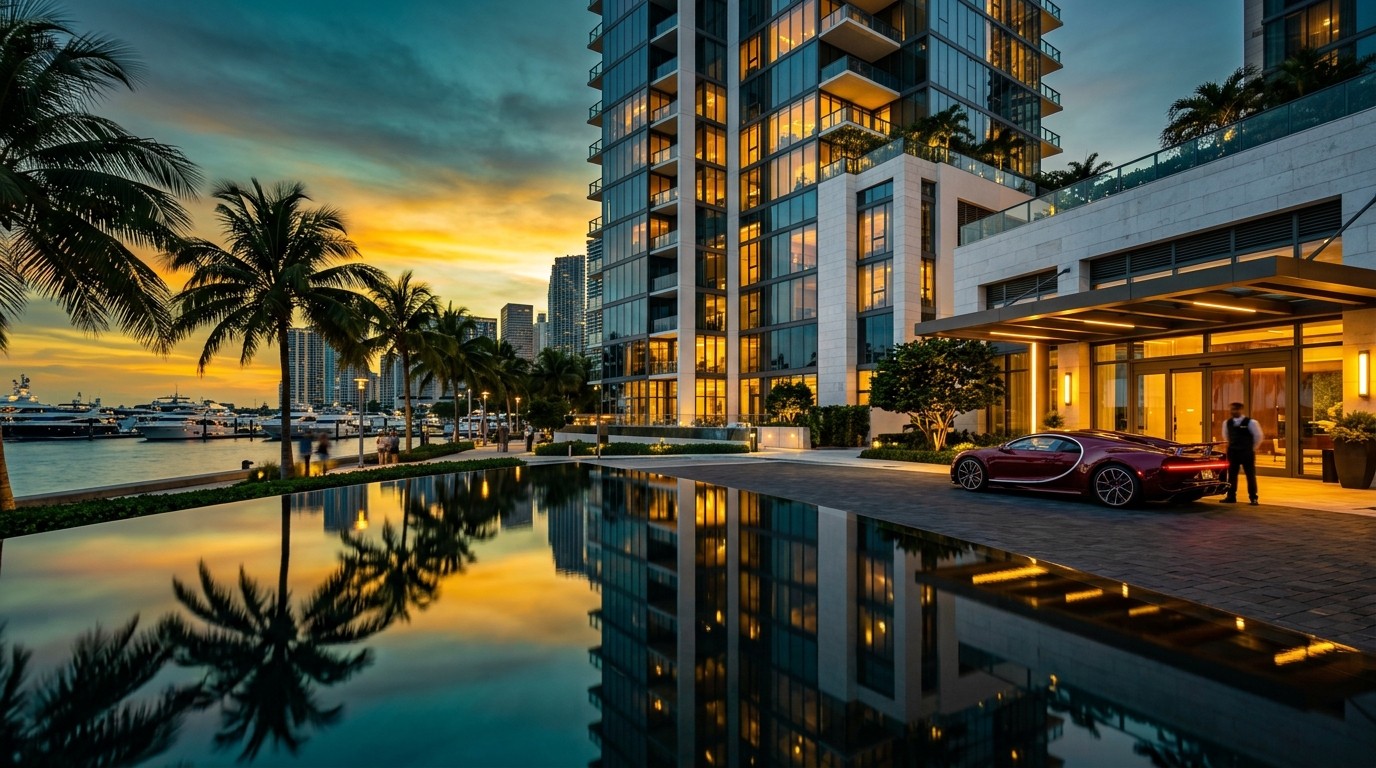

Walk the Brickell waterfront at dusk and you can almost hear the market arguing with itself. One side of the conversation is cool and careful: higher borrowing costs, thinner demand in ordinary neighborhoods, prices that no longer climb in a straight line. The other side is louder, flashier, and frankly harder to ignore. It is the sound of all-cash closings, penthouses spoken for before the marketing suite even looks finished, and luxury car names showing up on residential towers as if a badge on a hood now belongs on a lobby wall. That split is the real story of Miami right now.
Why The Top End Refuses To Cool Off
I have watched enough housing cycles to know that “boom” is a sloppy word. It hides who is buying, how they are paying, and which slice of the city is actually moving. In Miami-Dade, the slice that still moves with force is the ultra-luxury band. Homes at $10 million or more are not a side show. They are setting the pace.
Local realtor association figures for the first eight months of 2026 already show 194 sales in that rarefied bracket. That is 14.1% above the 170 deals recorded across all of last year. If the current rhythm holds, the county could finish near 291 transactions. The prior annual high of 230, set in 2021 during the pandemic scramble, would not just be matched. It would be left behind.
Those numbers land differently when you remember what the rest of the market feels like. Inflation-adjusted prices across the broader city slipped about 1.6% year over year. Affordability is strained. Ordinary buyers still notice every tick in financing costs. So how does the top stay this busy? Cash, mostly. And a stubborn flow of people who are not shopping with a mortgage calculator in one hand.
Cash Has Become The Quiet Superpower
Miami now leads the country in cash activity at the high end. About 82% of condo sales valued at $1 million or more in 2025 were completed without a loan. That is not a rounding error. That is a market structure.
When most of your buyers do not need a bank, rate hikes lose some of their bite. Closings do not stall while underwriters debate debt-to-income ratios. Sellers get certainty. Developers get deposits that feel real. I find that last part underdiscussed. Certainty is a product in luxury real estate, same as marble and bay views.
A high share of cash transactions has made the luxury segment less sensitive to elevated financing costs and helped pull bubble risk down from the top of last year’s ranking.
A major global bank’s housing index once placed Miami at the highest bubble-risk reading in its survey. This year the same city sits in the “elevated” column rather than the danger seat. That is not a victory lap. Elevated still means watch your step. It does mean the most extreme warning lights dimmed, in part because so many purchases never touch a lender.
There is a second support beam: relocation. Buyers leaving higher-cost, higher-tax states keep treating South Florida as a place to park both lifestyle and capital. A broad, sudden price collapse across the luxury band looks unlikely in the near term if that migration does not reverse. I would not call it invincible. I would call it stubborn.
The Split Screen Between Luxury And Everyone Else
Here is where the conversation gets less glamorous. The same city that is minting records above $10 million is asking middle-tier buyers to stretch. Elevated borrowing costs and thin affordability have weighed on demand outside the trophy segment. Prices, once adjusted for inflation, are not marching higher for the typical household.
That split screen matters if you are trying to read Miami as one market. It is not one market. It is a stack of markets that share humidity and a skyline. The penthouse and the three-bedroom inland condo can live in different economic weather on the same afternoon.
- Ultra-luxury sales are running ahead of last year’s full-year total with months still left on the calendar.
- Cash dominates high-value condo deals and cushions the top tier from rate shock.
- Broader, inflation-adjusted prices slipped, reflecting weaker demand below the luxury line.
- Relocation from expensive U.S. metros continues to feed trophy inventory more than starter inventory.
Perhaps the most interesting aspect is psychological. Media love a single headline. “Miami is booming” or “Miami is cracking.” Both can be true in the same week if you specify the price band. Readers who skip that detail walk away with a cartoon.
When A Car Badge Becomes A Building
Strength at the top is no longer visible only in closed sales. It is visible in branding. Last week, Bugatti outlined plans for its first branded residential project in the United States, planned for Miami’s Brickell waterfront. The French marque joins a roster that already includes Porsche, Aston Martin, Bentley, and Mercedes-Benz residences in the same metro.
I will admit a private shrug the first time I heard “car brand condos.” It sounded like a marketing stunt dressed as architecture. Then you look at who actually writes the checks. Buyers in this lane already collect objects that signal rarity. A residence that extends the same identity is not a gimmick to them. It is inventory that matches the rest of the closet.
Jay Roberts, chief executive of the group developing the planned Bugatti Residences Miami, called the city a global epicenter for wealth migration. That phrase gets used a lot. The branded-tower pipeline is one of the few ways the phrase shows up in steel and glass rather than a press release.
Does every badge project deserve a waiting list? Of course not. Some will age like a limited-edition color that looked brilliant in the showroom and odd five years later. The point is not that every tower will be a masterpiece. The point is that luxury capital still wants a Miami address with a story attached.
What Wealth Migration Actually Looks Like On The Ground
People talk about migration as if it were a single wave. It is more like a series of small decisions that pile up. A founder sells a company in the Northeast. A family office shifts a larger share of its year to the water. A household that already owned a seasonal place decides the seasonal place is now the main place. Multiply that by enough balance sheets and you get absorption at the top.
Tax climate is part of the pitch. Climate, in the weather sense, is another. So is a social calendar that now feels national rather than regional. Miami stopped being only a winter escape for a certain class of buyer. It became a year-round stage. That change is easy to mock until you watch listing traffic in January and July look more alike than they used to.
In my experience, the buyers who move markets are rarely the loudest on social media. They close quietly, often in cash, and they care about three boring things: privacy, liquidity of the asset if they ever want out, and whether the building still feels special after the launch party ends. Branded projects try to answer the third item. Cash answers the first two by removing financing drama.
Bubble Risk, Elevated Risk, And The Words In Between
Index labels are catnip for headlines. “Highest bubble risk” last year. “Elevated” this year. Useful, if you treat them as a temperature check rather than a prophecy. Miami did not suddenly become cheap. It became slightly less stretched in the eyes of one widely watched scorecard, thanks in part to that cash share and to demand that is not purely local.
A broad-based correction still looks unlikely in the near term according to that same analysis. I would add a caveat of my own. Unlikely is not the same as impossible. Insurance costs, climate exposure, and construction quality can reprice buildings even when buyer wealth remains high. Luxury is not immune to a cracked facade or a painful premium notice. It is simply slower to show fear.
| Market Layer | Current Tone | Main Support |
| Ultra-luxury, $10M-plus | Hot, record-tracking | Cash and inbound wealth |
| High-end condos, $1M-plus | Resilient | All-cash closings |
| Broader existing homes | Softer in real terms | Limited by rates and paychecks |
Read that table twice. The city can print trophy records and still leave a first-time buyer staring at monthly payments that do not work. Both facts can sit in the same paragraph without canceling each other.
Why Developers Keep Betting On Names And Water
Brickell waterfront is not a random pin on a map. It is a stage with an audience that already understands scarcity. Water views, short walks to dining, and a skyline that photographs well are the raw materials. A global brand is the seasoning. Together they create a product that can be sold to someone who might never have hunted Miami inventory before that logo appeared.
That is the underappreciated function of branded residences. They recruit. They turn a local tower into an object that a collector in another country already knows how to desire. Porsche does not need to explain itself. Neither does Bugatti. The building borrows that familiarity and tries to convert it into deposits.
Will the next decade be littered with too many badges? Possibly. Markets overshoot themes. We have seen hotel brands, fashion houses, and sports names take a turn at the same trick. Some projects become landmarks. Others become footnotes. Buyers who treat the badge as the entire due diligence package are the ones who usually learn the expensive lesson.
How Cash Changes Negotiation, Timing, And Risk
Talk to anyone who has sat at a luxury closing table in this city and you hear the same small details. Cash offers move faster. Inspection fights get shorter when the buyer is not waiting on a lender’s appraiser. Contingencies shrink. That speed is a feature for sellers and a pressure tactic for anyone still financing.
It also changes who gets left out. A qualified buyer with a large down payment and a pristine file can still lose a bidding situation to a wired transfer. That is not a morality play. It is arithmetic. If you are shopping below the trophy line, you feel that arithmetic as fewer options and more competition from investors who do not need sleep from a loan officer.
- Trophy inventory clears because wealthy buyers can ignore rate headlines.
- Branded towers harvest identity and turn it into pre-sales.
- Non-luxury demand cools when monthly costs outrun wages.
- Indexes mark lower bubble heat without calling the city cheap.
If you only remember one sequence, remember that one. It is the plot.
The Affordability Hangover Nobody Puts On A Billboard
Miami’s marketing machine will always lead with sunsets and marble. Fair enough. Sunsets sell. The hangover is insurance, maintenance, and the gap between median incomes and median payments. Those items do not photograph well. They still decide whether the middle of the market can breathe.
A 1.6% real price decline is not a crash. It is a reminder that gravity still works when leverage is involved. Families who need a mortgage live in a different movie from families who do not. Policy debates about housing supply often skip that split and then wonder why the argument feels stuck.
I have found that readers get calmer when you separate trophy statistics from household statistics. Mix them and you get rage or denial. Keep them in two columns and you get something closer to a usable map.
What Buyers And Sellers Should Actually Watch Next
Forget the urge to declare a new golden age. Watch a handful of unglamorous gauges. The share of cash in million-dollar-plus condos. The pace of $10 million-plus closings after the seasonal rush. Absorption in branded buildings after the first wave of collectors has taken their pick. Insurance quotes on waterfront stock. Time on market for homes that are merely nice rather than rare.
If cash share stays extreme, the top can keep humming even if national rate cuts disappoint someone. If branded inventory piles up faster than unique demand, discounts will show up first as silent extras rather than public price cuts. Parking spaces, storage, design credits. Luxury rarely shouts “sale.” It whispers upgrades.
Sellers in the middle should not copy trophy pricing logic. That is how listings go stale. Buyers in the middle should not assume the trophy boom will lift every boat. Sometimes it just lifts yachts.
A city can be the epicenter of wealth migration and still be a hard place to buy a normal home. Holding both ideas at once is the whole job.
The Cultural Flex Hiding Inside The Floor Plans
There is a cultural layer here that pure price charts miss. A Bugatti tower is not only housing. It is a statement that Miami wants to be counted among cities where identity is an amenity. Think of it as hospitality logic applied to ownership. You are not only buying square footage. You are buying membership in a story.
That can feel silly until you remember how many purchases at this level are already about story. Art. Watches. Cars. The residence is the largest object in the collection. Branding makes the object legible to peers. Whether that is tasteful is a separate debate. Whether it sells in this climate is less mysterious.
I still prefer buildings that will look inevitable in twenty years without needing the badge to explain them. Taste is not a closing condition, though. Money has its own aesthetic, and right now that aesthetic likes a recognizable name facing the bay.
A Longer View Than The Next Closing
Cycles end. This one will too, on some future calendar page we cannot mark yet. The useful question is what remains when the music changes. Cash-heavy demand can slow without vanishing. Migration can cool without reversing. Branded towers can keep their clubs even if resale premiums shrink.
What will not vanish quickly is the dual market. Miami has spent years becoming a magnet for mobile wealth while remaining difficult for households that live on local wages. That tension is older than this year’s sales tally. The tally just makes it louder.
If you came here hoping for a single verdict, I will disappoint you on purpose. The ultra-luxury book is thick and still adding chapters. The everyday book is slower, heavier, and more sensitive to the cost of money. Honest analysis keeps both books on the desk.
And if you happen to stand on that Brickell walkway after sunset, look up. The lights in those high floors are not a metaphor for the whole city. They are a report on one layer of it. The layer with cash. The layer with badges on the door. The layer that, for now, is still writing checks.
Practical Takeaways Without The Hype Machine
For a household already in the trophy hunt, speed and documentation still beat theatrics. Proof of funds talks. So does a willingness to live with the building’s rules after the champagne is gone. For everyone else, treat headline records as entertainment unless your budget lives in that neighborhood. Your market is the one that matches your payment, not the one that matches a press event.
Investors should separate scarcity from branding. Water, quality construction, and a floor plan people still want in a downturn will outlast a launch video. A logo can help the first sale. It does not automatically help the fifth resale.
Policymakers and neighbors will keep arguing about who this boom is for. That argument is not a distraction. It is the other half of the data. A record year at $10 million and above can coexist with a city that feels closed to the people who keep it running. Pretending those are separate planets is how analysis turns into advertising.
So yes, the Miami luxury housing market is booming in the band that pays cash and collects names. Bubble heat, as scored by that global index, is less extreme than it was. Car brands are now part of the residential skyline. None of that erases the softer print in inflation-adjusted prices for the rest of town. Hold the contrast. That is the adult version of the story, and it is the one worth reading twice.