
I used to think the clever move was simple: keep adding funds until the spreadsheet looked impressively busy. More names on the statement felt like more safety. Then I sat down one weekend, lined up the top holdings of every fund I owned, and watched the same giant companies appear again and again. That was the moment the question stopped being theoretical. How many funds should you actually hold before the extra ones stop helping and start getting in the way?
The Real Question Behind Fund Count
Diversification gets called the only free lunch in investing for a reason. A single fund already bundles dozens or hundreds of holdings, so it is tempting to assume that stacking funds multiplies that benefit. It does, up to a point. After that point you are mostly buying the same exposure twice, paying more attention than the extra slice is worth, and making rebalancing feel like a part-time job.
Wealth professionals often put it in plain language. Build a mix that can survive different markets. That usually means global reach, a blend of shares and bonds, and some cash for breathing room. You can get there with one carefully chosen multi-asset product. You can also get there with a short list of specialist funds. Both routes work. The mistake is treating the headcount as a badge of sophistication.
The key is to build a diversified portfolio because this helps you weather different market conditions. Diversification means spreading your money so it is invested globally, giving you exposure to different countries and sectors, with a mix of shares and bonds.
– Savings and investments director at a private bank
I have found that people rarely ask the better follow-up: what job does each fund do? If you cannot answer that in one sentence, the holding is probably decoration.
Why One Fund Can Be Enough
Ready-made multi-asset funds exist for a reason. They hold shares, bonds, and cash. They invest across regions. They differ mainly by how much risk they take. If you are starting out, or you simply do not want to babysit ten factsheets, picking one product that matches your comfort with volatility is a perfectly grown-up choice.
There is very little glory in owning a fund you do not understand. Complexity is not a strategy. A single global mix can cover the big building blocks: developed markets, some emerging markets, government and corporate bonds, and a cash sleeve for dry powder. You still need to check costs, tax wrappers, and whether the risk label matches how you sleep at night. You do not need a mosaic of tickers to look like an investor.
In my experience, beginners who start with one sensible core product make fewer impulsive tweaks. That matters more than most people admit. A tidy portfolio you leave alone often beats a crowded one you keep poking.
When Adding Funds Actually Helps
Confidence changes the picture. Once you know what a global equity tracker does, you might want a separate bond fund so you can tilt the mix yourself. You might want a dedicated emerging markets sleeve because your core product underweights that region. You might want a smaller satellite for a theme you actually understand, not one you saw in a headline.
Building the mix yourself usually means buying funds that each cover a different slice of the market. Think regions, not vibes. United Kingdom, United States, Europe, Asia, emerging markets. Then think asset class: shares versus bonds. Then, if you must, style or size: value versus growth, large companies versus smaller ones. That is how you add funds without cloning the same portfolio five times.
If you prefer to build your own diversified portfolio, around 10 well selected funds can be more than sufficient to provide diversification across different asset classes, regions, market capitalisation and styles.
– Head of funds research at an investing platform
Ten is not a magic number. It is a ceiling most households never need to smash. I would rather own eight funds with clear jobs than fifteen that blur together.
The Quiet Cost Of Too Many Holdings
Extra funds feel like extra safety. Often they are extra noise. Overlap is the usual culprit. Two global equity funds can share a startling number of the same mega-cap names. Add a technology fund and a growth fund on top and you have not broadened risk so much as concentrated it in a fashionable corner of the market.
There is another problem that does not show up on the first factsheet. Dilution. If you own twenty funds, each one is a sliver. A brilliant year in a tiny holding barely moves the needle. A disaster in a tiny holding barely hurts, which sounds comforting until you realise you also gave up the chance of meaningful contribution. Holdings that sit under about two percent of the whole often add paperwork without changing outcomes.
Monitoring suffers too. Rebalancing a compact portfolio is a short afternoon. Rebalancing a cluttered one becomes a project you postpone. Delayed maintenance is how drift happens. Drift is how a cautious plan quietly becomes an aggressive one without anyone deciding it should.
If you hold more than 20 funds, it is probably worth reviewing whether each one has a clear role and is genuinely adding something different to the portfolio. Too many funds can make a portfolio unnecessarily complicated and harder to monitor and rebalance.
– Funds research lead
I have sat with statements that looked diversified on the cover and concentrated underneath. The number of lines was not the story. The repeated stocks were.
Does A Bigger Pot Need More Funds?
Not really. Allocation is a percentage game. A large account and a small account can hold the same structure. The larger pile does not automatically require more products. It might allow smaller specialist sleeves without those sleeves becoming rounding errors, but that is optional, not mandatory.
Someone with a modest pot can get broad coverage from one multi-asset fund. Someone who wants tighter control can split the same idea across several building blocks. Portfolio size matters less than the map: how much in shares, how much in bonds, how much outside your home market, how much in cash. Get the map right and the number of vehicles becomes a secondary choice.
The size of the portfolio matters less than its overall asset allocation and the role of each fund. A large portfolio does not automatically need more funds. If a fund represents less than around 2% of your portfolio, it is worth asking whether it is large enough to make a meaningful difference to overall returns or risk.
– Investment platform research note
There can be good reasons for a tiny specialist allocation. A narrow sector you understand deeply. A hedge against a specific risk. Fine. Just be honest if the holding exists because it was interesting on a Tuesday evening and not because it changes the portfolio.
A Practical Range Most Investors Can Live With
If you want a working range rather than a slogan, here is the one I keep coming back to. One fund can be enough if it is a genuine multi-asset mix aligned with your risk. Three to six funds is a sweet spot for people who want to set weights themselves. Around ten is ample for almost any household that is not running a specialist strategy. Beyond twenty, assume you have a review problem until proven otherwise.
| Investor stage | Typical fund count | What the count is doing |
| Just starting | 1 multi-asset fund | Simple global mix, less decision fatigue |
| Building confidence | 3 to 6 funds | Separate regions or shares and bonds |
| Hands-on amateur | About 8 to 10 funds | Asset class, region, style, small satellites |
| Crowded portfolio | 20 or more | Likely overlap, harder reviews, thin slivers |
Treat that table as a compass, not a law. Life circumstances, tax wrappers, and employer plans can add extra lines you did not choose for fun. The test stays the same. Can you explain each line? Does it change risk or return in a way you can feel at portfolio level?
How To Spot Overlap Before It Bites
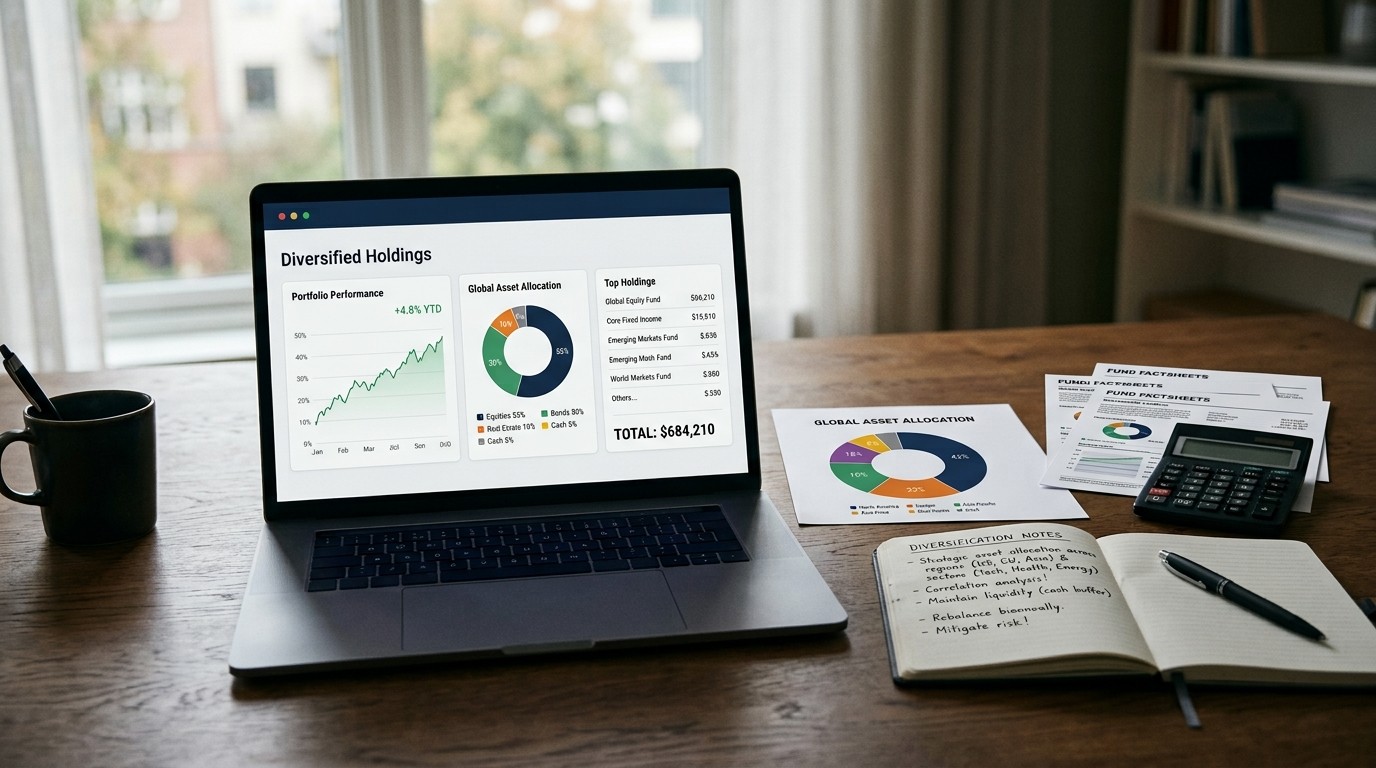
Look at top ten holdings across funds. If the same names keep showing up, you do not have five equity ideas. You have one idea wearing five costumes. Check region weights next. Two funds labelled differently can both be dominated by the United States. Check sector weights after that. A global fund plus a technology fund plus a growth fund can quietly stack the same trend.
Correlation is the unglamorous word for this. When markets fall, holdings that looked different on paper can slump together. Diversification that only works in calm weather is not diversification. It is coincidence.
- Compare top holdings, not just fund names.
- Check country weights, especially the United States share.
- Watch sector piles that repeat across supposedly different products.
- Ask whether a new fund changes the mix or merely restates it.
- Cut or merge when two products do the same job.
Perhaps the most interesting aspect is how often people buy a second fund because the first one had a dull year. That is not diversification. That is impatience with a label.
Beginners, Themes, And The Urge To Tinker
If you feel less confident, keep the first version simple. Ready-made options exist so you do not have to invent a global allocation from scratch. Adding a fund you cannot explain is not ambitious. It is clutter with a story attached.
Later, themes can earn a seat. Clean energy, healthcare innovation, smaller companies, quality income. The test is still boring and useful. Is the theme already sitting inside funds you own? Is the sleeve large enough to matter and small enough not to sink the plan if it goes cold for years? Can you hold it through a stretch where the narrative looks silly?
I have watched people collect themes like souvenirs. The portfolio becomes a mood board. Mood boards do not rebalance well.
Risk Appetite Still Beats Headcount
The number of funds will not save you if the mix is too aggressive for your nerves. Ten cautious funds can still be calmer than two equity-heavy ones. Risk lives in asset allocation, time horizon, and the gap between what you say you can tolerate and what you do when markets drop 20 percent in a quarter.
Write the mix first. Shares versus bonds. Home market versus the rest of the world. Cash buffer. Only then choose vehicles. That order keeps you from using fund shopping as a substitute for a plan.
A simple order of work:
  1. Decide risk and time horizon
  2. Set asset mix in percentages
  3. Choose the fewest funds that deliver that mix
  4. Review roles, overlap, and costs
  5. Rebalance on a schedule, not a headline
That sequence sounds almost too plain. It is also how people avoid owning seventeen products and still feeling exposed.
Costs, Tax Wrappers, And Friction You Can Feel
Every extra fund can mean extra ongoing charges, extra dealing fees if you rebalance often, and extra mental load. None of that appears in a glossy performance chart. Cheap broad funds remain hard to beat as core holdings. Paying active fees twice for the same large companies is a slow leak.
Tax wrappers change the housekeeping, not the logic. A pension, an individual savings account, and a general account can force you to duplicate a holding for administrative reasons. That is different from collecting lookalikes because a new launch sounded exciting. Keep the economic exposure consistent even if the legal wrappers multiply the line items.
Friction is underrated. If reviewing the portfolio feels heavy, you will delay it. Delayed reviews are how accidental bets form.
A Review Ritual That Keeps The List Honest
Once or twice a year, print or export the holdings. Next to each fund write one job in ordinary language. Global shares. UK shares. Global bonds. Emerging markets. Small companies. If two rows share a job, one of them is on notice. If a row has no job, it is a candidate for sale, not for a sentimental keep.
- List every fund and its percentage of the whole.
- Write the role in one short sentence.
- Flag anything under two percent unless it is a deliberate satellite.
- Compare top holdings for repeats.
- Decide whether to merge, cut, or leave well alone.
You do not need a dramatic overhaul every time. Sometimes the honest outcome is that the list is already fine. That is a win. Leaving a good mix untouched is a skill.
What Good Enough Looks Like In Practice
Picture two households. One owns a single multi-asset fund inside a tax wrapper, contributes monthly, and barely touches it. The other owns nine funds: a global equity core, a UK sleeve, an emerging markets sleeve, two bond funds with different jobs, a small-company fund, and a modest theme that the owner can explain at dinner without sliding into jargon. Both can be well built. The twenty-four fund collection with three overlapping global trackers and a graveyard of old themes is the one that usually needs a clear-out.
Good enough is a mix you can describe in a minute, rebalance without dread, and hold when the news is ugly. It is not a museum of products.
I’ve found that the investors who sleep best are rarely the ones with the longest statements. They are the ones who know why each line is there and what they will do if it has a rotten decade.
A Straight Answer You Can Use This Week
Hold as many funds as you need to deliver the mix, and not one more for theatre. One can be enough. Ten is plenty for most people who want control. Twenty is a prompt to edit. Portfolio size does not rewrite that logic. Overlap, tiny slivers, and fuzzy roles do.
If you remember only one thing, make it this. Diversification is about different sources of risk and return, not a higher line count. Name the job. Size the holding so it matters. Cut the duplicates. Then go live your life instead of babysitting a catalogue.
That is the unglamorous version. It is also the one that tends to last.