
Have you ever watched a fuel price jump and wondered who actually decides what happens next? I have, more than once, usually while standing at a pump that suddenly felt like a tax booth. This week the argument is not abstract. A possible diesel export ban has business groups, farm-state lawmakers, refiners, and White House officials talking past one another. The pitch from some corners is simple: keep more diesel at home and prices should fall. The reply from industry is just as blunt. Lock the barrels inside the country and you may get a short dip, then less production, tighter supply, and a nastier bill for families, farmers, and truckers.
Why A Diesel Export Ban Has Suddenly Become A Political Flashpoint
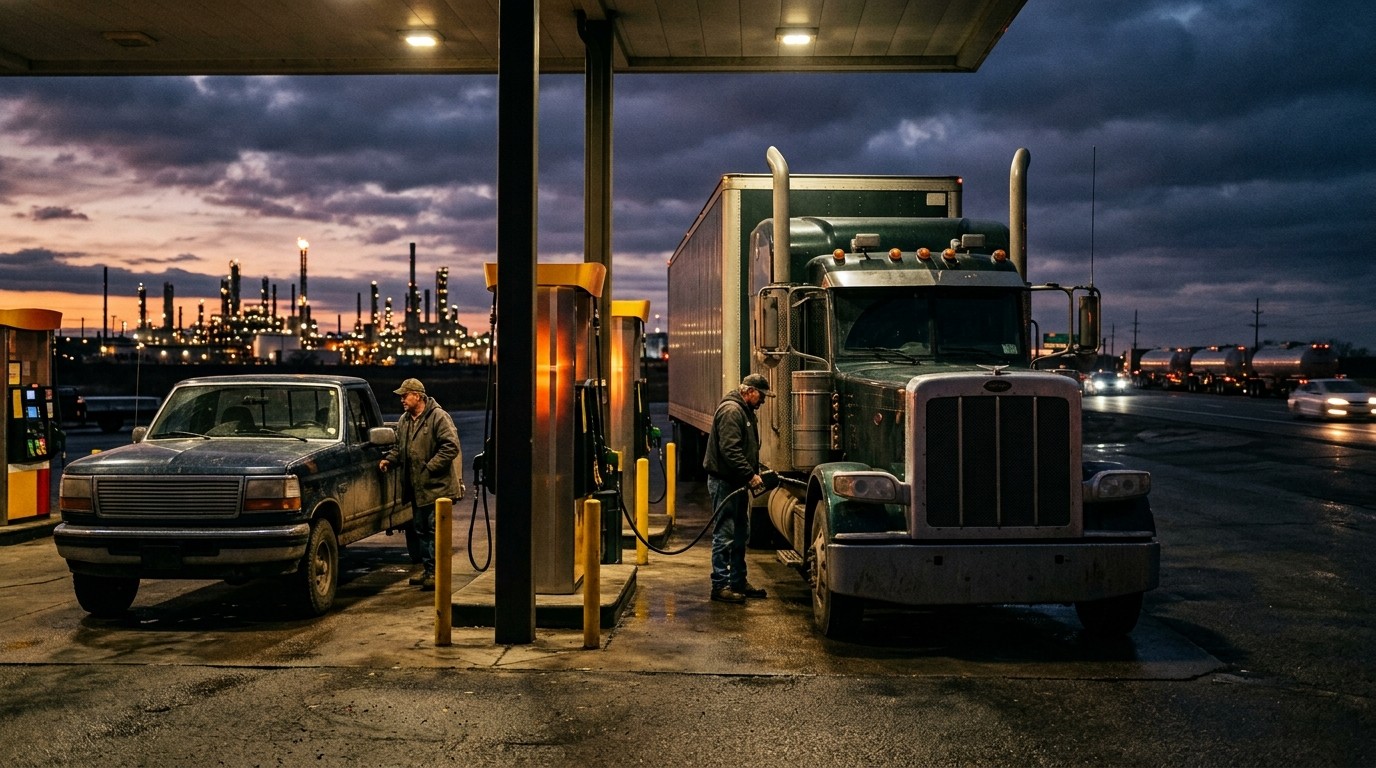
Diesel is not a side character in the American economy. It moves grain, steel, groceries, and almost every pallet that leaves a warehouse. When the national average sits near $6.51 a gallon, about $2.82 higher than the same stretch last year, people notice. They notice in Iowa first. They notice in every county where harvest season and trucking margins collide.
That is why the politics arrived before the policy paper. Lawmakers in farm states want action before midterm season hardens. The White House has been asked, loudly, to stop sending diesel abroad. The president even said he has argued internally for holding product back. Those remarks surprised a lot of people who live inside refining economics. Surprise is rarely a good planning tool in energy markets.
I’ve found that energy fights rarely stay inside one fuel. Constrain diesel and you start tugging on gasoline, jet fuel, and the way a refinery balances its slate. You also start tugging on global prices, because the United States is not a quiet producer. It is a major exporter. Remove that stream and the world looks for barrels somewhere else, often at a worse price and with worse timing.
What The Joint Letter Actually Warned
A cluster of large business organizations sent a joint letter this week. The Chamber of Commerce, the Business Roundtable, the National Association of Manufacturers, the American Petroleum Institute, and dozens of other groups told the administration that a ban or tight limit would be counterproductive. Their core claim was not subtle.
You have been asked by some to ban or limit the export of diesel to help lower prices, when in fact the opposite would occur.
They argued an export freeze would lead to less fuel production, tighter supplies, and rising costs for American families, farmers, and truckers. In my experience, that sentence is the whole fight in twelve words. One side hears “keep it here.” The other side hears “break the incentive to make it.”
Refineries do not run like neighborhood bakeries. They optimize crude slates, product yields, and export windows months in advance. If diesel cannot leave the country, some plants will make less of it. Some will cut runs. Some will lean harder into other products that still have a market. That is not ideology. That is how a complex industrial system protects cash flow when a valve gets welded shut.
The Political Clock Versus The Refinery Clock
Farm-state Republicans are not inventing the pain. Diesel is a farm input the way seed and fertilizer are farm inputs. When the pump climbs, the combine still has to run. Truckers face the same math with less poetry. A few cents on a gallon becomes a line item that eats a thin margin. Midterms make that line item louder.
So the political clock says: do something visible. Ban exports. Show voters a fist on the table. The refinery clock says something colder. Capacity is not a speech. Utilization rates, turnaround schedules, and product demand across gasoline and jet fuel decide whether more diesel even exists to keep at home.
Perhaps the most interesting aspect is how fast markets reacted to rumor. A report that the administration might prepare a 90-day freeze knocked diesel futures and refiner shares. Then an energy official said a full blanket ban was not on the table. That whiplash matters. Traders price fear faster than farmers can change a planting plan.
Feasible, Partial, Or Just Talk?
Treasury officials have described an internal look at feasibility. Could a full ban work given overall refining capacity? Would a partial limit do less damage? Those are fair questions. They are also the kind of questions that sound tidy in a briefing and messy in a tank farm.
An energy secretary with an industry background has already flagged a hard trade-off. Squeeze diesel exports and you can lift gasoline prices. That is not a talking point I enjoy repeating, but it is the sort of cross-product effect people forget when they stare at one number on a gas station sign.
Energy specialists describe a familiar pattern. A ban can crush regional diesel prices for a short stretch. Then refiners cut output. Then prices rebound, sometimes harder than the first spike. If you have ever seen a grocery sale empty a shelf and then double the restock price, you already understand the shape of this story.
The Global Squeeze That Made This Argument Possible
Diesel did not get expensive in a vacuum. Attacks on Russian refineries pushed Moscow to halt its own diesel exports. Russia had been the world’s second-largest diesel exporter. That hole in the map did not stay empty. It pulled on every remaining barrel, including American barrels.
At the same time, strikes and threats around Middle Eastern refining and tanker routes have kept shipping nervous. When the Strait of Hormuz feels risky, insurance rises, voyages slow, and product arrives late. Late product is expensive product. A U.S. export ban would remove the largest remaining flexible source from that stressed market. I do not say that as a cheer for exports. I say it because pretending the rest of the world will shrug is wishful.
There is a blunt phrase for this: you cannot isolate a global commodity with a domestic slogan. Diesel molecules do not care about midterms. Tankers do not wait for talking points. If the United States steps back, someone else prices the shortage.
Who Pays First If Exports Stop
The letter named three groups on purpose: families, farmers, and truckers. That is not random branding. Those three sit at the end of the cost chain. They do not hedge like a trading desk. They buy what they need when they need it.
- Farmers feel diesel in planting, harvest, and grain haul.
- Truckers feel it on every loaded mile.
- Households feel it later, in freight embedded in food and goods.
A brief regional price drop would look like a win on television. The second chapter is less camera-friendly. If refiners reduce diesel output because the export valve is closed, domestic users eventually compete for a smaller pile. That is how a policy designed as relief becomes a ration by price.
I’ll admit something here. The instinct to “keep our fuel at home” is emotionally clean. It sounds patriotic. It sounds practical. Markets are neither. They are accounting systems with pipelines attached. Ignore the accounting and the pipeline still has to balance.
Refining Reality, Without The Jargon Fog
Think of a refinery as a kitchen that must sell every course. Crude goes in. Gasoline, diesel, jet fuel, and leftover streams come out in proportions the equipment can handle. You can nudge those proportions. You cannot pretend the kitchen can plate only the dish voters want this month.
Export demand is part of the reason some plants keep running hard. Take that demand away and the plant manager has a choice. Cut runs. Shift yield. Park product in storage until tanks groan. Storage is not infinite. Neither is patience from lenders who watch crack spreads for a living.
That is why business groups keep repeating production, not just allocation. A ban allocates existing barrels. It does not magically create new ones. If anything, it can shrink the incentive to create them.
| Policy Move | Near-Term Price Effect | Medium-Term Risk |
| Full export ban | Possible regional diesel dip | Lower runs, rebound, gasoline pressure |
| Partial limit | Uneven, market-by-market | Compliance fights and weaker investment |
| No ban, other tools | Less theater, slower politics | Prices still tied to global shocks |
Tables flatten a messy world, I know. Still, the pattern is useful. The first week can look like victory. The third month can look like a supply problem you invented.
Farm Country Math Is Not Optional
It is not just diesel. Iowa farmers and their counterparts elsewhere are staring at a stack of higher costs. Fuel is the loudest because it is paid in public, one fill-up at a time. Fertilizer, parts, labor, and interest rates do their damage more quietly. Stack them and a harvest that looks fine from a highway can still lose money on a spreadsheet.
That is why a fuel-only fix is so tempting. It is visible. It is national. It can be announced in a sentence. The trouble is that diesel is the one cost most tightly bound to global refining and shipping. You can lecture a local co-op. You cannot lecture a tanker queue in a war-shadowed sea lane.
In my view, the honest political answer would sound worse on a rally stage. Help with timing of purchases. Look at seasonal blending rules. Watch Strategic inventories with care. Avoid a blunt export lock that teaches refiners to shrink. That sentence will not fit on a bumper sticker. It might still save more money by November than a 90-day freeze that scares investment.
What Officials Are Signaling, And What They Are Not
Public comments have already narrowed the theater. A complete, zero-export freeze is being described as something nobody wants. The live conversation is about the most efficient way to get more diesel into U.S. markets without choking gasoline and jet fuel flows. That is a better sentence. It is also harder to execute.
“Most efficient” can mean swapping barrels between coasts. It can mean encouraging higher utilization. It can mean temporary licensing quirks. It can mean talking loudly enough that traders pre-position supply. Words move barrels before rules do. That is not cynicism. That is how paper markets work.
Still, once a president says he has called for holding diesel back, the idea does not vanish. It sits on the table. Industry letters are an attempt to shove it off the table before a draft order grows a title.
The Short Squeeze Fantasy
Every few years someone rediscovers export controls as a consumer tool. Ban the outbound cargo. Watch the domestic price wilt. Celebrate. The fantasy skips the part where producers stop making the surplus that made the cargo possible.
Diesel demand is not a straight line either. Harvest season, winter heating in some regions, freight cycles, and hurricane logistics all yank the same product in different months. An export rule written for one news cycle can land in the wrong season. Timing errors in energy policy are expensive hobbies.
Ask a simple question. If exports are the problem, why did prices rise while the United States was still exporting? Because the global balance changed. Russian barrels left the board. Shipping risk rose. Crude quality and refining outages did their usual mischief. An American lockbox does not reverse those facts. It just changes who holds the remaining inventory.
Gasoline And Jet Fuel Are Sitting In The Same Room
People talk about diesel as if it lives in a private apartment. It does not. A refinery is a shared house. Push the house to hoard diesel and the roommates feel it. Gasoline yields can shift. Jet fuel availability can tighten on certain coasts. Airlines do not vote in Iowa the same way grain elevators do, but they buy product every day.
That cross-effect is why some industry veterans sound almost bored by the ban idea. They have seen this movie. The sequel is never “cheap diesel forever.” The sequel is “unexpected price in the product you forgot to mention.”
I keep coming back to that because voters will judge the policy by the sticker they see most often. If diesel eases and regular gasoline jumps, the political win melts in public. That is not a clever prediction. It is basic household arithmetic.
How Markets Already Voted
Futures moved on the rumor. Refiner equities moved on the rumor. That is a tell. If investors thought a ban would mint easy domestic profits, those stocks might have rallied. They did not behave like winners. They behaved like operators about to lose a sales channel.
That reaction should humble anyone who thinks a letter from business groups is just lobbying noise. Lobbying is real. So is the tape. When the tape and the letter say the same thing, I pay attention.
Does that mean exporters are saints? Of course not. Companies chase the best netback. They will sell to the buyer who clears the dock at the best after-tax, after-freight number. Policy can change that number. Policy cannot repeal the habit of maximizing it.
A Cleaner Way To Think About “More Diesel At Home”
If the goal is more barrels inside the United States, start with production and logistics, not a padlock. Higher utilization at plants that can swing yield. Faster turnaround discipline where safety allows. Smarter coastal transfers. Clearer seasonal signals so inventories build before harvest, not during the speech about harvest.
- Map where diesel is tight by region, not by slogan.
- Check whether refiners can raise diesel yield without starving gasoline.
- Use storage and transfers before using export locks.
- Watch global disruptions that no domestic ban can fix.
- Measure household freight costs, not just the highway pump.
None of that fits a chant. All of it fits a market that has to keep planes flying and trucks rolling in the same week.
The Midterm Temptation
Election calendars compress judgment. A 90-day idea sounds perfect because 90 days can cover a news cycle and a campaign ad. Energy systems do not reset on 90-day clocks. Contracts, maintenance, and crude purchases live on longer rails.
That mismatch is how well-meaning pressure becomes a self-inflicted shortage. I have watched versions of this in other commodities. Export threats, price caps, sudden licensing. The first headline is relief. The second headline is why shelves look thin.
Farm-state anger is legitimate. Using that anger as a design spec for refining policy is how you get a rule that wins a week and loses a quarter.
What Families Should Watch Next
Skip the theater and watch three things. First, official language. “Full ban” versus “targeted flows” is the whole game. Second, diesel cracks and gasoline cracks moving together or apart. Third, refinery run rates. If runs fall after a restriction, the letter writers will look prophetic.
Also watch regional spreads. The United States is not one pump. The Gulf Coast, the Midwest, and the West Coast can tell three different stories on the same Thursday. A national average hides that. Farmers do not buy the national average. They buy the rack down the road.
Quick field check:
  Pump price is the symptom.
  Run rates are the cause.
  Exports are one valve among several.
  Global outages still set the weather.
A Personal Read, Without The Podium
I do not blame anyone for wanting cheaper diesel. I want cheaper diesel. I also want refiners to keep making it. Those two wishes only travel together if the commercial reason to produce remains intact. Slam the export door and you may get a photo-op. You may also get a quieter cut in output that shows up later as another spike.
Is there a world where a narrow, temporary measure helps a specific corridor through harvest? Maybe. Narrow is the word that matters. Temporary is the other word that matters. Blanket is the word that should stay in the drawer.
The joint letter will be dismissed in some rooms as self-interest. Fine. Self-interest can still describe a mechanism correctly. If less access to foreign buyers means less reason to maximize diesel yield, prices do not stay friendly. That is the mechanism. Argue with it if you have a better model. Do not argue with it by shouting “keep it here” louder.
The Quiet Cost Hidden In Freight
Even households that never touch a diesel nozzle pay diesel. The cereal box, the online parcel, the lumber stack at the yard, the milk crate behind the store door. Freight is a tax that does not call itself a tax. Raise diesel for long enough and that tax shows up in checkout math.
That is why the letter mentioned families alongside farmers and truckers. The chain is one chain. Break a link at the rack and the receipt at the register eventually twitches. People will blame grocers. They should look one step upstream.
Capacity Is A Constraint, Not A Speech Line
Feasibility talk keeps returning to refining capacity. Good. Capacity is the adult in the room. If plants are already stretched, a ban reallocates scarcity. If plants have spare room to make more diesel without wrecking other yields, a ban is still a clumsy tool compared with letting them sell into the bid that keeps units running hard.
Capacity also includes people, not just towers. Turnarounds, skilled crews, spare parts, and weather windows decide whether “just make more” is a plan or a wish. Energy officials who have actually run field businesses tend to remember that. It is why some of the public comments have sounded more cautious than the campaign-trail version of the same idea.
What A Sensible Compromise Could Look Like
If Washington feels it must act, the least harmful path is targeted, time-limited, and paired with a production incentive rather than a production penalty. Think reporting, surge logistics, and regional transfers before think embargo. Think winter and harvest buffers before think morality play about cargo leaving a dock.
A compromise also tells refiners the rule will not become a habit. Investment hates habits that appear in odd-numbered years and vanish after Election Day. Announce uncertainty and you get caution. Caution looks like lower incremental barrels.
The most efficient path is the one that adds diesel without starving gasoline, jet fuel, and the incentive to keep running hard.
Reading The Next Two Weeks
Watch for a trial balloon that is smaller than a ban and louder than a study. Watch farm-state statements that treat any hesitation as betrayal. Watch industry statements that treat any restriction as catastrophe. Truth usually sits in the unglamorous middle, where logistics memos live.
Also watch overseas disruption. Another refinery hit abroad can do more to U.S. pump prices than any letter or speech at home. That is an uncomfortable fact for domestic politics. It remains a fact.
If officials keep repeating that a blanket freeze is not under discussion, markets may settle. If the phrase “hold the diesel” keeps returning, volatility stays. Volatility itself is a cost. Hedging gets pricier. Contracts get shorter. Planning gets dumber.
The Human Texture Behind The Barrels
There is a driver in a cab doing mental math on the next fill. There is a grower wondering whether the dryer and the truck to town will erase a decent yield. There is a dispatcher trying to explain a surcharge without losing the account. Those people are not props in an export debate. They are the reason the debate exists.
Respecting them means refusing magic. Magic is “ban the boats and the number falls and stays down.” Reality is “change one valve and the whole plant rebalances.” I would rather sound like a wet blanket than sell a story that pops in week one and bites in week six.
A Last Pass Over The Core Claim
Business groups say a diesel export ban would raise fuel prices, not lower them, after the first jolt. The mechanism is less production and tighter supply. Political pressure says voters cannot wait for mechanisms. Both statements can be true at the same time. That is what makes the moment sharp.
The United States can want lower diesel costs and still refuse a tool that shrinks diesel output. Those are not opposite loyalties. They are the same loyalty applied with patience. Patience is in short supply before an election. Fuel is too.
If there is a line worth keeping on the fridge, keep this one. Do not confuse moving barrels around with making more barrels. One is a press conference. The other is an industry still willing to run.
And if the administration studies feasibility, good. Study it with run rates, yield slates, coastal balances, and freight into farm country on the same page. Leave the padlock for a door that actually isolates the problem. This door opens onto a world market that is already short, already nervous, and already pricing every American decision in real time.