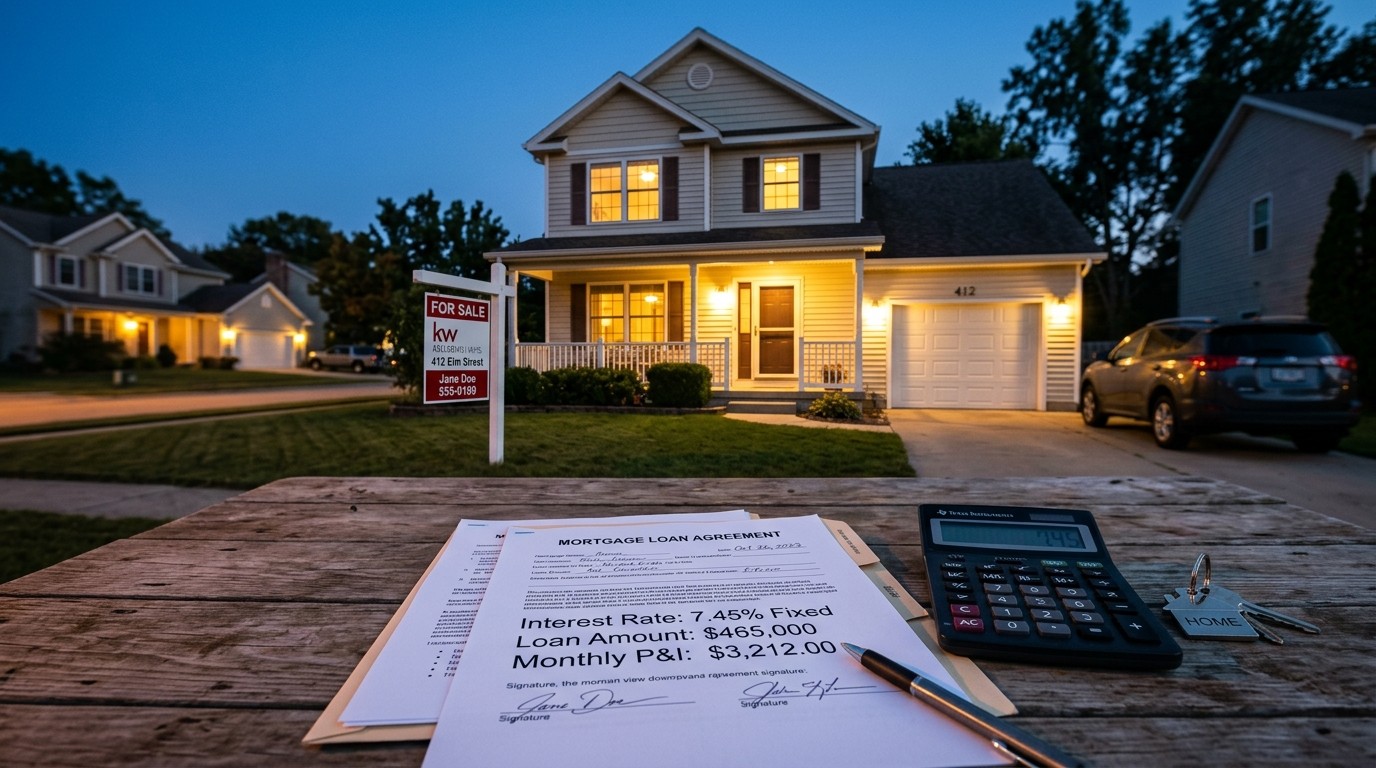

I still remember how 6% felt like a line in the sand. Then 7% showed up, and people treated it like a storm that would pass by Friday. It did not. On Thursday the average 30-year fixed mortgage rate jumped to 7.45%, and the move was not a rounding error. It was a sharp, same-day climb that left a lot of buyers staring at payment quotes they did not expect when they woke up.
What Drove The Sudden Spike In Mortgage Rates
Mortgage rates do not float in a vacuum. They loosely track the 10-year Treasury yield, and that yield had a rough day. Lenders priced morning quotes one way, then had to reprice again after bonds sold off in the afternoon. That is why one daily reading can look tame at breakfast and ugly by dinner.
From the prior session, the 30-year fixed was up about 19 basis points. That is a big one-day swing in this market. In practical terms, it is the difference between a payment that almost works and a payment that quietly kills the deal.
Sellers decided to sell… a lot. There was no single, clean headline that explains the afternoon move.
That comment from a market operator stuck with me because it is honest. Sometimes the tape just breaks. People invent stories after the fact. Oil, growth data, policy talk, inflation scars from earlier in the month. All of those can matter. None of them, on their own, fully explain why bonds dumped so hard after lunch.
Why Daily Quotes And Weekly Averages Tell Different Stories
Here is where a lot of readers get tripped up. A weekly average can print just above 7% on the same morning that live lender quotes are already racing higher. One number looks backward. The other is trying to catch the market in real time. If you only watch the weekly print, you will feel late. If you only watch the daily print, you will feel whiplash.
I prefer the daily survey when I am trying to understand what a borrower might actually be offered today. Weekly averages still have value for the long arc. They just should not be used as a same-day shopping tool.
The Path From Sub-6% Back Above 7%
Cast your mind back to late February. The 30-year fixed had dipped as low as 5.99%. That number feels almost fictional now. The climb started as geopolitical risk returned to the headlines, then steepened again in September after policy makers lifted the benchmark rate. Markets hate uncertainty. Housing finance hates it even more, because a mortgage is a long promise priced off a moving bond market.
By early September, 7% had already been pierced on a daily basis after inflation data raised the odds of tighter policy. Since then, a mix of official comments, firmer economic prints, and higher energy prices added pressure. None of that is mysterious. The mysterious part is the extra afternoon surge that did not come with a neat catalyst.
What 7.45% Actually Does To A Monthly Payment
People talk about rates as if they were weather. They are not. They are math. A jump of this size changes who can buy, what they can buy, and how long they stay on the sidelines.
Take a simple example. On a $400,000 loan, the difference between 7.26% and 7.45% is not life-changing by itself. Stack that on top of the move from the mid-6s, and it becomes a budget problem. Principal and interest climb. Taxes and insurance do not shrink to make room. Many households were already stretched.
| Loan Amount | Rate Near 7.26% | Rate At 7.45% | Payment Pressure |
| $300,000 | Higher but manageable for some | Noticeably tighter | Medium |
| $400,000 | Already heavy in many metros | Pushes more buyers out | High |
| $500,000 | Requires strong income | Filters the pool hard | Very High |
I am not pretending this table is a full underwriting file. It is a snapshot of direction. Direction matters when inventory of affordable homes is still thin and list prices have not cracked in a clean, national way.
Housing Demand Meets A Confidence Problem
High home prices did not vanish because rates rose. Weak consumer confidence did not suddenly improve. Affordable listings remain scarce in too many zip codes. Put those three together and you get a market that looks busy on paper and exhausted in real life.
Shoppers still want a house. That desire has not disappeared. What disappeared is the easy math. When the payment jumps in a single Thursday, the emotional reaction is often stronger than the spreadsheet reaction. People pause. They wait for a better print. Sometimes they wait too long and miss the few homes that actually fit.
- High asking prices still limit the first-time buyer pool
- Thin affordable supply keeps bidding uneven by neighborhood
- Rate volatility makes pre-approvals feel stale within days
- Confidence surveys keep pointing to caution, not urgency
In my experience, the pause is rational. It is also expensive if rents keep climbing while buyers sit on their hands. There is no perfect answer here. There is only a set of trade-offs that look different in Dallas than they do in Daly City.
How Bond Yields Pull Mortgage Pricing Around
If you want one technical phrase worth keeping, make it this: duration risk. Lenders hold, or hedge, long-dated cash flows. When the 10-year yield rips higher, the hedge costs more and the note rate follows. It is not a one-for-one copy. Spreads can widen or tighten. But the compass still points at Treasuries.
That is why a calm housing story can still get wrecked by a messy bond tape. Housing can look slow. Bonds can look violent. The mortgage desk has to live in both rooms at once.
Perhaps the most interesting aspect is how little the afternoon selloff needed a clean narrative. Markets sometimes move because enough holders decide the same thing at the same minute. Afterward, everyone writes a reason. I would rather admit the reason is incomplete than pretend I have a perfect map.
Policy, Data, And The September Turn
September did not invent this problem. It concentrated it. Inflation reports earlier in the month raised the chance of another official rate hike, and that hike arrived. Stronger activity data then reduced the odds of a quick pivot. Energy prices added another layer of worry about the next inflation print.
None of this means housing is the intended target. It means housing is collateral damage in a fight about prices and growth. Mortgage borrowers feel policy with a lag, then all at once, then with another lag when they try to refinance later.
A combination of policy comments, higher oil prices, and firmer economic data added to the pain after 7% was first broken on a daily basis.
That sequence matters because it tells you this was not a one-headline event. It was a stack. Stacked stories are harder to reverse in a week.
What Buyers Should Do When Quotes Move This Fast
I do not like panic advice. I also do not like fake calm. If you are shopping right now, treat the rate as a moving input, not a personality trait of the house.
- Get a fresh quote the same day you write an offer, not last week’s sheet.
- Stress-test the payment at least a quarter point higher than the quote in hand.
- Ask how long the lock lasts and what it costs to extend if the appraisal drags.
- Keep cash reserves for closing costs that tend to swell when deals get jumpy.
- Walk away from a house that only works if rates fall before closing.
That last point is the one people hate hearing. Hoping the bond market saves the deal is not a strategy. It is a wish. Wishes are fine on a weekend. They are a bad underwriting plan.
Sellers Are Not Off The Hook Either
Owners with a 3% loan do not want to move. That lock-in effect is old news by now, but it still shrinks listings. When rates jump again, the incentive to stay put gets stronger. That keeps supply tight in the very segment buyers need most.
If you must sell, pricing like it is still early 2022 is a good way to sit on the market. Buyers can do the payment math in thirty seconds. They will not pay a trophy price for the privilege of borrowing at 7.45%.
I have found that modest price cuts, cleaner inspection reports, and flexible closing dates do more work than another round of staging photos. The product has to survive a higher payment. Pretty lighting will not change the amortization schedule.
Investors Face A Different Spreadsheet
For investors, the spike is both a filter and a tease. Cap rates do not automatically jump because mortgage quotes did. Rents can lag. Insurance and taxes already ate a chunk of yield in many markets. A 7.45% purchase loan makes thin deals look thinner.
That does not mean every property is a bad idea. It means leverage is no longer doing the heavy lifting. Cash-on-cash returns have to come from rent, operations, and basis, not from cheap debt. I would rather own fewer doors at a real spread than a crowded portfolio that only works if rates retreat by spring.
Simple investor check:
  1. Does the rent cover debt, tax, insurance, and vacancy with room left?
  2. Would the deal still work if the exit cap is not generous?
  3. Can you hold if refinancing stays expensive for years?
If the answer to any of those is a shrug, the Thursday spike just did you a favor. It showed the weak points before you signed.
Regional Reality Versus National Headlines
National averages hide a lot. A coastal market with scarce lots does not behave like a Sun Belt suburb with a long pipeline of new homes. In some places, builders can buy down the rate and keep traffic alive. In others, existing homes dominate and there is no buydown fairy.
That is why a 7.45% print can freeze one metro and merely bruise another. Local wages, local insurance costs, and local inventory matter more than the national talking point. If your market already had a payment problem at 6.8%, this week did not create the issue. It advertised it.
The Refinance Window Is Not Opening
Anyone waiting to refinance out of a recent purchase should reset expectations. A spike of this size does not usually reverse in a tidy two-week rally. It can ease. It can chop. It rarely gifts you a full point back just because the last move felt unfair.
If you already have a low existing rate, congratulations. You are part of the lock-in story. If you closed in the mid-6s and hoped for a quick do-over, Thursday was a reminder that hope is not a hedge.
Psychology Of A Round Number, Then A Break Higher
Seven percent is a headline number. People remember it. Once daily quotes broke that line earlier in September, the next question was never “will we hover?” It was “how messy does the overshoot get?” 7.45% is that overshoot in plain sight.
Round numbers change behavior even when the extra 20 basis points are just arithmetic. Agents hear more “let’s wait.” Loan officers hear more “what if I float?” Floating after a violent up-day is a personality test I would not recommend unless you like surprises.
Is waiting ever right? Sure. If your lease has months left and your savings rate is strong, patience can be cheap. If you are doubling up with family and burning savings on rent plus storage, patience can be the expensive option. Context beats slogans.
How To Read The Next Few Sessions Without Getting Fooled
One down day in yields will produce victory laps. Ignore the lap. Watch whether the 10-year can hold a lower range for more than a session or two. Watch whether lender spreads stay wide even if Treasuries calm down. Spreads can keep mortgage rates sticky after the bond panic fades.
- Track the 10-year yield first, then the note rate
- Compare morning lender sheets with late-day revisits
- Separate weekly averages from live offer quotes
- Look at lock desks, not just social media charts
I’ve found that the readers who stay sanest are the ones who pick a payment ceiling in advance. The house either fits under that ceiling or it does not. The market does not owe anyone a prettier number next Tuesday.
Affordability Was Already The Binding Constraint
It is tempting to blame Thursday alone. That would be sloppy. Prices stayed high. Wages did not sprint in a matching way everywhere. Insurance in several states became its own crisis. Add a lean supply of starter homes and you get a market that was fragile before this spike and more fragile after it.
Fragile does not mean collapsing. Transaction volume can stay dull while prices grind sideways. That is a grind a lot of households will recognize. It is not dramatic enough for a movie. It is more than enough to delay a first purchase by a year.
A Plain Talk Note On Risk
Borrowing at 7.45% is not immoral. It is expensive. If the home is the right home, the job is stable, and the payment leaves oxygen in the budget, expensive can still be acceptable. If the deal requires perfect overtime, a roommate who has not agreed yet, or a refinance fantasy, it is not acceptable. That is not scolding. That is arithmetic with a pulse.
I would rather see a smaller house that survives a rough year than a dream listing that only works in a friendly rate tape. Pride of address fades. A strained payment does not.
What Could Ease The Pressure From Here
A softer inflation path would help bonds. A cooling labor print could help too. A drop in energy prices would remove one of the recent irritants. Builders offering meaningful temporary buydowns can paper over some of the pain at the margin. None of those are guaranteed this month.
On the housing side, more listings in the lower price tiers would do more for affordability than a 10-basis-point dip that lasts three days. Supply is the slower lever. It is also the honest one.
Rates rose because bonds sold off. Housing feels that sale immediately, even when the reasons behind the sale are messy.
Putting Thursday In A Longer Frame
This is not the first time the 30-year fixed has shocked people who thought the worst was behind them. It will not be the last. The useful question is not “who looks foolish for buying last month?” The useful question is whether your household can carry the payment through a dull, expensive market.
From 5.99% in late winter to 7.45% on a Thursday in September is a long walk in a short year. Geopolitics started the turn. Policy and data steepened it. An afternoon bond dump put extra paint on the wall. That is the sequence as I see it, without dressing it up.
If you are mid-transaction, talk to your lender before you refresh social media. If you are only browsing, write down the payment you can defend, then shop inside that box. If you are selling, price for a buyer who is borrowing at today’s quote, not last spring’s memory.
The market will keep arguing about catalysts. Buyers still have to wire funds. That gap between the argument and the wire is where most of the stress lives. Thursday just made the gap easier to see.
And if the next session gives you a slightly kinder quote, great. Lock the payment you can live with. Do not wait for the market to apologize. It rarely does.