

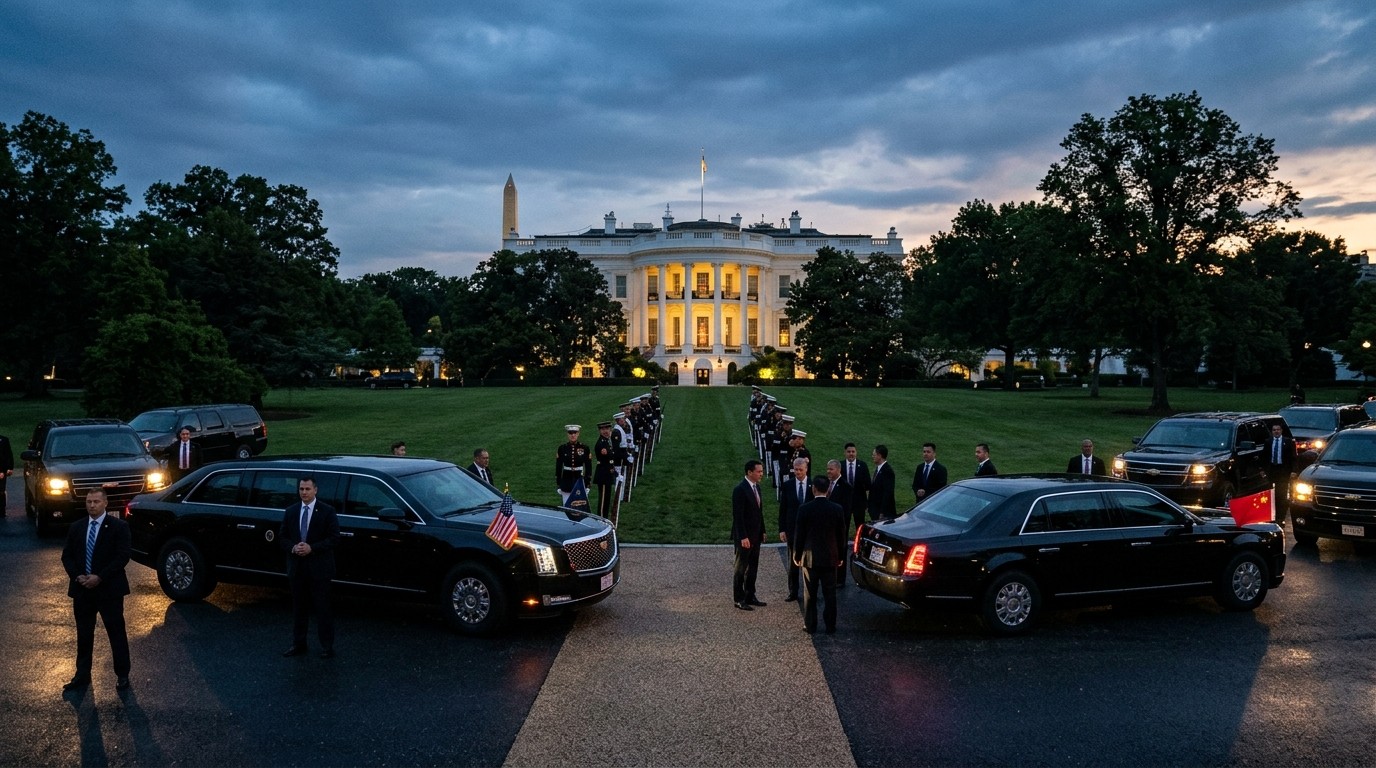

Have you ever watched two people smile for the cameras and still felt the room get colder? That is close to how this White House visit landed. President Xi Jinping arrived in Washington talking about stronger communication and insisting the so-called Thucydides Trap can be overcome. The pageantry was real. The red carpet was real. The market shrug overnight was real too.
What This Summit Actually Changes
I have covered enough diplomatic theater to know the difference between a handshake and a deal. This visit looks like management, not transformation. A two-month extension of the tariff truce takes some heat off the calendar. It does not settle the argument. Investors who wanted a longer pause, closer to six months, got something thinner. That gap between hope and paper is why Chinese stocks slipped while the speeches were still being polished.
The mainland CSI 300 fell about 1.7 percent overnight. The Hang Seng China Enterprises Index managed to flatten by the close after giving back an earlier drop. Broader Asian equities felt the same draft. A global bond selloff was already underway after firmer U.S. data and a weak Treasury auction. Add a short trade truce and you get a familiar cocktail: less panic, more skepticism.
The Arrival Scene And The Message Behind It
Xi’s first White House visit since 2015 was staged as a state occasion. There was an arrival ceremony, opening remarks, talks, a South Lawn event, and a black-tie dinner later with technology executives. Private tea and a National Archives stop were also on the schedule. That is a lot of choreography for a relationship that both sides now describe in the language of risk control.
Xi’s line about communication was the line that traveled. Strengthen the channel. Avoid the trap in which a rising power and an established power slide toward conflict. It is a classic phrase, and it is doing a lot of work. In my view, it is less a promise than a plea for time. Time to keep talking while the hard files stay open: tariffs, rare earths, chips, farm goods, Iran, and Taiwan.
We should strengthen communication. The Thucydides Trap can be overcome.
– Remarks attributed to President Xi on arrival
Pretty words. Necessary words, even. Still, markets price paper, not poetry. The two-month window through January 10 removes an immediate cliff. It also tells you how little trust is sitting on the table. A former senior trade official put it bluntly on television: this is a far shorter extension than Beijing wanted. China, in that telling, hoped to stretch the truce toward the end of the current U.S. term. Washington answered with a stopwatch.
Why Two Months Feels Like A Warning
Short truces are not accidents. They are leverage. If rare earth shipments and agricultural purchases are still disappointing from Washington’s point of view, a brief pause is a way to keep the next deadline close. I have found that investors often hear “truce” and relax. Pros hear the length and start counting.
Wall Street desks had floated hopes of three to six months. Some traders I talk with wanted six, full stop. Two months is a different animal. It can stabilize a week. It rarely rebuilds a multiple. Equities like duration. Credit likes duration. Supply chains like duration. Two months is a memo that says: we are still watching you.
- The immediate tariff cliff is delayed, not removed.
- Rare earth export behavior remains a live complaint.
- Farm purchases, including soybeans, are still part of the scorecard.
- A proposed Board of Trade idea covering roughly $30 billion in goods on each side is discussion, not done.
- Boeing aircraft and LNG purchases are on the wish list, not the signed pile.
That list is why the tone from strategists was cautious rather than celebratory. One veteran market voice noted that many clients had been hoping for a longer bridge and that a short one may not help equities much. Fair point. A pause that expires in winter is still a winter problem.
What The Agenda Really Contains
Trade is the headline because tariffs are easy to measure. The rest of the folder is messier. Technology restrictions sit next to allegations that some Chinese firms distilled American models. Low-cost Chinese open-weight systems are already pressing U.S. frontier labs and thinning the sense of an unassailable moat. A proposed AI hotline sounds almost friendly until you remember why hotlines exist: to stop a misunderstanding from becoming a spiral.
Then there are the strategic files that never stay in the trade ministry. Taiwan. Iran. Export controls on advanced chips. Access to materials that make magnets, motors, and missiles possible. You can serve steak at a state dinner and still be arguing about all of that in the next room.
| File | What Washington Wants | What Beijing Wants |
| Tariff truce | Leverage and proof of purchases | A longer, quieter pause |
| Farm goods | Visible soybean and related buys | Flexibility on timing and price |
| Energy and aircraft | LNG and jet orders as political wins | Terms that do not look like surrender |
| Technology | Tighter control of advanced chips | Relief from export limits |
| Materials | Predictable rare earth flows | Strategic control of supply |
Look at that grid long enough and you stop expecting a grand bargain. The realistic product of a summit like this is a communique, a few purchase announcements if luck holds, and a promise to keep talking. That is not nothing. It is also not the multi-year settlement some portfolios were quietly underwriting.
How Markets Read A Short Truce
Overnight China weakness was the first draft of the verdict. It was not a crash. It was a mood. When the extension lands shorter than hoped, you get selling in names that needed a longer runway. You also get a reminder that Asia still trades the U.S. rates complex as much as it trades diplomacy. Stronger American data and poor auction demand had already pushed yields. Equity risk then had to digest both stories at once.
Perhaps the most interesting aspect is how quickly the conversation shifted from “will they meet” to “how long is the paper.” That is a mature market. The meeting itself was priced. The duration was not fully priced. Duration is the thing that changes capex plans, shipping bookings, and the willingness of a purchasing manager to lock in a year of inventory.
In my experience, the first session after a diplomatic event is almost never the last word. If dinner produces a surprise purchase package, futures can snap back. If the language stays vague, the two-month clock becomes the story into year-end. Traders will map January 10 the way they map option expiries. Because that is what it is: an expiry with flags.
Wall Street’s Base Case Is Modest
Across large banks and research shops, the shared expectation heading into the talks was limited breakthroughs. That is a polite way of saying: do not build a model on peace. Manage the relationship. Keep it from breaking. Do not pretend the structural rivalry has been retired.
We are at a point in the relationship where big deliverables are just no longer possible. The work is about managing ties and keeping them stable, not transforming them.
– Assessment from a veteran trade negotiator
That sentence should be taped to a few risk dashboards. Stability is tradable. Transformation is a different asset class. If you came into this week overweight the idea of a comprehensive deal, you were trading hope. If you came in looking for a pause that prevents an autumn rupture, you got something closer to the brief.
I would still watch the dinner list. Technology names in the room matter because the next fight is not only about soybeans. It is about models, silicon, and who sets the rules for the stack that runs everything from warehouses to weapons planning. A photograph with executives is not a license. It is a signal that both capitals know where the future margin sits.
Rare Earths, Farms, And The Quiet Scorecard
Rare earths are the unglamorous hinge. They do not trend on social feeds the way a state banquet does. They do decide whether factories keep humming. Allegations of tight or tactical export behavior are exactly the sort of grievance that shortens a truce. Agricultural purchases sit on the other side of the ledger. They are visible, rural, and politically useful. When those shipments lag, the White House hears about it from places that do not care about communiques.
A Board of Trade structure covering tens of billions each way is an attempt to put a frame around the haggling. Frames help. They do not erase the instinct to use trade as a tool of statecraft. Anyone who thinks a committee will depoliticize soybeans and magnets has not sat through a midterm cycle.
- Track official language on export licenses and farm commitments in the first 72 hours after the dinner.
- Watch whether any dollar figure is attached to aircraft, LNG, or grain.
- Compare the January 10 date against options open interest and event-vol in China-sensitive names.
- Treat chip-rule chatter as a separate tape from the tariff tape.
- Assume Taiwan and Iran stay in the background briefing even if they stay out of the toast.
That is a practical list, not a prophecy. Markets do not need a prophecy. They need a checklist that survives the next headline.
The Bond Market Did Not Wait For The Toasts
It is easy to write this week as a China story. It is also a rates story. Stronger U.S. data and a sloppy auction reminded everyone that the Federal Reserve path is still a live argument. When yields jump, risk assets everywhere feel it. Asian equities do not get a diplomatic exemption from that math.
So you had two currents in the same stream. One was geopolitical relief that was smaller than hoped. The other was domestic American tightness in funding conditions. Put them together and you understand why the bounce in some China shares faded into a flat close rather than a victory lap.
I’ve found that people underestimate how often diplomacy and duration collide. A charming summit cannot reprice a two-year note by itself. If traders decide the Fed still has work to do, the best communique in the world becomes a sideshow by Friday.
AI, Chips, And The Dinner Table Problem
The guest list is a tell. When chip and model leaders sit near the official party, you are looking at the next decade of friction. Open-weight systems from China are cheap and good enough for a shocking number of tasks. That pressure is already changing how American labs talk about moats. Export rules on advanced processors are the counterweight. Distillation disputes sit in the middle like a family argument nobody wants to have in front of guests.
An AI hotline is the kind of idea that sounds bureaucratic until you imagine a week when a model-related incident, a sanctions designation, and a Taiwan scare arrive together. Hotlines are for bad nights. Building one during a polite dinner is a sign that both sides can picture the bad night.
Will that produce a market-moving paragraph in a joint statement? Maybe not. It can still change how compliance teams write memos. And memos, over a quarter, change orders.
What “Overcoming The Trap” Would Actually Require
The Thucydides line is seductive because it flatters both capitals. It says history is a warning, not a sentence. Fine. Overcoming it would still require more than ceremony. It would require predictable market access, fewer surprise controls, credible purchase schedules, and a habit of talking before acting. That is a high bar for two systems that use economic tools as strategy.
I am not cynical about talking. Talking is better than drifting. I am skeptical that a single visit resets the slope of the relationship. The slope has been set by industrial policy, military planning, and domestic politics that do not take instructions from a South Lawn program.
If you want a human analogy, think of two neighbors who agree to keep the fence painted while still arguing about the property line. The paint job matters. The survey still matters more.
How To Think About Positioning Without Playing Prophet
This is not a call to dump or chase a region. It is a call to match time horizon to document length. A two-month truce supports tactical trades more than structural ones. Exporters who needed a year of tariff clarity did not get a year. Chip-adjacent names still live under policy risk. Commodity names tied to Chinese buying still live under the purchase-scorecard risk.
Working map for the next few weeks:
  40% duration of the truce and any add-on language
  25% hard purchase numbers if they appear
  20% U.S. rates and auction follow-through
  15% unexpected security headlines
Ugly little map. Useful little map. It keeps you from treating a state visit like a merger announcement.
If concrete concessions show up, the tape can look friendlier fast. If the language stays atmospheric, January becomes a second event risk. Event risk is not the same as disaster. It is a reason to size positions as if the calendar still has teeth.
The Human Texture People Skip
There is a temptation to reduce all of this to indexes. Resist it for a minute. A state visit is also protocol, spouses on a receiving line, a flyover, a camera that lingers a second too long on a face. Those images travel in China and in the American Midwest for different reasons. One audience looks for respect. The other looks for toughness. The leaders have to feed both rooms at once. That is why the public script sounds warmer than the private bargaining.
I’ve sat through enough of these cycles to recognize the pattern. Morning optimism. Afternoon footnotes. Evening dinner. Next-morning research notes that all say “limited breakthroughs” in slightly different fonts. The pattern is not a failure. It is the relationship as it now is.
Does that mean nothing good can come out of the room? Of course not. A working channel on AI incidents would be good. A clearer farm schedule would be good. A less jumpy rare earth license process would be good. Good is available. Grand is expensive.
What To Watch After The Dinner Ends
The useful work starts when the motorcade leaves. Read the joint language for verbs, not adjectives. Count the nouns that come with numbers. See whether agencies issue follow-up notices on export processes. Listen for farm-state reaction, because that constituency can shorten a truce as fast as any think tank.
Also watch the next Treasury auction and the next inflation print. Diplomacy does not float free of the cost of money. If yields keep climbing, even a tidy Washington photo can fail to lift risk assets for long.
- Joint statement verbs and any dated commitments
- Purchase figures for grains, energy, and aircraft
- Regulatory follow-through on materials and chips
- Equity reaction in China-sensitive sectors after the first bounce fades
- The January 10 clock as a volatility magnet
Keep the list short enough to use. Long enough to stay honest.
A Clear-Eyed Close
Xi came to Washington asking for more communication and offering the hope that history’s trap is not fate. The United States rolled out ceremony and kept the tariff pause brief. Markets heard both messages and chose the shorter one as the thing that pays.
That feels right to me. Not gloomy. Just adult. Rival systems can share a dinner and still refuse to share a decade of certainty. Investors who accept that can trade the pause without marrying the press release. Investors who wanted a six-month hug will need a new plan before winter.
The trap, if it is overcome, will not be overcome in one evening. It will be overcome in a string of boring, enforceable, numbered paragraphs. Until those show up, treat the visit as what it is: an important conversation, a thinner safety net, and a reminder that global markets still take their cues from both the South Lawn and the bond desk.



