

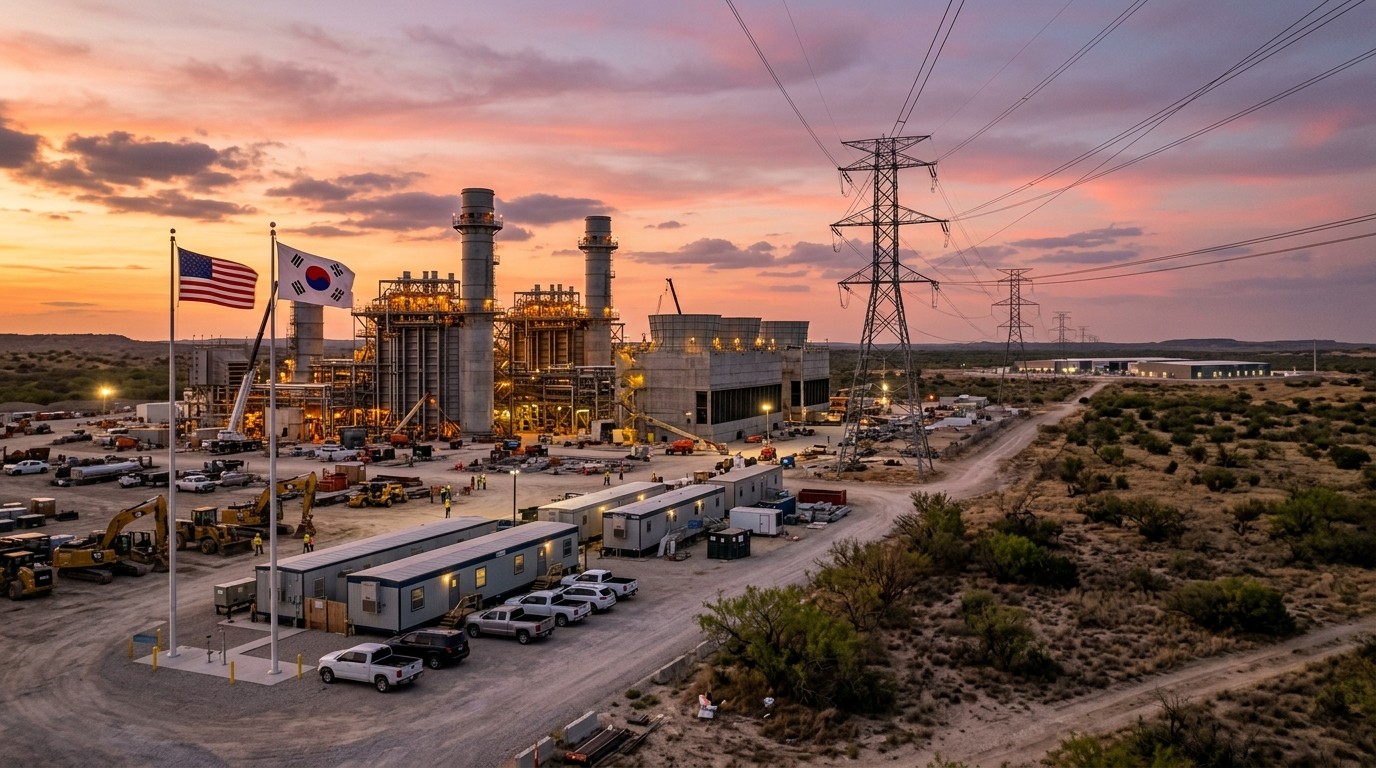

What would you do if you had to park the first slice of a $350 billion promise in someone else’s country, under political pressure, and still call the project commercially reasonable? That is roughly the spot South Korea found itself in after months of tariff talk, late-night bargaining, and a very public clock. The first check is now pointed at a gas-fired power complex near Encinal, Texas, a town of a few hundred people that is about to learn what happens when megawatts become a diplomatic currency.
Why A Quiet Texas Town Suddenly Matters
I’ve been watching energy and trade stories long enough to know that the headline number is rarely the whole plot. The plant is described as a roughly $22.3 billion, 6.3-gigawatt gas project, with talk that Washington wanted the package closer to $25 billion. On paper it is a power station. In practice it is the opening move of a much larger pledge that also covers shipbuilding and other so-called strategic industries.
Encinal is tiny. Real estate there will not stay sleepy if thousands of construction jobs, transmission work, and contractor traffic actually show up. That part is easy to picture. Harder to picture is who will buy the electricity, when the turbines arrive, and how a 50/50 cash-flow split with the United States still leaves Korea whole after fuel, operations, and interest.
Reports say Seoul picked the site this week and that a White House announcement could follow quickly, depending on other diplomatic scheduling. The two presidents met briefly on the sidelines of a New York gathering. Final U.S. approval is still required. In other words, the ribbon is not on the fence yet.
The Staged Build And The Missing Customer
The construction plan is staged, which is sensible and also a tell. First comes about 1.4 gigawatts of simpler, faster gas turbines. Later comes roughly 4.9 gigawatts of more efficient combined-cycle generation. Fast power first, efficient power later. That is how you try to get electrons on the wire before the heavy equipment queue swallows the calendar.
Here is the awkward part. No offtakers have been confirmed. There is no signed power purchase agreement. Signing is talked about for 2027. That is a long time to live with a $22 billion story that still needs a buyer. I’ve found that energy projects can look inevitable in a press briefing and still stall when the first long-term contract refuses to materialize.
Every project is supposed to be commercially reasonable, yet the definition of reasonable sits with a U.S.-led committee, and the last word sits in Washington.
Korean officials have told lawmakers the plant could throw off $43 billion to $45 billion of revenue over 20 years, enough, they argue, to recover principal and interest. Do the napkin math. That is about $2.2 billion a year of gross revenue. Gross is not cash in the bank. Fuel is the main variable cost of a gas plant. Operations, maintenance, and financing sit on top. Korea only keeps half the cash flow until it is repaid. After that, the split flips hard: Korea 10 percent, the United States 90 percent.
On a plain reading, recovering more than $22 billion plus interest from a 50 percent share means distributable cash has to be a lot healthier than “revenue is twice capex.” Seoul has not published a clean bridge from those headline revenues to recovery under the split. That gap is not a nitpick. It is the heart of the deal.
How The $350 Billion Pledge Is Structured
Under the late-2025 framework, Korea is expected to put up $200 billion of upfront capital for strategic-industry projects, capped around $20 billion a year, plus a separate $150 billion tied to shipbuilding. Project cash flow is shared 50/50 until Korea recovers principal and interest. After recovery, Korea’s share drops and Washington’s share soars.
It is a generous arrangement if you are the host. It is a tougher arrangement if you are the party wiring the money. Korean ministers say they negotiated hard for projects that Korean firms can actually enter. The president has talked about sleepless nights. That phrase is not poetry. It is the sound of a mid-sized export economy trying not to get boxed by tariffs while still looking commercially adult at home.
- Upfront Korean capital for designated U.S. projects, with an annual ceiling
- A separate shipbuilding envelope that is large enough to move yards and suppliers
- Cash-flow sharing that favors recovery first, then heavily favors the United States
- An investment committee that judges what counts as commercially reasonable
- Political risk if Seoul objects too loudly
Perhaps the most interesting aspect is not the legal text. It is the leverage. Objecting to a project can be read as stalling. Stalling can be answered with tariff heat. That is not how a textbook project-finance memo is supposed to work. It is how a trade-and-security package works when both sides know the other side is watching domestic headlines.
Japan Went First, And The Template Is Visible
Tokyo moved earlier with a still larger pledge. The first big energy slice was a multi-gigawatt gas plant in Ohio, later joined by talk of small modular reactors in other states. Cost per kilowatt on the Korean Texas plan and the Japanese Ohio plan sits in a tight band, a little above $3,500 per kilowatt. That is rich compared with older U.S. combined-cycle builds from before the artificial-intelligence power scramble.
Why the premium? Because every large buyer wants the same megawatts in the same window. When hyperscalers, chip plants, and politicians all chase dispatchable power at once, contractors price the congestion. Steel, labor, interconnection, and especially turbines stop behaving like calm commodities.
In my experience, identical unit costs across two allied pledges are not a coincidence. They are a market clearing price under political time pressure. You can call it a template. You can also call it what happens when capital is abundant and hardware is not.
Turbines Are The Real Bottleneck
Money, oddly, looks like the easy input. Large gas turbines are widely described as sold out deep into the decade. Some developers talk about deliveries slipping toward the early 2030s if they order now. A few are even dusting off older steam-based approaches just to get something online sooner. That is not nostalgia. That is scarcity.
Encinal’s two-step design tries to work around the queue: simpler machines first, combined-cycle blocks later. Fine. Everyone else can read the same calendar. Getting in line is not the same as jumping the line. Korean capital does not manufacture extra hot-section parts out of thin air.
Bank research circulating this month has lifted forecasts for behind-the-meter generation because grid connection times keep stretching. On-site gas is expected to cover a sizable share of U.S. data-center demand by 2030. The equipment names that usually win that race are familiar Western and Japanese industrials. Korean suppliers are not automatically on that short list. So a Korean-funded plant can still send a large slice of equipment spend outside Korea. That is an uncomfortable talking point in any National Assembly hearing.
Competition is not only American. A major Chinese cloud operator has talked about tens of gigawatts of data-center power this decade. One company’s target can dwarf a single Texas complex. The turbine market does not care which flag is on the term sheet. It cares who signed the purchase order first and who can pay cancellation fees without blinking.
Who Might Buy The Power, And Who Is Borrowing To Need It
The obvious customers are large computing platforms and advanced manufacturers. They are not short of balance sheet. Credit desks have been raising forecasts for investment-grade bond issuance by those same firms, with a big share expected in dollar markets. They are borrowing to build halls that eat electricity the way older factories ate coal.
The bull case for Seoul is simple. Someone signs a long contract by 2027, the plant is in the interconnection queue, and the revenue story starts to look less like a slide and more like a model. The bear case is also simple. Korea has fronted a huge check on the assumption that a buyer will appear while the loudest part of the computing capex cycle may already be frosting at the edges.
I do not need to pick a winner today. I do need to say the timing risk is real. Power plants last decades. Fashion in capital spending does not.
| Item | What Is Known | Open Question |
| Headline cost | About $22.3 billion, possibly pushed toward $25 billion | Final approved budget and contingencies |
| Capacity | About 6.3 GW in two stages | Actual delivered megawatts after derates |
| Offtake | No confirmed PPA yet | Who signs, at what price, for how long |
| Cash split | 50/50 until Korean recovery, then 10/90 | True free cash after fuel and opex |
| Equipment | Heavy-duty turbines scarce through the decade | How much spend lands with Korean firms |
Revenue Math That Still Needs A Bridge
Let us stay with those $43 billion to $45 billion figures. Twenty years. Call it $2.15 billion to $2.25 billion a year. A modern combined-cycle fleet can earn that in a tight market with high capacity factors and strong contracted prices. It can also miss by a mile if gas spikes, if the plant runs as a peaker more than a baseload machine, or if contracted prices come in soft because too much supply shows up in the same Texas corridor.
Texas already knows boom-and-bust in generation. Merchant exposure is not a morality tale. It is weather, gas basis, and transmission constraints wearing a price tag. A contracted plant is a different animal. Until the contract exists, treat the revenue slide as a hope with units attached.
Also remember the split. Half the cash until recovery is not half the revenue. Cash is what remains after the plant buys fuel and keeps the blades spinning. If margins are thin in some years, the clock on principal recovery stretches. Interest does not nap while you wait.
Rough check investors will run anyway:
  Headline 20-year revenue
  minus fuel
  minus O&M
  minus sustaining capex
  minus financing drag
  = distributable cash
  times 50 percent
  = Korea’s recovery engine
If that engine cannot clear principal plus a fair yield, “commercially reasonable” becomes a political phrase. Markets notice the difference even when communiqués do not.
Local Impact In A Town Of A Few Hundred
Encinal will feel this first as trucks, then as wages, then as housing strain. A multi-gigawatt site is an industrial weather system. Temporary housing, road wear, school enrollment, water, and emergency services all move. Property that looked sleepy can reprice fast when a project this size is even rumored to be real.
That is the human scale sitting under the geopolitics. A global pledge lands on a county map. People who never asked to host a diplomatic down payment will host the dust. If the project is delayed, they host the waiting too.
I’ve walked enough energy towns to know the pattern. The first year is hope. The third year is traffic. The tenth year is whether the tax base outlasted the construction boom. Encinal deserves that longer view, not just a population joke in a headline.
The Broader Relationship Is Not Only About Electrons
The plant arrives while other files sit open. Washington has pressed Seoul on security questions far from Texas. Seoul has drawn a line against combat deployments in a Middle East fight. Nuclear-powered submarines remain a Korean ask with limited visible progress. One official channel has suggested that movement on sensitive defense items may wait until investment announcements land. Pay first, then talk. That linkage, if accurate, explains the urgency better than any heat-rate spreadsheet.
Nuclear cooperation and a smaller Alaska gas export concept are said to be next in line. Korea has also been negotiating a reduced minority stake in a major U.S. nuclear vendor after seeking a larger slice. The pattern is consistent. Capital is the greeting. Technology access is the hope. Political permission is the gate.
- Announce a visible U.S. energy project with a round number.
- Keep annual capital within the pledged ceiling so domestic critics can count.
- Argue that Korean firms gain a beachhead in American power and industry.
- Use the announcement as diplomatic proof of good faith.
- Save harder files, from shipyards to nuclear know-how, for later rounds.
Is that cynical? A little. Is it how allied industrial policy has been working this cycle? Also yes.
Data Centers, Chip Fabs, And The Power Panic
Washington’s appetite is not mysterious. Computing clusters and advanced factories do not wait politely for transmission upgrades. Grid queues in the United States and Europe have lengthened. Behind-the-meter gas has become the blunt instrument. If you cannot get a line, you bring a plant to the parking lot, or at least to the neighboring parcel.
That is why a 6.3-gigawatt complex is not a random trophy. It is sized like a regional answer to a national bottleneck. Whether it is the right answer depends on methane supply, water, permits, and the honesty of demand forecasts. Demand for computing is real. The slope of that demand is a debate. Build too slow and you ration growth. Build too fast and you own stranded steel.
Analysts have raised their outlook for on-site generation by tens of gigawatts this decade. They still prefer a short list of turbine and engine makers. That preference matters for anyone who thought a Korean check would automatically mean Korean factories humming. Content rules can be written. Physics and vendor lead times are ruder.
What “Commercially Reasonable” Can Hide
The official line is that every project must clear a commercial test. The fine print is who grades the test. A U.S.-led committee decides. The American president can have the last call. Seoul can object. Objection has a price if tariffs are the background music.
A commercial test that can be overruled by trade leverage is still a political test wearing a spreadsheet.
That does not make the plant a stunt. Gas generation next to hungry load is a coherent industrial idea. It does mean citizens in Korea are entitled to a clearer recovery model than “revenue over 20 years looks like twice the capex.” Twice the capex is not a return if you only own half the cash and fuel takes a bite every day.
Industry officials say intense talks aimed at viable projects and at widening Korean companies’ path into the U.S. market. That goal is fair. Entry into a market is not the same as earning a market return. Both can be true. They should not be blended into one slogan.
Risks That Belong On One Page
Let me put the risks in ordinary language, because the deal will be sold in ordinary language.
- Offtake risk: no signed long-term buyer as of the latest public descriptions
- Equipment risk: turbine slots are scarce and slipping
- Fuel and margin risk: gross revenue is not free cash
- Split risk: 50 percent of cash until recovery, then a steep drop in Korea’s share
- Political risk: the commercial label can move with the trade climate
- Cycle risk: computing capex can cool after a frantic build
- Local risk: permits, water, transmission, and community capacity in a small town
None of those kill the project by themselves. Together they explain why a careful reader should not confuse an announcement with an operating asset.
What Comes After The First Check
Even if Encinal is approved tomorrow, most of the $350 billion is still unplaced. Nuclear files, a slimmed Alaska concept, shipbuilding, and other industrial bets will need sites, partners, and the same awkward test of reasonableness. The first project is a proof of motion. It is not proof that the whole envelope will earn its keep.
Watch three things next. First, a real power contract with a name, a volume, and a price shape. Second, a turbine reservation that looks like hardware, not hope. Third, a published recovery model that survives a skeptical committee in Seoul, not only a friendly briefing in Washington.
If those three arrive, the Texas plant can be what allies say they wanted: dispatchable power for a strained grid, and a visible down payment on a strained relationship. If they do not, Korea will have taught every finance ministry a lesson. Large pledges close press conferences. Plants close when customers, machines, and math agree.
I keep coming back to that small town and that large number. $22 billion is a first installment, not a full sentence. The remaining $328 billion will be harder, because the easy symbolism gets used first. After symbolism comes steel. After steel comes the bill for gas. After the bill comes the argument over who really got paid.
That argument is the story. The plant is only the stage.



