

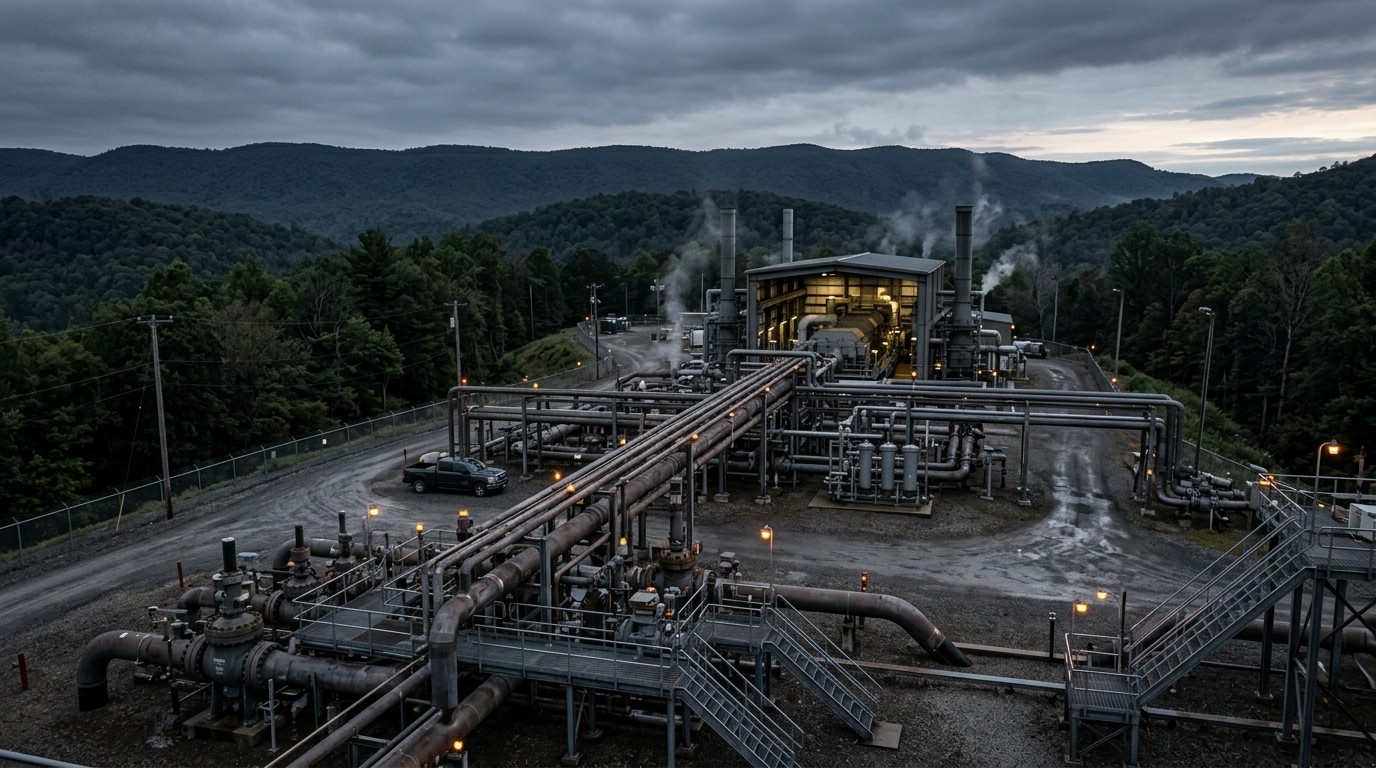
Natural Gas Prices Spike After Pipeline Force Majeure

A sudden mechanical issue on a major West Virginia gas line just forced a hard cut to firm flows. Prices jumped fast. The real question is how long the restriction lasts, and who gets squeezed next.
Financial market analysis from 25/09/2026. Market conditions may have changed since publication.
Have you ever watched a market that looked well supplied one day and suddenly tight the next, all because one stretch of steel in the hills of West Virginia hit a mechanical snag? That is the story unfolding around natural gas this week. A major transmission system serving Appalachian supply just declared force majeure after an unexpected mechanical issue forced an immediate pressure reduction. Futures reacted the way they often do when takeaway capacity vanishes without warning. They jumped.
What The Pipeline Disruption Actually Changes
I have covered energy markets long enough to know that traders do not panic over every maintenance notice. They panic when firm service is cut, when the constraint is set to zero, and when the operator cannot yet say when service returns. That combination arrived with the Mountaineer XPress segment between the Mt. Olive compressor area in Jackson County and the Saunders Creek regulator point in Cabell County.
The notice called for an immediate pressure reduction. Scheduled volumes on that segment were expected to fall. Research circulating among traders put the affected firm service near 1.8 million dekatherms per day, roughly in line with what had been scheduled through the constrained segment. For a line designed as a 2.7 billion cubic feet per day Appalachian takeaway route, that is not a rounding error. That is a hole in the map.
Flow restrictions can tighten downstream supplies even when gas remains abundant at producing wells.
That last point is the one people outside the business often miss. Appalachia can still be producing. Wells can still be open. And yet delivered gas in the Midwest, Mid-Atlantic, Southeast, and toward Gulf export corridors can still feel scarce if the pipe cannot move it. Takeaway is the word that matters here, not just production.
Why This Corridor Matters More Than It Looks
Mountaineer XPress is not a quiet local line. It is a southbound artery for Marcellus and Utica molecules. Once gas leaves the hills, it can feed the broader Columbia system and two very different kinds of demand.
- Regional markets tied to the TCO pool serving Midwest, Northeast, and Mid-Atlantic customers
- Southern markets reached through the Leach interconnection in Kentucky
- Downstream paths that can carry supply toward the Southeast and Louisiana export complex
In my experience, the second path is what makes a West Virginia mechanical issue a national price story. If gas cannot reach the southbound handoff, traders start asking whether Gulf-facing volumes will thin out just as the market is already sensitive to storage, weather, and export nominations.
Upstream receipts had not fully adjusted in the first hours. Flows at key receipt points were still moving, which is typical. Nominations lag. Tomorrow’s cycle is when the restriction starts to look real on paper. If roughly 1.8 billion cubic feet a day cannot find another path, someone has to reroute, cut production, or both.
The Price Reaction Was Fast For A Reason
October futures climbed about 4.5 percent in morning trade, adding more than thirteen cents to reach the mid-$3 range. From early Wednesday, the contract had already jumped more than 12 percent. That is not a gentle drift. That is the market pricing uncertainty about restoration.
I’ve found that natural gas is uniquely unforgiving about logistics. Crude can sit in tanks. Coal can sit in piles. Gas wants a pipe, a storage field, or a flare. When a high-capacity segment drops, the prompt contract does not wait for a press conference. It marks the risk immediately.
| Market Piece | What Changed | Why Traders Care |
| Firm service | About 1.8 MMDth/d affected | Contracted volumes may not flow |
| Constraint | Segment cut toward zero | No spare room on that path |
| Restoration | No firm timeline yet | Premium for uncertainty |
| October futures | Sharp morning rally | Prompt tightness risk |
Perhaps the most interesting aspect is how little physical scarcity you need at the wellhead to create financial scarcity at the citygate. The molecules exist. The path does not, at least not on this segment, not today.
Force Majeure Is A Legal Phrase With Market Teeth
People throw around force majeure as if it were just corporate language. In pipeline operations it is more than that. It is the operator saying an unexpected event prevents normal performance of firm obligations. Shippers who thought they had rock-solid capacity suddenly discover that “firm” has an exception clause.
That does not mean every customer loses the same amount. Priority, location, and alternative paths decide who feels the pinch. A utility with diverse receipts may shrug. A producer relying on that exact southbound slice may have to shut in or pay up for a workaround. Those workarounds, when they exist, show up as basis blowouts on nearby points.
I keep coming back to this: markets hate silence on duration. An outage with a three-day estimate is a headache. An outage with “update Friday morning” and no restoration window is a volatility machine. Traders will keep a bullish lean in the prompt contract until someone can prove the steel is healthy again.
Appalachia’s Old Problem In A New Week
Appalachian gas has always been a takeaway story. The basin can produce more than local pipes can comfortably carry on some days. That is why new compression, looping, and southbound projects were built in the first place. When one of those projects stumbles, the basin’s old bottleneck returns in miniature.
Think of it like a crowded highway with one tunnel closed. Traffic does not disappear. It piles up behind the closure and looks for side roads that were never designed for the extra load. Those side roads are other pipelines, storage injections if available, or production cuts if nothing else works.
- Confirm the exact segment and pressure limit
- Watch next-day nominations for real volume loss
- Track nearby basis for signs of trapped supply
- Look for production response if alternate paths fill up
- Reprice the prompt contract until a repair window is credible
That sequence is almost ritual. Anyone who has sat on a gas desk through a compressor failure knows the rhythm. Day one is the headline. Day two is the nomination print. Day three is when producers stop hoping and start making operational calls.
Who Feels This First
Not every region will feel the same squeeze. That is worth repeating because national headlines flatten local reality. A Mid-Atlantic citygate that can still pull from other laterals may see only a modest basis move. A southern path that counted on Leach volumes could look tighter, especially if weather or power burn rises at the same time.
Export-facing demand sits in the background of almost every modern gas story. Even if this outage never touches a single liquefaction train directly, traders still ask whether fewer Appalachian molecules heading south changes the balance at the Gulf. Sometimes the answer is no. Sometimes the answer is a few cargoes’ worth of tightness in the narrative, which is enough to keep the bid alive.
Power generators are the other quiet audience. Combined-cycle plants do not care about county names in West Virginia. They care about delivered price and reliability when the stack needs gas-fired megawatts. A sudden restriction is not a blackout by itself. It is one more reason the prompt curve stays nervous.
Why Futures Can Rally While Wells Keep Flowing
This is the paradox that still trips up casual observers. Production headlines can look fine. Rig counts can look fine. Storage can even look comfortable on a national print. And the front-month contract can still rip higher because the market is regional, hourly, and path-dependent.
I’ve seen weeks where the national surplus argument was technically correct and still useless for the next ten trading sessions. Location basis does the real work. If gas is cheap where it is stuck and expensive where it is needed, the Henry Hub contract can lean higher simply because the balancing point is no longer as easy to feed.
Simple gas math this week:
  Production still available
  Takeaway suddenly reduced
  Nominations not yet fully rerouted
  Prompt price pays the uncertainty premium
Is that premium justified for weeks? Maybe not. Is it justified overnight? Markets usually say yes. They would rather overpay for a day than get caught short if the mechanical issue is worse than the first notice implied.
What “Immediate Pressure Reduction” Really Signals
Operators do not cut pressure for fun. A mechanical issue on a high-pressure transmission line can mean integrity concerns, equipment risk, or a need to protect the remaining system. The public notice language is deliberately cautious. “Expected mechanical issue” is not a full engineering report. It is a warning flare.
Until inspectors finish their work, capacity stays conservative. That conservatism is why firm service can be slashed even if the pipe is not fully offline. Reduced pressure often means reduced throughput. Reduced throughput on a busy segment means someone loses a schedule.
In my view, the Friday morning update is the next real datapoint. Not the commentary. The operational note. If the operator restores even a slice of the constraint, the bullish impulse fades. If the restriction holds, the market will start treating this as more than a one-session scare.
How Shippers Try To Work Around A Closed Door
When a primary path dies, the scramble is unglamorous. Schedulers call other interconnects. Producers look at interruptible space that suddenly looks expensive. Marketers hunt for storage that can absorb stranded supply for a few days. None of that is free.
- Reroute through less efficient laterals if they have room
- Displace other volumes and pay the basis cost
- Inject into storage when the field and the ticket allow it
- Curtail production at the most constrained receipt points
Each option has a different pain profile. Rerouting costs money. Storage may already be booked. Curtailment costs future cash flow and can create lease or midstream friction. That is why a mechanical issue in two West Virginia counties can become a boardroom issue for producers hundreds of miles away.
Do I think every Mcf gets shut in tomorrow? No. Markets are adaptive. But adaptation is not instant, and the futures pit trades the lag.
Seasonal Context Makes The Timing Awkward
Late September is a shoulder month, which sounds calm until you remember what the calendar is about to do. Heating demand is not roaring yet. Storage injections still matter. Export schedules still matter. A surprise outage now is less dangerous than the same outage in a polar vortex. It is still poorly timed if inventories need every available molecule to stay on the comfortable side of winter.
Traders will overlay weather models on this outage by habit. A mild pattern would mute the story. An early cold snap in the Midwest or Mid-Atlantic would amplify it. That overlay is why a pipeline notice can keep influencing price even after the first headline is old.
I am not in the business of pretending one compressor corridor controls the entire winter. It does not. It can, however, change the starting line for October and November if repairs drag.
The Difference Between A Blip And A Bottleneck
Every outage wants to be called temporary. Some are. The market’s job is to decide which ones become structural for a week or two. Three questions usually settle that debate.
- Is the mechanical issue isolated equipment or a broader integrity problem?
- Can adjacent pipes absorb the displaced 1.8 Bcf/d without ugly basis?
- Do producers keep flowing into a shrinking exit or do they cut?
If the answers are isolated, yes, and keep flowing, this fades. If the answers are messy, no, and cut, the rally has legs. That is not poetry. That is how this market has worked for years.
The pipe is the product as much as the molecule is the product.
I like that way of putting it because it keeps the conversation honest. A cheap well with no exit is not cheap for long. A rich basin with a wounded artery is not long for a bearish narrative.
What Investors And Energy Watchers Should Track Next
If you are not sitting on a scheduling desk, you still have a short checklist. Watch the next operational update. Watch whether receipts at the big upstream points roll over. Watch whether October’s bid holds after the first burst of headlines. And watch basis, because basis is where the truth leaks first.
Equity investors sometimes treat a gas spike as a simple producer tailwind. It can be. It can also be a midstream reminder that infrastructure risk is not theoretical. A few days of lost throughput is a rounding item for a giant system. A prolonged restriction is a cash-flow and contract-credit conversation.
For households, this is not an overnight bill shock. Retail rates lag. The more honest near-term effect is wholesale volatility and a slightly less comfortable path into winter if other surprises stack on top of this one.
A Plain-Language Read On Risk
Let me put my own cards on the table. I do not see this single event as a structural bull case for years of $8 gas. That would be overselling a mechanical notice. I do see it as a clean example of why natural gas remains a logistics market dressed up as a commodity market.
Capacity is concentrated. Weather is lumpy. Export demand is now a permanent feature. When one high-volume Appalachian path stumbles, the prompt contract has every reason to jump first and ask questions later. That is not hysteria. That is how scarce exit capacity gets priced.
The human temptation is to wait for a tidy ending. Markets rarely offer one on day one. They offer a bid, a notice, and a Friday update. Between those points, the only honest stance is simple: treat restoration as unproven until the operator proves it.
The Broader Lesson For Energy Markets
Every few months the same lesson returns in a new county. Infrastructure is the hidden balance sheet of the gas market. You can cheer production growth all you want. If the steel, the compressors, and the regulators cannot move the gas, price will do the rationing.
That rationing shows up as higher futures, wider basis, and uncomfortable phone calls between producers and pipelines. It also shows up as a reminder that “abundant resource” and “abundant delivered supply” are not the same sentence.
I’ve found readers remember the price chart and forget the map. This week the map is the story. A line in West Virginia lost pressure. A constraint went to zero for a cycle. Firm service took a hit near 1.8 million dekatherms a day. October gas paid up. Until the next notice changes those facts, that is the market.
Will the restriction vanish as quickly as it appeared? Possibly. Mechanical issues sometimes do. Will traders give the all-clear before the pipe does? Unlikely. That gap between hope and hardware is where the extra cents in the October contract are living right now.
Keep an eye on nominations, restoration language, and whether Appalachian receipts finally flinch. If those three line up bearishly, the spike fades. If they do not, this little stretch of West Virginia pipe will keep punching above its weight in the national gas tape.
Success is walking from failure to failure with no loss of enthusiasm.


Russia Nato Attack Risk Rises After New Intelligence Warning

XRP Price Squeeze Near $1.60: What Comes Next
Related Articles

US Gun Violence: State-by-State Death Rates Revealed
Which US states have the highest gun death rates? From DC’s alarming stats to surprising lows, uncover the trends shaping this crisis...

How Nations Tackle the Iran Oil Crisis Shock
As oil prices skyrocket from the Iran conflict disrupting global supplies, nations impose drastic steps—from price ceilings and export bans to four-day weeks and stair-climbing mandates. But will these measures hold, or is a deeper economic storm brewing?...

Trump Administration’s Bold Move on Cannabis Reclassification
The Trump administration just announced a major move to reclassify cannabis, potentially opening doors for research and business. But is this the game changer everyone hopes for, or are there still hurdles ahead? Find out what it really means.