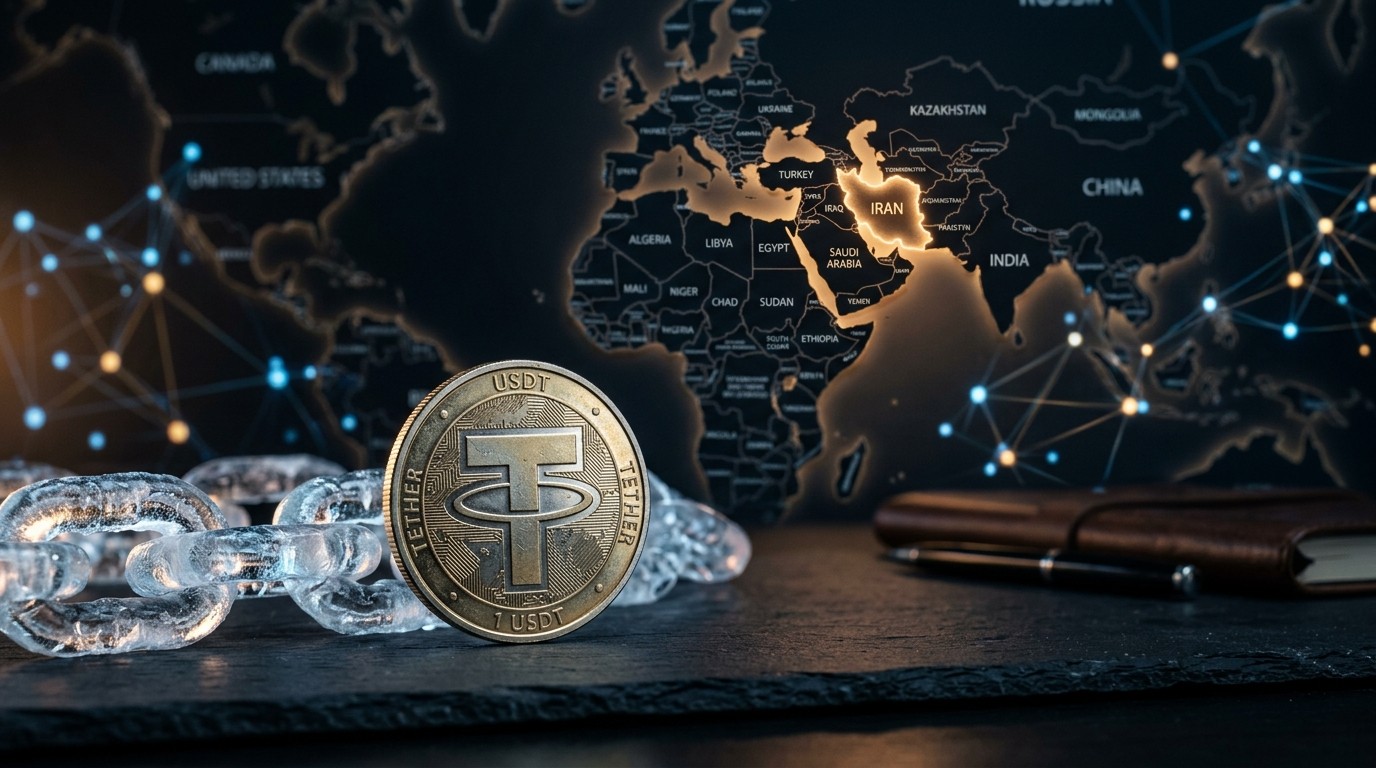

Have you ever watched a number that big land in a crypto headline and felt that mix of relief and unease at the same time? Nearly $550 million in Iran-linked USDT was frozen this year with help from the issuer, and the timing is not quiet. A Senate Democrat asked federal agencies to look harder at whether the world’s most used stablecoin became a convenient pipe around sanctions. I have covered this beat long enough to know that frozen tokens are never just a press release. They are a signal that the old story about “unstoppable money” is colliding with the older story about states that still want a kill switch.
What The Freeze Actually Means For USDT
Start with the facts as they were presented, then sit with them. The company said it has worked with international law enforcement for years. This year alone it froze more than $130 million in USDT across four wallets. In April it froze more than $344 million tied to the Central Bank of Iran. Add those pieces and you land close to that $550 million figure that is now traveling across market chats.
The CEO put it bluntly. USDT, in the company’s telling, is not a haven for sanctioned actors, terrorist organizations, or criminal networks. That is a strong claim. It is also the kind of claim you only make when someone else is already arguing the opposite.
Tether has consistently demonstrated that USDT is not a haven for sanctioned actors, terrorist organizations or criminal networks.
– Company chief executive
On the other side of the same news cycle, investigators on a Senate subcommittee released a report arguing that USDT had become a key channel for Iran to dodge restrictions. They looked at hundreds of wallets already tagged for Iran ties. The finding that stuck with me was the concentration: 84% of 846 sanctioned wallets had transacted exclusively or nearly exclusively in USDT. That is not a rounding error. That is a pattern.
In my experience, markets do not process patterns like that as moral lectures. They process them as operational risk. If a token can be frozen at scale, holders care about the freeze policy. If a token is hard to freeze, policymakers care about the leakage. You can dislike both instincts and still admit they are real.
The Public Record The Issuer Wants You To See
The company also put a larger number on the table. Cooperation with authorities worldwide, it said, has led to more than $4.9 billion in assets frozen. More than $2.4 billion of that was connected to U.S. authorities. Those are not small footnotes. They are an attempt to reframe the product as a tool that investigators can actually use.
The list of partners was long on purpose. Justice officials, the FBI, the Secret Service, homeland investigators, sanctions officers, and agencies abroad have, according to the issuer, worked with the firm to trace, freeze, and recover funds. The closing line was almost a mission statement: that capability will stay available to people trying to stop terrorism, sanctions evasion, fraud, and other serious crimes.
I find that framing interesting because it accepts a premise a lot of early crypto culture rejected. The premise is that a dollar-like token on a public chain is still, in practice, an administered asset. Someone can blacklist an address. Someone can refuse to honor a redemption. Someone can cooperate. That is not the same as cash in a suitcase, and pretending otherwise has always been a bit of theater.
Why Stablecoins Sit In The Crosshairs
A stablecoin that tracks the dollar is useful for the same reasons a checking account is useful. It is liquid. It is familiar. It moves fast. Traders park value in it between bets. Merchants in stressed economies reach for it when the local currency wobbles. Remittance desks like the settlement speed. None of that is mysterious.
The trouble starts when the same features that help a family move savings also help a sanctioned network move value. Speed does not check passports. Liquidity does not read a designation list. If most of the on-chain activity in a cluster of flagged wallets runs through one ticker, critics will say the ticker is the problem. Defenders will say the ticker is simply the ocean everyone swims in.
Both can be partly true. USDT is everywhere. Market share at that scale means any illicit flow that wants dollar exposure will bump into it. That does not automatically prove the issuer designed a sanctions tunnel. It does mean the issuer cannot hide behind rarity.
- High liquidity makes the token a default settlement rail.
- Global availability makes it hard to fence off one country cleanly.
- On-chain transparency helps tracers follow funds after the fact.
- Centralized issuance still allows address-level freezes.
That last point is the hinge. People sometimes talk as if crypto is either fully private or fully controlled. USDT lives in the messy middle. The ledger is public enough for analytics firms to map clusters. The issuer is centralized enough to interrupt those clusters. That combination is why law enforcement likes the phone number and why critics still ask whether the phone gets answered early enough.
The Senate Pressure Campaign
The political piece arrived on the same day as the company’s defense, which is rarely an accident. Democratic investigators published findings that treated USDT as a preferred channel for Iranian counterparties. A senator then asked Treasury and Justice officials to examine possible sanctions violations. That is not a casual letter. It is a request that can turn into subpoenas, licensing reviews, and years of process.
Perhaps the most interesting aspect is how the two narratives use the same raw material. Investigators look at sanctioned wallets and see a dominant token. The issuer looks at frozen balances and sees proof of cooperation. One side counts flows that already happened. The other side counts funds that can no longer move. Readers who only consume one version will think the other side is lying. Usually they are arguing about the clock.
Did the freezes happen after the damage? That is the unkind question every compliance team hates. Prevention is quieter than recovery. Recovery still matters. A $344 million freeze linked to a central bank is not a rounding error in anyone’s sanctions program. But if 84 percent of a sanctioned sample set was already living in one token, opponents will say the barn door was open for a long time.
How A Freeze Works In Plain Language
People new to this space imagine a SWAT team seizing coins from a hardware wallet. That is not the usual movie. For a centralized stablecoin, the more common move is an address blacklist. The smart contract or the issuer’s control keys stop those tokens from transferring through the official contract logic. The coins may still “sit” on an address. They just stop being useful as money inside the official system.
That is a blunt instrument. It can catch a cluster of wallets after analytics firms map them to a designated entity. It can also freeze funds that later turn out to belong to someone caught in the splash. I have found that the public conversation almost never spends enough time on false positives. Compliance people do. Traders do when they wake up and cannot move a balance.
Freeze path in practice:
  Flagged activity
  Analytics cluster
  Legal request or internal review
  Address-level restriction
  Follow-up recovery talks
Notice what is missing from that sketch: a global pause button for the whole token. That matters. Critics sometimes talk as if one scandal could halt the entire float. Issuers talk as if surgical freezes prove the system is already well policed. Reality sits between those posters. Surgical freezes are real. So is the lag between first transfer and first freeze.
Iran, Dollar Access, And The Incentive Map
You do not need a classified briefing to understand the incentive. When traditional correspondent banking is constrained, actors look for substitutes that still feel like dollars. A widely accepted stablecoin is one substitute. Hawala networks are another. Trade mis-invoicing is another. Oil-for-goods arrangements are another. Crypto did not invent evasion. It added a rail that is faster to audit after the fact and faster to use before the fact.
That duality is why this story will not end with one statement. If on-chain dollars are useful to households under inflation, they will keep spreading. If they are useful to designated institutions, governments will keep tightening the screws on issuers, exchanges, and on-ramps. The issuer’s bet is that being the helpful freeze partner is safer than being the distant protocol that shrugs.
I am not sure that bet is cheap. Helpfulness invites more requests. More requests invite more political ownership of the product. At some point a private treasury of tokenized dollars starts to look like a regulated utility that just happens to live on public chains. Some investors will like that. Some cypherpunks will hate it. Most users will only notice when a transfer fails.
What The Wallet Statistic Does And Does Not Prove
Eighty-four percent is a loud number. Loud numbers deserve careful handling. The sample was 846 wallets already sanctioned over Iran ties. That is a selected set, not a random draw of all USDT users. Inside a selected set of bad addresses, concentration in the most liquid dollar token is almost expected. If you studied sanctioned wallets in any other popular dollar instrument, you might also see crowding.
Still, expectation is not a free pass. If one product dominates illicit dollar crypto flows, policymakers will treat that product as systemically important for sanctions enforcement. Banks learned this lesson decades ago. Money transmitters learned it later. Stablecoin issuers are learning it now, in public, with market cap hanging off every sentence.
| Claim | What it highlights | What it leaves open |
| $550M frozen this year | Issuer can interrupt large balances | How early the interruption arrived |
| 84% USDT in sanctioned sample | Heavy concentration in one token | Whether the sample overstates typical use |
| $4.9B frozen over time | Long cooperation history | Share of flows that never get frozen |
| Central bank linked freeze | High-value institutional target | How the funds were accumulated first |
Look at that grid for a minute. Every cell can be true at once. That is why the debate feels stuck. People pick the cell that fits their tribe.
Traders, Treasuries, And The Confidence Question
If you hold USDT as dry powder, your first question is not geopolitical theory. It is whether your tokens will move on Monday. Address-level freezes do not freeze the whole supply. They do change the mood. A market that watches nine-figure freezes will price two risks at once: the risk that bad actors used the rail, and the risk that good actors get caught near a cluster.
I have sat with desk heads who treat issuer risk the way they treat bank counterparty risk. They ask who can halt a balance. They ask what law the issuer answers to. They ask how often freezes happen without a public court opinion attached. Those are adult questions. Anyone still treating a multi-billion dollar token as a toy is not doing the job.
There is a second, quieter market effect. When an issuer advertises cooperation, regulated exchanges feel safer listing the token. When a Senate shop advertises an investigation, compliance teams add review cycles. Listings do not vanish overnight. Friction rises in inches. Inches matter when you settle large books every day.
The Older Fight About Who Polices Digital Dollars
This episode sits inside a longer argument. Should a private firm that issues dollar tokens act like a bank, a software vendor, or a diplomat? Banks have know-your-customer rules baked into charters. Software vendors ship code and claim they do not police speech or money. Diplomats negotiate exceptions. Stablecoin issuers keep borrowing language from all three jobs.
When they freeze funds they sound like banks. When they talk about blockchain rails they sound like vendors. When they list agencies they have helped they sound like partners of state. That hybrid is efficient until a scandal forces a single identity. Investigations are how political systems force a single identity.
The record is public: authorities around the world have repeatedly worked with the issuer to trace, freeze and recover assets.
Public records cut both ways. They show capability. They also show that capability is discretionary. Discretion is exactly what critics want written into law and what some founders wanted to keep informal. Informal systems scale until they do not.
Sanctions Policy Is Not A Crypto Subculture
It helps to step out of token twitter for a second. Sanctions are a foreign policy tool. They are blunt. They create gray markets. They also remain one of the main non-military levers large states use. If a digital dollar product becomes a visible leak in that lever, the product will be treated as a national security object, not a fintech novelty.
That shift changes the vocabulary. You stop hearing only about pegs and reserves. You start hearing about beneficial owners, correspondent exposure, and secondary sanctions risk for exchanges that touch the token. The technical white paper becomes less important than the org chart and the jurisdiction of the operating entities.
Is that fair to builders who wanted open settlement? Fair is the wrong measuring stick in this room. Policy is about leverage. A token that claims dollar equivalence is inviting dollar-state attention. That invitation was always in the product design.
What “Helped Freeze” Does Not Tell You
Language in these statements is careful. “Helped freeze” can mean the issuer initiated a review after analytics flagged a cluster. It can mean an agency arrived with a packet and the issuer executed. It can mean a mix. Outsiders rarely get the chronology. Chronology is the whole ballgame if you are trying to judge negligence versus partnership.
- Identify whether the wallets were already designated.
- Identify when the first large inflows arrived.
- Identify when the freeze landed relative to those inflows.
- Identify whether counterparties on the other side were ordinary users.
- Identify what share of similar clusters remains unfrozen.
Without those five points, both applause and outrage are premature. I would rather sound boring than certain. Certainty is cheap on deadline. It ages badly.
Users In Ordinary Countries Feel This Too
It is easy to write this as a story about Tehran and Washington. Plenty of readers holding USDT live in places that are not on any sanctions list. They use the token because local banks are slow, because brokers demand it, or because payroll arrives that way. Their risk is collateral. A political fight over high-profile wallets can tighten withdrawal rules for everyone.
That is the part I wish more commentary admitted. Compliance upgrades are not laser-guided. Exchanges raise limits, request more documents, delay payouts, and delist pairs in bursts. A family trying to keep savings in something stable does not experience those bursts as justice. They experience them as friction.
So yes, freeze large designated piles. Also be honest that the plumbing changes around those freezes. Honesty travels farther than slogans about either freedom or security.
Reserve Stories And Trust Stories Travel Together
Every major USDT controversy eventually loops back to the same two files: what backs the token, and who can stop the token. This week is mostly the second file. Do not pretend the first file is unrelated. If users believe redemptions are sound, they tolerate more governance. If they doubt the cash and paper behind the peg, every freeze looks like a prelude to a wider lock.
I have found that sophisticated holders separate those files on a spreadsheet and merge them in the gut. Spreadsheets say the freeze of someone else’s wallet does not change your reserve claim. Guts say an issuer that can freeze can also hesitate. Markets price guts more than we like to admit.
Competition Waiting In The Wings
Whenever the leading dollar token is in the dock, rivals clear their throats. Some will pitch tighter banking relationships. Some will pitch more transparent attestations. Some will pitch more aggressive blacklisting as a feature. A few will pitch the opposite: less ability to freeze, more protocol neutrality. Each pitch has a customer.
The customer that matters in the next two years may not be the retail trader. It may be the exchange, the market maker, the payment firm, and the legislator. Those four groups decide distribution. Distribution decides whether a token remains the default.
Does that mean USDT is about to lose the crown because of one report and one defensive statement? No. Crowns in this market move slowly until they move all at once. The useful stance is watchful, not theatrical.
A Note On Rhetoric And Reality
Company statements like to say a token is not a haven. Investigators like to say a token is a channel. Haven is a moral word. Channel is a plumbing word. Plumbing is closer to how money actually moves. Water finds the widest pipe. If USDT is the widest on-chain dollar pipe, water will be there, clean and dirty.
The adult response is not to deny the width of the pipe. It is to instrument the pipe, log the flow, and shut specific valves when the law requires it. That is less romantic than early manifesto culture. It is also closer to how every successful monetary network has grown up.
Romance still has a constituency. I get it. Censorship resistance is not a silly idea. It is an incomplete product description when the product is a claim on dollars administered by a company that wants to keep banking partners. Incomplete product descriptions cause surprise. Surprise causes hearings.
What To Watch After The Headlines Fade
The next chapter will not be another round number. It will be process. Watch whether Treasury or Justice staff treat the request as a speech or as a case. Watch whether more wallet clusters get named. Watch whether the issuer publishes more detailed freeze statistics by category rather than a single grand total. Watch whether exchanges change deposit screening in ways that show up in user complaints before they show up in official memos.
Also watch the quieter technical work. Analytics vendors will keep selling graphs of Iran-linked clusters. Compliance suites will keep adding stablecoin modules. Legislators will keep drafting bills that treat issuers more like banks. None of that is cinematic. All of it is how this industry actually changes.
If you trade, size issuer-risk the way you size venue-risk. If you build, assume that dollar tokens will face more requests, not fewer. If you just use the token to move value across a weekend, keep records and avoid addresses that look like puzzles. That last line is not legal advice. It is hygiene.
A Longer View On Trust In Administered Crypto
We are ten-plus years into the experiment of putting dollars on public ledgers without putting the whole banking stack on those ledgers. The result is a hybrid that keeps surprising people who wanted a clean ending. The ledger is open. The liability is not. The transfer is fast. The permission can still be withdrawn.
That hybrid can still be valuable. Speed plus a familiar unit of account is a genuine product. Recovery tools for stolen or designated funds are a genuine product. The collision comes when one audience buys the token for the first feature and another audience regulates it for the second.
This year’s freezes, the April action tied to a central bank, and the Senate report are all scenes in that collision. I do not think the collision ends with a villain monologue. I think it ends with thicker rulebooks and a market that keeps using the token anyway until a better default appears.
Maybe that sounds cynical. I would call it empirical. Tools that clear and settle at this scale rarely disappear because a hearing was spicy. They get wrapped in more process. Process is the tax you pay for looking like money.
Closing The Loop Without Fake Certainty
So where does that leave a reader who is not on a subcommittee and not on an issuer payroll? You now know the company says it helped lock down close to $550 million in Iran-linked USDT this year, including a very large April action and a set of four wallets north of $130 million. You know the same week brought a report about USDT dominance inside a sanctioned wallet sample and a call for a federal look. You know the issuer points to billions frozen over a longer horizon with U.S. agencies in the mix.
You do not know, from public statements alone, the full timeline of every flow. You do not know how an investigation would end. You do not know whether market share will blink. Anyone selling you those answers today is selling comfort.
What you can hold onto is simpler. Dollar tokens with an issuer are freezeable. Freezeable assets will be asked to prove usefulness to states. States will keep asking. The companies that survive that asking will look less like manifesto projects and more like financial utilities that happen to post balances on-chain. That may disappoint some of us. It may also be the only way a token this large stays in the legal daylight.
I keep coming back to that first feeling, the mix of relief and unease. Relief that large designated piles can be stopped. Unease that the stop button lives in a conference room. If you can sit with both feelings at once, you are closer to how this market actually works than any slogan on either side.