

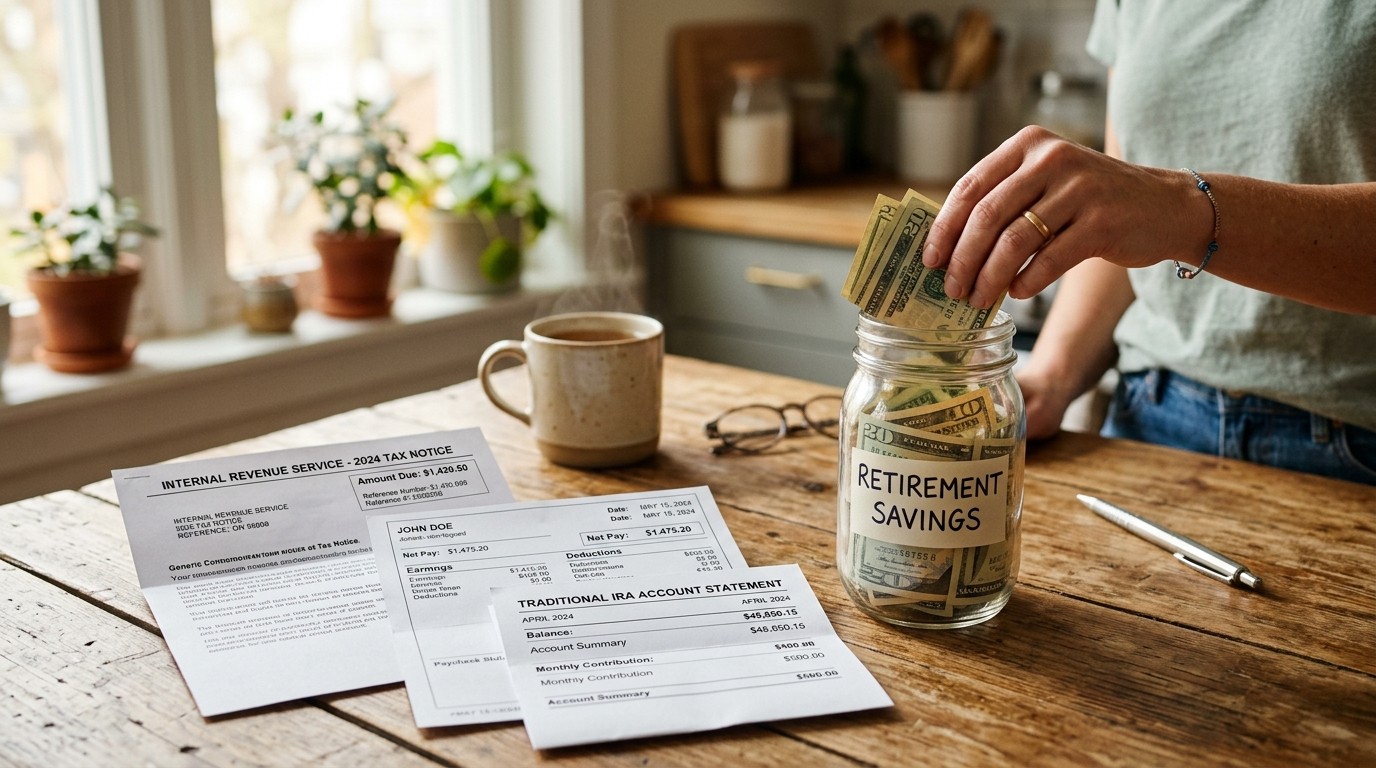
IRS Saver’s Match Notices For New Retirement Benefits

The IRS just mailed notices about a retirement match that can add up to $2,000. The old saver's credit is fading, and the fine print on Roth accounts may surprise you before 2027.
Financial market analysis from 29/09/2026. Market conditions may have changed since publication.
I keep a small stack of tax mail on the corner of my desk for a week before I open it. Most of it is noise. Every so often something lands that actually changes how a household should save. That is the feeling around the new Saver’s Match notices. If you claimed the old saver’s credit last year, or if your 2025 income sat in the eligible range, you may already have a letter in the pile. The program itself does not pay out until the 2027 tax year. Still, the timing of the notice is the point. People who wait until April 2028 to learn the rules will leave money on the table.
What The IRS Notice Is Really Telling You
The agency has started sending CP321J notices to taxpayers who look like future candidates for the match. In plain English, the letter is an early warning, not a check. It flags people who used the current saver’s credit on a 2025 return, plus others whose income would have fit the coming brackets. How many letters went out is still unclear. That vagueness is annoying, and I will say it out loud: a public count would help employers and advisors prepare. Until that number appears, treat the notice as a personal checklist, not a guarantee.
The match was written into the 2022 Secure 2.0 retirement package. It replaces a credit that never quite lived up to the brochure. Beginning with tax year 2027, income-eligible savers can receive a government matching contribution of up to $1,000 for a single filer and $2,000 for joint filers. You claim it later, when you file the 2027 return in 2028, on a new form labeled 8880-A. Until then, the familiar saver’s credit stays in place through tax year 2026.
Why The Old Credit Fell Short For Many Households
The saver’s credit looks generous on paper. Same headline amounts: up to $1,000 single, $2,000 joint, tied to retirement contributions and income. The catch is structural. It is a nonrefundable credit. It can shrink a tax bill to zero. It cannot create a refund. Lower-income households, the very group the credit was meant to help, often owe little or nothing. A credit that only offsets tax you do not owe is a polite shrug.
A match deposited into an account is more useful than a credit that disappears when your tax bill is already small.
Awareness was another problem. Plenty of eligible filers never heard of the credit, never saw it on software screens they actually understood, and never planned contributions around it. Researchers who study household finance have said for years that the credit never reached tax filers at scale. I tend to agree. Benefits that require extra forms and extra knowledge quietly fail the people with the least spare time.
The Saver’s Match tries to fix that design. Instead of trimming a tax line, the government would send a matching amount into a retirement account. That is a different psychological object. Money that shows up in a balance feels earned. Money that only reduces a bill you barely have feels theoretical. If you have ever watched someone ignore a tax credit and then get excited about a workplace match, you already understand the difference.
Who Can Qualify Once The Match Begins
Eligibility is narrower than a slogan and wider than a rumor. Single filers with modified adjusted gross income up to $20,500 can receive a full 50 percent match on qualifying contributions, with the contribution slice capped so the yearly match maxes at $1,000. Joint filers can go up to $41,000 for the full match, with a $2,000 household ceiling. Above those floors, a phase-out begins. Singles between $20,501 and $35,499, and joint filers between $41,001 and $70,999, can still get a reduced match.
Age and status matter too. You generally need to be at least 18, not a student, not someone else’s dependent, and a U.S. resident for tax purposes. You also have to make a qualifying retirement contribution. No contribution, no match. That last point sounds obvious. It is the one people forget when they treat the program like a stimulus check.
| Filing status | Full-match income range | Reduced-match range | Maximum yearly match |
| Single | Up to $20,500 | $20,501 to $35,499 | $1,000 |
| Joint | Up to $41,000 | $41,001 to $70,999 | $2,000 |
Those income figures will need watching. Tax brackets and program thresholds often move with inflation in later years. Treat the numbers above as the current published frame, not a forever law of physics. If your income sits near a cutoff, a bonus, overtime, or a second job can flip you from full match to partial match in a single season. That is not a reason to refuse extra pay. It is a reason to plan contributions earlier in the year instead of in a March panic.
Workplace Plans And IRAs Both Count, With A Twist
The match is available whether you save in a workplace plan such as a 401(k) or in an individual retirement account. That flexibility is one of the better parts of the design. Tens of millions of private-sector workers still lack an employer plan. Estimates around 53.7 million full-time and part-time workers between 18 and 65 have no workplace retirement option. For that group, an IRA is not a luxury product. It is the only door.
Here is the twist that will confuse people. Roth IRA contributions can help you qualify, but a Roth account generally cannot receive the match. If you only own a Roth, the match needs somewhere traditional to land. Workers in state auto-IRA programs often sit in Roth-style accounts by default. They may need a traditional account in the mix, or they may wait for regulators to bless a workaround.
Agencies have floated a conduit traditional IRA. The match would arrive there, then move to a Roth. That move is a taxable conversion. I do not love extra steps that create a tax event for people who were trying to do something simple. Public comments on the August notice run through early October. If you work with savers in this income band, that comment window is not academic. It is the last cheap chance to argue for less friction.
The Messy Middle: Providers Do Not Have To Take The Money
Even a well-designed match fails if nobody will accept the deposit. Workplace plans and IRA providers are not required to take Saver’s Match dollars directly. A trade group survey of plan sponsors found almost no firm ready to say yes. Out of 125 responses, three said they will accept the federal matches. Forty-five said they are considering it. Fifty-seven said no. Twenty admitted they barely knew the program existed.
Some of the no votes make sense on paper. Higher-wage workforces will not have many eligible employees. Administrative cost is real. Recordkeepers hate one-off government deposits that do not fit their existing file layouts. I still find the early refusal rate uncomfortable. If the match can only live in a narrow set of IRAs, the people who save only at work will get a brochure and no deposit.
A comparison site for IRAs is expected in early 2027 so workers can shop accounts and, if eligible, collect the match when it is distributed. A public portal can help. It cannot replace payroll simplicity. The best version of this program would let a small contribution at work trigger a match that lands in the same plan without a scavenger hunt.
How To Think About The Match If You Got The Letter
Do not treat the notice as a prize ticket. Treat it as a calendar reminder. Through tax year 2026 you can still use the old credit. If you owe tax and you are contributing, that credit may still be worth claiming. Starting with 2027 activity, the match becomes the main event. The practical question is whether you can put enough into a qualifying account to earn a meaningful match without wrecking next month’s rent.
- Confirm that your 2025 income and filing status actually sit near the published ranges.
- List every retirement account you already have, including workplace plans and IRAs.
- Note whether those accounts are traditional, Roth, or a mix.
- Ask your plan administrator, in writing, whether they intend to accept match deposits.
- If the answer is no, open a traditional IRA with a provider that is likely to participate.
- Set a contribution habit now, even if the first dollars are small.
Small and automatic beats heroic and late. A 50 percent match on the first slice of savings is a rare deal. You do not need to max a plan to benefit. You need a contribution that exists, is documented, and sits in an account that can receive the government side. I have found that people do better when they pick a monthly number they can survive in a bad month, then raise it after a raise, not before.
A Walk Through The Math Without The Fog
Suppose a single filer earns $19,000 in modified adjusted gross income and puts $2,000 into a qualifying account. A 50 percent match on that $2,000 is $1,000, which is also the cap. The household did not need a perfect year. It needed two thousand dollars of contributions and an eligible income. If that same person could only save $800, the match would be $400. Still useful. Not magic.
Now change the income. A single filer at $28,000 sits in the reduced-match band. The percentage falls. The exact reduced formula will live in the final regulations, so I will not pretend I have a pocket calculator for every dollar in the phase-out. The principle is enough for planning: the closer you are to the top of the reduced band, the thinner the match. If you expect a raise that will push you out entirely, accelerating contributions while you are still inside the window can matter more than waiting for a prettier paycheck.
Joint filers should run the household number, not two solo daydreams. One spouse in a workplace plan and one spouse with only a Roth IRA can still qualify as a couple, then stumble on the receiving-account problem. Talk before tax season. The match is claimed on a return. The deposit has to land somewhere specific. Those are two different chores.
Students, Dependents, And Other Easy Disqualifiers
The age-18 rule is simple. The student and dependent rules are where families get sloppy. A young adult who is claimed as a dependent on a parent’s return generally will not qualify, even if that young adult earned wages and stuffed money into an IRA. A full-time student status can also block the match. If your household is in that gray zone, the notice in the mailbox may be informational rather than actionable.
Residency for tax purposes is another quiet filter. People with complicated cross-border years should not assume a letter equals eligibility. The match is a tax-administered benefit. If your filing posture is messy, fix the posture first. Chasing a match on a return that later gets adjusted is a headache you do not need.
What Regulations Still Have To Settle
The Treasury and the tax agency have said they will issue rules for how the match operates. That sounds dull until you list the open questions. Which account types can receive deposits. How a conduit IRA would work. Whether a conversion from that conduit to a Roth creates withholding surprises. How providers confirm identity. How quickly money moves after a return is processed. How errors get corrected if a taxpayer overstated contributions.
Comment letters through early October are the public’s chance to push for simplicity. I care less about elegant legal theory than about the number of boxes a tired filer has to check. The simpler the claim form, the higher the take-up. The more account types that can accept the money, the fewer people get a match they cannot house. Policy people talk about architecture. Households experience architecture as a Saturday afternoon on hold.
From tax forms to account types to the tax treatment of the deposit, the details will decide whether this help actually arrives.
– Economic policy analyst
How This Fits A Broader Retirement Gap
The United States still runs a split system. Some workers get automatic enrollment, an employer match, and a clean website. Others get a part-time schedule, no plan, and a polite suggestion to open an IRA when they have time. The Saver’s Match is an attempt to put a government thumb on the second group. It will not close the entire gap. A $1,000 annual match does not replace decades of missed compounding. It can still change the first decade for someone who starts with almost nothing.
Perhaps the most interesting aspect is behavioral, not statutory. A visible deposit teaches a habit. The first time a balance jumps because you saved, the next contribution feels less like a sacrifice. That is why I would rather see a smaller match that actually lands than a larger theoretical credit that never shows up in a statement. Statements educate. Credits hide inside software.
Employers who serve lower-wage teams should pay attention even if they do not love extra compliance. If a plan refuses the match and a nearby IRA accepts it, workers will split balances. Split balances are easier to cash out, easier to forget, and harder to roll later. Plan design that blocks the match may protect the recordkeeper and quietly harm the participant. That tradeoff deserves a board conversation, not a shrug in a survey box.
Practical Moves Before 2027 Without Overthinking It
You do not need a 40-page spreadsheet. You need a clean picture of income, accounts, and cash flow. Start with last year’s return. Find modified adjusted gross income. Compare it with the ranges above. If you are far above the reduced band, the notice may simply be a courtesy based on an older year. If you are inside or near the band, build a contribution path that you can keep during a lean month.
- Keep using the saver’s credit for 2026 if you still owe tax and you contribute.
- Open or confirm a traditional account that can receive a future match.
- Turn on automatic transfers on payday, not on the first of the month when rent hits.
- Save plan-provider emails about match acceptance in a folder you can find.
- Revisit income in late 2026 so a raise does not ambush your 2027 planning.
If money is tight, protect the emergency stash first. A match is not a reason to empty the only cash that keeps the lights on. Retirement compounds. So do overdraft fees. The households this program targets cannot afford a strategy that looks smart in a slide deck and cruel in a checking account.
Common Mix-Ups I Expect To Hear All Year
People will confuse the notice with a payment. It is not a payment. People will assume Roth is always better and then discover the match cannot live there. People will think a workplace plan automatically accepts the deposit because the plan already accepts employee deferrals. Different pipes. People will wait until they file in 2028 to open an account, then wonder why the money has nowhere to go.
Another mix-up: treating the match like an employer match you can get without contributing. The government side is a match. Your contribution is the spark. No spark, no fire. If your budget only allows $20 a month, start there. Twenty dollars a month is $240 a year. A 50 percent match on that slice is $120. Not a headline. Still a start, and starts are how balances begin.
What Advisors And Payroll Teams Should Do Now
If you advise clients in this income range, put the notice on the autumn agenda. Map accounts. Flag Roth-only savers. Draft a one-page explainer in ordinary language. If you run payroll or benefits, ask your recordkeeper for a written position on accepting deposits. “We are watching the regulations” is not a position. It is a stall. A stall through 2026 becomes a scramble in 2027.
Training matters more than a glossy flyer. Front-line HR staff will get the first confused emails. Give them a script that covers income bands, the Roth receiving problem, and the fact that the old credit still exists for one more full tax year. Confused staff create abandoned enrollments. Clear staff create contributions.
A Note On Fairness And Take-Up
Benefits that require perfect paperwork tend to flow toward people who already have help. That is the quiet risk here. A filer with software, an advisor, and a cooperative IRA will claim the match. A filer with two jobs and a broken scanner may not. The notice campaign is an attempt to shrink that gap. Notices only work if the later steps stay short.
I would rather see the final rules bias toward inclusion. Accept more account types. Keep the form short. Make error correction boring and fast. If the program becomes a maze, we will spend 2029 writing postmortems about low participation and calling it a mystery. It will not be a mystery. It will be design.
The Bottom Line If Your Letter Already Arrived
Open it. Check the year it references. Compare your latest income with the published ranges. Keep saving under the current credit through 2026 if it helps your bill. Build a traditional landing spot before 2027. Do not wait for a perfect regulation package. Perfect rarely shows up on schedule. Ready accounts do.
The Saver’s Match will not make anyone rich in a single year. That was never the job. The job is to put a real deposit next to a real contribution for people who have been offered slogans instead of balances. If the rules stay clumsy, the program will underperform. If the rules stay human, a modest match can become the first line on a statement that finally moves. That is the part worth preparing for, long before the 2028 filing season turns the notice into a missed chance.
Money is a good servant but a bad master.


Related Articles

Wealthy Donors Eye Double Tax Win With Stock Gifts to Trump Accounts
Rich donors could soon unlock a powerful double tax break by gifting appreciated stocks into children's Trump Accounts. What does this mean for philanthropy, taxes, and the future of these kid-focused investment vehicles? The details might surprise you...

Trump Accounts for Kids: Eligibility, $1000 Deposit and How to Get Started
With Trump Accounts now live, every parent has a chance to secure their child's financial future with a $1,000 government boost and tax-deferred growth. But who actually qualifies and how do you maximize the benefits before the deadlines hit?
AI Jobs Platform: Revolutionizing Career Connections
AI is reshaping how we find jobs with smarter platforms and certifications. Could this be the future of your career? Click to find out more!