

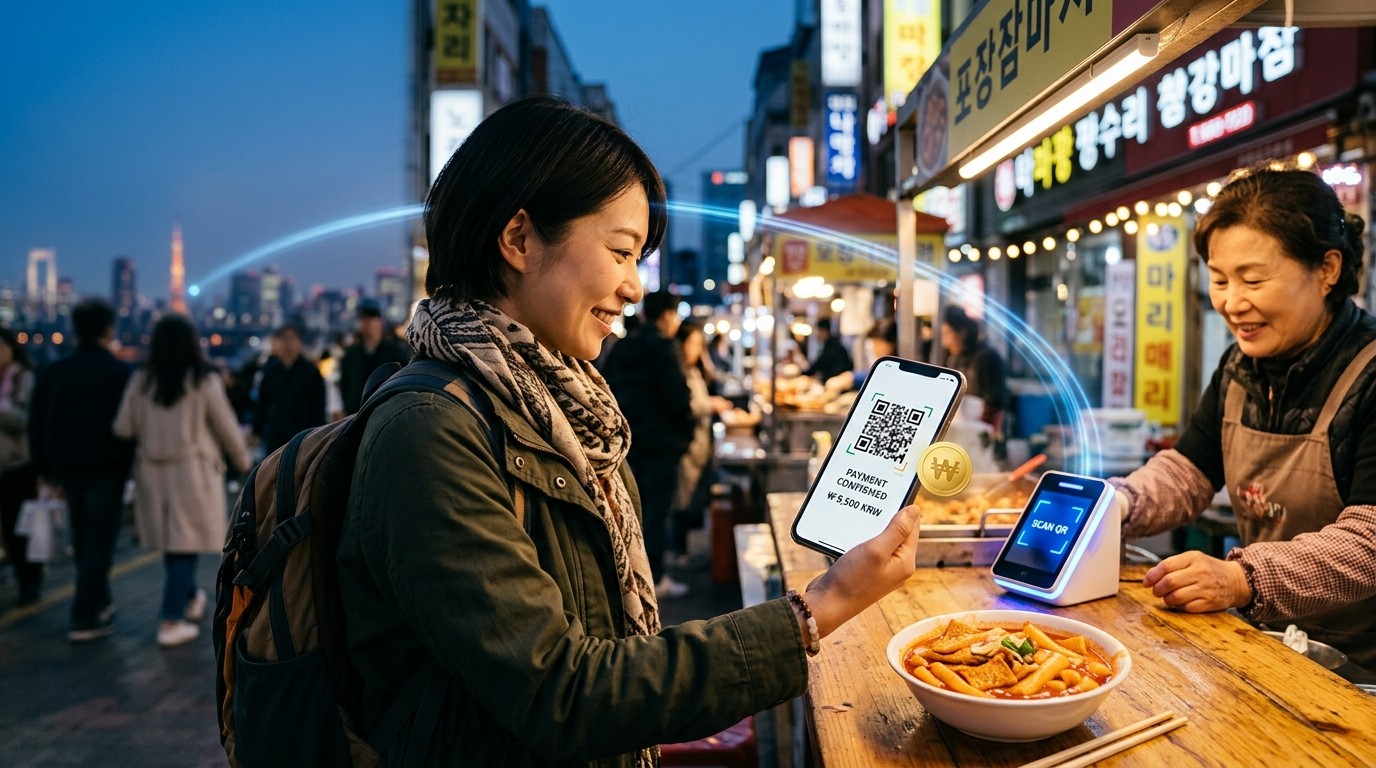

Picture this. You step off a flight in Seoul, the evening air smells like grilled meat and rain, and the stall you want does not take the card in your wallet. You could hunt for a currency exchange, pay a spread you cannot see, and walk away with notes you will not finish. Or you could scan a code and let a token pegged to cash do the boring part. That second picture is what a group of Japanese and Korean firms has started poking at, and I keep coming back to it because travel payments are where grand blockchain talk either becomes a receipt or stays a slide.
On the first day of October 2026, the SBI Group said its digital-trust arm had begun a joint verification with NICE Information and Telecommunication and the blockchain firm DSRV. The scenario is narrow on purpose. A Japanese traveler pays a NICE-affiliated merchant in South Korea by scanning a QR code. Money has to move from the customer side to the shop. Instructions have to be clear. Systems have to talk. The three companies want that homework finished by the end of December 2026. They have not promised a public product after that. They have not even named the coin.
Perhaps the most interesting aspect is how ordinary the ambition sounds. Not a new exchange. Not a loyalty app with a token sticker on it. A checkout. If you have ever stood in a queue while a terminal blinks and a clerk shrugs, you already know why that framing matters.
A Travel Checkout, Not Another Wallet Demo
Most cross-border crypto pilots I have watched stop at the moment two test wallets swap a balance. Useful for engineers. Useless for the person holding a paper tray of food. This verification is being described as a practical flow. The Japanese side designs the payment structure and keeps an eye on cooperation with other businesses inside the same group. The Korean payment processor brings merchant operations and existing rails. DSRV looks at the blockchain architecture that would have to sit under settlement without breaking the shop’s day.
The memorandum was signed at NICE headquarters in Seoul on 30 September. The public note followed a day later. That sequence is small, but it tells you the work is not a press-release first draft. Someone sat in a room, agreed a scope, and only then talked about it.
A payment product is not real until a merchant can explain it to a tired cashier in one sentence.
A payments operator I trust more than any white paper
I have found that pilots die in the gap between that sentence and the architecture diagram. The partners say they will study fund movement, payment instructions, system connections, transaction size, cost, and whether a commercial case exists at all. That last item is the honest one. December is a testing deadline, not a launch party.
Who Holds Which Piece of the Puzzle
SBI DigiTrust sits on the Japanese regulatory, financial, and digital-asset side. It is a blockchain infrastructure provider inside a group that already runs remittance, brokerage, and digital-asset businesses. That matters because a tourist payment is never only a tourist payment. Someone has to hold client money, someone has to satisfy registration rules, and someone has to decide what happens when a refund is due at 11 p.m.
NICE is the merchant door. The announcement cites a network of roughly 1.2 million merchants across South Korea. Read that carefully. The verification uses affiliated merchants as the setting. Nobody has said every one of those locations will switch on a stablecoin button. A large network is a laboratory, not a promise of nationwide coverage on day one.
DSRV takes the technical brief. System design. What a stablecoin would need to do. How a chain talks to systems that already clear card and QR volume. If you have built anything that touches a live till, you know the unglamorous part is reconciliation, timeouts, and the duplicate scan that posts twice.
- SBI DigiTrust shapes the Japanese structure and looks across sister businesses for cooperation.
- NICE tests merchant operations, links to current payment systems, and the business case.
- DSRV studies architecture, token requirements, and the join between chain and legacy rails.
- All three review cost, scale, and the issues that would block a later commercial service.
That split is cleaner than many consortia I have seen. Still, clean on paper is not clean in production. A refund path that works in a lab can fall over when the shop’s batch closes and the traveler is already on the train back to the airport.
What the Scan Is Supposed to Prove
Strip the jargon and the test is asking a handful of blunt questions. Can a Japanese customer start a payment that a Korean merchant recognizes as paid? Can the instruction set survive the hop between companies? Can the cost stay inside a range a shop would accept for a small ticket, not only for a wholesale transfer? And can anyone explain the failure mode when the phone loses signal halfway through the scan?
Tourist spend is awkward money. Tickets are small. Volume is bursty. Chargebacks, or whatever the stablecoin equivalent becomes, have to be faster than a postcard. If the unit economics only work above a few hundred dollars, the street-food story collapses and you are left with a remittance product wearing a QR costume.
In my experience, teams underestimate the instruction layer. Everyone obsesses over the token. The shop cares about the message that says paid, the amount, the reference, and the time. Get that wrong and the blockchain part is irrelevant.
The Details Nobody Has Named Yet
Here is the part that should slow the headline writers down. The partners have not named the stablecoin. They have not named the chain. They have not named a wallet provider, an exchange-rate method, or a settlement currency. There is no commercial launch date. That is not a minor footnote. It is the entire product.
A dollar-pegged coin, a yen-linked instrument, and a won-linked instrument would each drag a different licensing story, a different FX exposure, and a different conversation with a merchant who prices in won. Until that choice is public, any claim that travelers will “pay in stablecoins” is a sketch, not a route.
I would rather they stay quiet than invent a ticker for the sake of a chart. Silence is frustrating. It is also a sign the verification is still a verification.
| Question | What is public | What is still open |
| Who is testing | SBI DigiTrust, NICE, DSRV | Which other group units join later |
| Use case | Japanese traveler, Korean QR merchant | Remittance-only flows, refunds, offline fallback |
| Merchant reach | About 1.2 million in the NICE network | How many sites actually sit in the test |
| Asset | A stablecoin, unnamed | Peg, issuer, chain, wallet, FX method |
| Clock | Verification targeted for end of December 2026 | Any commercial go-live |
Treat that table as a boundary, not a teaser. Anything outside the middle column is commentary, including mine.
Why Japan and Korea Are a Sharp Test Bed
The corridor is short, busy, and already full of payment habits. Flights are frequent. Weekend trips are normal. Card acceptance is high in cities, patchier in the places people actually wander. QR codes are not exotic in Korea. Japanese travelers already juggle IC cards, credit cards, and cash. Adding a token only wins if it removes a step, not if it adds an app, a seed phrase, and a customer-support number in another language.
There is also a political texture that product teams prefer to skip. Two advanced economies, two currencies, two regulators moving at different speeds. A pilot that survives that mismatch has a better claim to be infrastructure than a pilot that only works inside one sandbox.
Would I use it on a Saturday night in Hongdae if the fee were obvious and the refund worked? Maybe. Would I use it if I had to pre-fund a strange wallet and pray the peg held through dinner? No. That is the bar, and it is not a high one. It is just rarely cleared.
Regulation Is Not a Side Note Here
Japan already treats fiat-linked stablecoins as electronic payment instruments. Businesses that handle those services need the relevant registration under the payment-services framework. On 1 June 2026 the country also brought in a registration path for intermediaries that sit between customers and registered providers for certain stablecoin and crypto services. That date is easy to glaze over. It changes who is allowed to stand in the middle of a tourist flow.
South Korea is earlier in the won-linked debate. The announcement itself says the Korean framework is still being built and that the partners will keep watching policy while the test runs. The central bank has been studying digital payments, tokenized deposits, and central-bank digital currency plumbing, and it has been in the room for the won-stablecoin argument. Research is not a license. It does mean the test is happening beside an unfinished rulebook, not after one.
Two clocks, then. Japan’s rules are usable enough to design against. Korea’s are moving. A December report that ignores the second clock would be decorative.
Build the payment as if the stricter rule will win, because the stricter rule usually does.
I am not a lawyer, and this is not advice. It is a pattern. Cross-border products that assume the looser regime will “catch up” tend to spend the following year rewriting contracts. The partners have at least said they will keep reviewing policy changes. That sentence is worth more than a roadmap graphic.
A Corridor Already Full of Experiments
This NICE and DSRV work is not the group’s first look at Japan-Korea stablecoin routes. In August, a separate effort began with the Korean infrastructure firm Nodeinfra, using the Canton network to examine payment tokens and, later, regulated stablecoin settlement between institutions. Different counterparty. Different shape. Institutional pipes rather than a tourist till.
September brought another test. Kyobo Life and SBI ran a yen-won stablecoin payment pilot aimed at exchanging representations of the two currencies without routing the settlement through the dollar. That run covered transfer, foreign exchange, settlement, tracking, and reconciliation. No institutional funds moved. No production date was announced. Again, Canton sat underneath.
Elsewhere in the group, the remittance arm has worked with Fasset on cross-border stablecoin infrastructure for remittances, payment services, and settlement across markets. Inside Japan, a dollar-backed stablecoin, RLUSD, reached local customers in June through a licensed distributor after the required approval, via the group’s VC Trade business and Ripple. None of those facts means the tourist QR test will use the same coin or the same chain. They do mean the group is not starting from a blank whiteboard.
Stacking pilots can look like momentum. It can also look like a company trying several doors because it does not yet know which one opens onto a business. Both readings can be true at once. I lean toward the second until a merchant settlement report shows up with fees, failure rates, and a named asset.
How a Traveler Payment Actually Has to Behave
Let me walk the flow the way a slightly impatient person would. You land. You want the payment method already on your phone, or one download that does not demand a seminar. You see a code. You confirm an amount in a currency you understand. The shop sees paid. You get a receipt you could show a friend. If the skewer was wrong, the refund does not require a ticket number from a chain explorer.
Every extra screen is a tax. Every new account is a reason to pull out a card instead. Stablecoin advocates like to talk about finality. Travelers talk about whether the clerk nods. Those are related, not identical.
- Identify the payer without turning a snack purchase into a full onboarding interview.
- Show a price the traveler can compare with the menu, including any spread.
- Move value in a way the merchant’s existing system can book before the queue grows.
- Leave an audit trail both regulators and a confused customer can follow.
- Handle the failed scan, the double scan, and the “I changed my mind” case.
The partners say they will map fund movement and settlement instructions across the remaining months of 2026. Good. That map is the product. The token is a component.
Merchant Math Is the Quiet Boss
NICE is not in this only to lend a logo. It has to ask whether stablecoin settlement helps a shop or just gives the shop another reconciliation file. Card fees are hated, but they are familiar. A new rail wins when it is cheaper, faster to settle, or better at a customer the shop cannot reach today. Tourists can be that customer. They can also be a seasonal headache.
Roughly 1.2 million merchants is a large door. The commercial question is narrower. Which categories have foreign spend high enough to care? Convenience, transit-adjacent retail, restaurants near stations, duty-free, clinics, hotels. A hardware store in a town with no visitors does not need this, and pretending otherwise inflates the story.
Cost will be examined alongside technical feasibility. That pairing is the right one. A chain that settles in seconds and costs more than the card scheme will lose to the card scheme. A cheap rail that posts the next morning will lose to cash for a 4,000-won snack. The interesting band is the middle, where the fee is visible and the confirmation is fast enough that the clerk does not hold the food hostage.
Traveler rail scorecard, informal:
  Speed the clerk can feel
  Fee the shop can explain
  Refund the customer can finish
  Rulebook both countries can live with
  Asset the partners are willing to name
Miss two of those and the pilot can still be a success as research. It will not be a product. The announcement is careful on that point, and I think the care is justified.
FX Without the Dollar Detour
One thread running through the group’s Korea work is the wish to exchange yen and won representations without parking the settlement in dollars. The September life-insurer pilot was explicit about that. The tourist test has not said it will do the same. Still, the idea sits in the background, and it is worth understanding because it changes who earns the spread.
Today a lot of cross-border card volume is converted through dollar rails even when neither shopper nor shop thinks in dollars. That is plumbing, not a conspiracy, but it is also a toll. A direct yen-won stablecoin hop could, in theory, shorten the path. In practice it needs deep enough liquidity, a clear rate source, and a legal home for each token. Without those, “direct” is a marketing word for a dollar hop with extra steps.
If the December work includes a rate model, I hope they publish the assumptions. A pretty mid-market rate in a demo and a rate a merchant actually receives are different animals. Travelers notice. Shops notice faster.
What Could Go Wrong Before Christmas
December is close. A three-party verification that touches live-style merchant systems does not have a luxurious calendar. Integration slips. Legal review slips. A policy draft in Seoul moves and the design has to move with it. None of that would make the project a failure. It would make it a project.
Other risks are more structural. An unnamed coin cannot be risk-assessed by outsiders, which is fine for a private test and awkward for anyone asked to trust a launch rumor. Merchant staff training is boring and decisive. A QR standard that works in one acquirer build may sulk in another. Travelers who already have a working card will not beta-test your edge case unless the incentive is obvious.
There is also the peg question, which never really leaves the room. A stablecoin is a claim on reserves and on the issuer’s operations. A tourist does not want a lecture on attestations at the counter. The firms standing behind the flow have to want that lecture in their own risk committee. SBI’s regulated footprint helps. It does not retire the question.
- Policy in Korea can shift while the test is still open.
- System joins between a chain and a mature acquirer are where timelines go to hide.
- Small-ticket economics may not clear the card alternative.
- Without a named asset, outside scrutiny stays shallow on purpose.
- Refunds and offline failures will decide trust faster than throughput charts.
I do not say that to dunk on the effort. I say it because the interesting version of this story is the one that survives those points, not the one that skips them.
What December Is Allowed to Conclude
The companies plan to use the findings as material for later business decisions. That is a modest sentence and the correct one. A completed verification can say the flow works in a defined setting, the cost sits inside a band, and the open regulatory issues are listed. It can also say the opposite. Both outcomes are useful. Only one of them should be sold as a coming app.
Watch for four signals if you care about whether this leaves the lab. A named stablecoin and issuer. A named chain, or a clear reason for staying chain-agnostic. A merchant count that is a test cohort, not the entire 1.2 million figure repeated as if it were live. And a sentence about refunds. If those appear, the sketch has started to harden. If they do not, the December note is a progress memo, and that is fine.
Perhaps I am too attached to receipts. Payments people get that way. A corridor this busy deserves a better tourist experience than a plastic card plus a mystery spread, and it also deserves fewer announcements that stop at the word blockchain. This one, so far, stops at a checkout and a calendar. That is a better place to stop.
Where This Sits Against Ordinary Travel Money
Cards will not vanish because a pilot started in Seoul. Cash will not vanish. Transit cards will not vanish. The realistic win is a niche that grows. Foreign visitors who do not want another cash withdrawal. Shops that want settlement in a form they can convert on their own clock. Groups that already hold licenses on one side of the water and a merchant file on the other.
Compare it with the tools a traveler already trusts. A card is ubiquitous and disputes are understood, at the price of FX padding and occasional declines abroad. Cash is final and dumb, at the price of the exchange counter. App-based QR already works inside Korea for residents. A stablecoin scan has to beat at least one of those on a trip measured in days, not in ideology.
There is a version of this I would actually recommend to a friend. Fees shown before confirm. A familiar wallet or a one-time pass that does not trap a balance. Merchant staff who have seen the flow before. A support path that answers in the languages of the corridor. Until that version exists, the honest advice is still the card in your pocket and a little cash for the stall that never joined any network.
Institutional Pipes and Street-Level Scans Are Different Jobs
It is tempting to fold every Japan-Korea test into one narrative. Resist that. An institutional settlement pilot can succeed with a handful of desks, a shared ledger, and no consumer interface. A tourist QR product fails in public, in front of a queue. The Canton-based work with Nodeinfra and the life-insurer pilot live closer to the first job. The NICE work lives closer to the second, even if no shopper is holding a production app yet.
The skills overlap. Tracking, reconciliation, and a lawful asset show up in both. The temperament does not. Institutional projects can tolerate a next-day break fix. A dinner queue cannot. If the group uses the institutional lessons without dragging institutional pace into the merchant test, that would be the sophisticated move. If it copies the architecture and hopes the till adapts, December will mostly produce a list of exceptions.
I have a soft spot for the unglamorous reading. Remittance infrastructure, the Fasset collaboration, the local dollar-stablecoin distribution, the institutional corridor tests, and now a merchant study. That is a stack being assembled in pieces. Stacks get overhyped. They also, occasionally, become the thing you use without noticing the brand.
A Note on Language and Hype
You will see this described as a stablecoin payment network, a travel revolution, a bridge. Some of those words may become accurate later. Today the accurate words are agreement, verification, and year-end target. I prefer them. They leave room for the work.
Hype is not harmless in payments. Merchants remember the last wallet that asked them to sticker their window and then went quiet. Travelers remember the app that worked in the demo city and declined at the airport convenience store. A December finish that says “not yet” would do less damage than a soft launch that half-works on a holiday weekend.
Useful test result = clear flow + named constraints + a decision, even if the decision is waitThat formula is plain on purpose. The corridor does not need another metaphor. It needs a paid flag a clerk believes.
What I Would Ask the Partners If I Had Ten Minutes
Not the chain. Not the market-cap slide. Ten practical questions, and I would take silence on half of them as a legitimate answer this early.
- Which currency does the traveler see, and which currency does the merchant receive?
- Who is the issuer, and under which registration does the Japanese leg sit?
- What is the target fee on a 10,000-won basket versus a 100,000-won basket?
- How many merchants are in the actual cohort, and in which districts?
- What happens on a timeout after the customer has confirmed?
- Is there an offline or card fallback, or does the flow simply fail?
- How are refunds initiated, and how fast do they land?
- Which Korean policy scenarios would pause commercialization?
- Does this share infrastructure with the institutional corridor tests, or is it separate?
- What would make you stop rather than launch?
The last one is the adult question. Projects that cannot describe a stop condition tend to drift into a soft launch nobody owns. The announcement’s refusal to commit to a commercial service is, oddly, the most reassuring line in it.
Travelers, Shops, and the People in Between
If you are booking a Korea trip this autumn, nothing in this verification changes what you should pack. No public service, no named wallet, no promise that a given street will accept the scan. Treat social posts that say otherwise as fan fiction until a merchant page says so.
If you run a shop on the NICE network, the relevant question is operational. Will a new tender type shorten settlement or lengthen the close of day? Will staff need a script? Will the foreign customer be worth the exception handling? Those are allowed questions. A pilot that cannot answer them by December is still a pilot.
If you build in this market, the lesson is narrower than the headline. Distribution beats protocol. A million-merchant file plus a regulated Japanese counterpart is a rarer asset than another consensus algorithm. The firms that already sit on both ends of a corridor get to run tests the rest of us only write about. That advantage is real. It is not the same thing as product-market fit.
The Longer Arc, Without the Firework
Stablecoins grew up as trading collateral and as a dollar substitute in places where local banking is painful. Using them as a tourist rail between two rich countries is a different bet. The pain is milder. The alternatives are better. The regulation is closer. Success here would say something sturdier than success in a market with no cards. It would say the rail can win on cost and convenience against instruments people already like.
Failure would say something useful too. It might say small-ticket FX is still a card business, and that stablecoins belong in treasury and remittance until the consumer edge is sharper. The group’s other projects could still stand if this one stays in the lab. Remittance does not need a street stall. A street stall does not need a life-insurer pilot. Letting them inform each other without forcing them to be the same product is the disciplined path.
I keep picturing the stall. Not because food is a metaphor. Because the acceptance test is human and slightly rude. Did the payment finish before the food got cold? Everything else is a supporting document.
Reading the Calendar Without Inventing a Launch
From early October to the end of December is a short runway for architecture, merchant process, cost work, and a moving Korean rulebook. Enough time to map a flow. Tight for a surprise product. The public commitment matches the short runway. Completion of verification, then a decision. Anyone selling a live Japan-Korea stablecoin checkout for the holiday season is ahead of the companies doing the work.
Between now and that deadline, the useful public updates would be dull. Cohort size. A description of the instruction set. A note on which regulations were reviewed. A cost range with assumptions attached. Dull updates are how you tell a serious payments project from a narrative. I will take dull.
And if the update in January is that the model needs another year, that can still be the right call. Corridors do not expire because a memorandum had a date on it. They expire when the people who could have built the rail get bored and move the slide to archive.
A Fair Bottom Line
SBI DigiTrust, NICE, and DSRV are testing whether a Japanese traveler can pay a Korean merchant with a stablecoin QR flow, and they want the study done by the end of December 2026. NICE brings a very large merchant network and the daily reality of acceptance. DSRV brings the chain design questions. SBI DigiTrust brings the Japanese regulatory and group context. The asset, the chain, the wallet, the rate model, and any launch remain unnamed. Parallel tests on institutional settlement and yen-won exchange sit nearby but are not this product.
That is a narrower story than the phrase “stablecoin payments for travel” suggests, and it is a better one. Payments get real when someone has to balance a till. This group has at least pointed the work at a till. Whether the till nods back is a December question, not an October fact.
If you remember one line, make it this. A scan is not a network, a network is not a license, and a license is not a fee a shop will accept. The partners have started at the scan. The rest is still homework. I would rather watch them finish it than watch the rest of us pretend they already have.



