
I kept refreshing the shipping notes on Thursday night, the way some people refresh a score. Not because I enjoy war maps. Because a single projectile report in a narrow waterway can move a barrel price before most desks have finished coffee. Then the carrier news landed on top of it. A third strike group, plus an amphibious force with roughly 2,000 Marines, heading into a fight that has already dragged into its eighth month. If you trade energy, or just pay for fuel, that combination is the story. Everything else is commentary.
A Third Hull Changes the Math
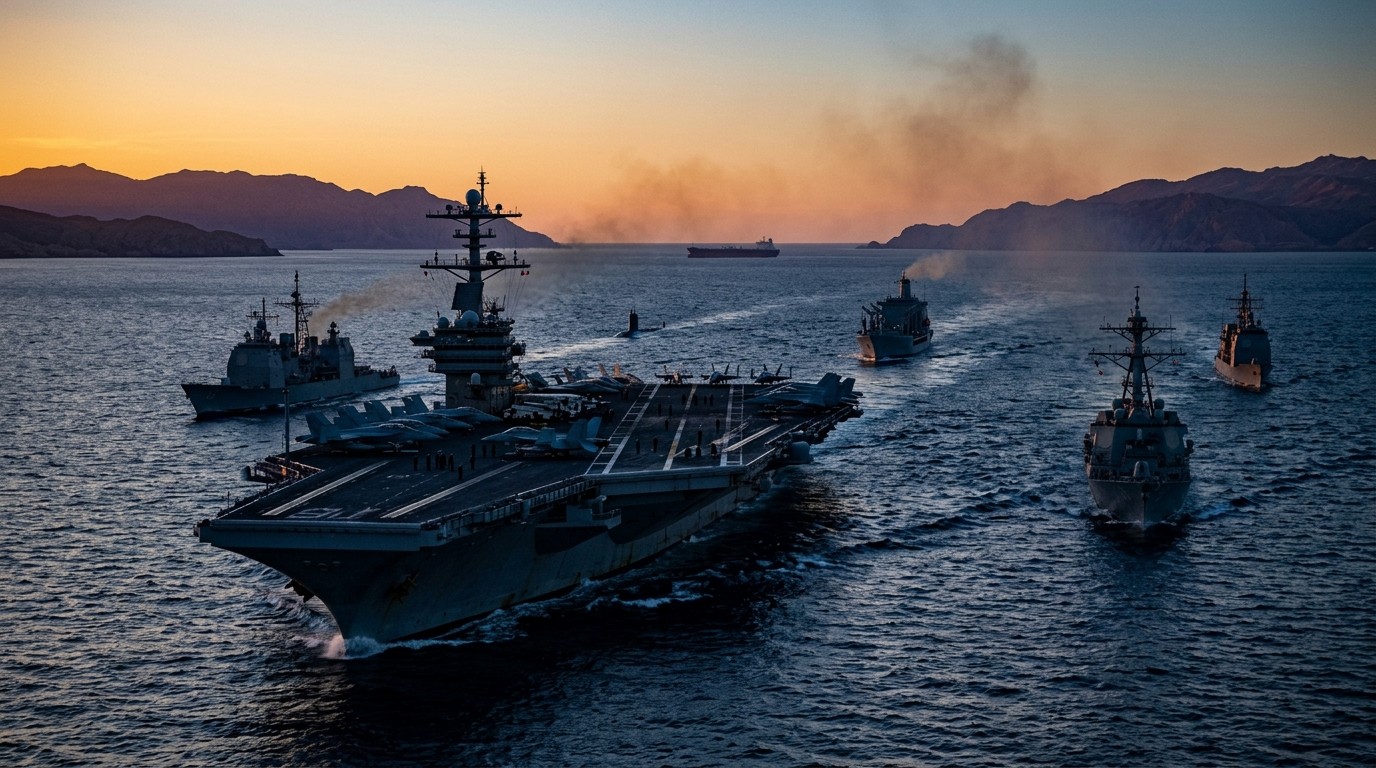
One carrier is a signal. Two can look like a holding pattern. Three, with Marines in the mix, starts to look like a government preparing options it does not want to explain in public yet. Reports say the Theodore Roosevelt group and the Makin Island force have left San Diego. A fuller buildup is expected to be in place by November. That timing is not accidental. It sits right next to talk that strikes on Iran could resume after the midterm elections.
I have watched these cycles long enough to distrust neat calendars. Ships do not vote. They also do not teleport. If hulls are already steaming, the political clock and the logistics clock are being lined up on purpose. Perhaps the most interesting part is how ordinary the language has become. “Resume bombing” used to be a phrase that stopped a room. Now it reads like a scheduling note.
The war, such as it is, has settled into a sour stalemate. Indirect talks stalled after Washington rejected an Iranian idea to reopen the Strait of Hormuz in exchange for lifting the blockade. Oil has stayed above the levels traders remember from before the fighting. That gap is the war premium, and it has been stubborn.
What the Deployment Actually Adds
A carrier strike group is not a single ship with a flag. It is a small floating air force, escorts, supply ships, and a command staff that can run strikes without asking a host country for runway space. An amphibious force is different. Marines imply the possibility of raids, seizures, or holding a patch of coast long enough for someone else to decide what happens next. You do not load that capability for a press release.
Officials have not published a public target list, and anyone claiming they know the exact mission is guessing. Still, the mix matters. Air power pressures infrastructure and air defenses. Marines pressure ports, islands, and the messy edges of a blockade. Together they widen the menu.
- A third carrier raises sortie capacity if strikes restart in November.
- The amphibious piece adds options that pure air campaigns do not have.
- Transit time from the U.S. West Coast makes the November window plausible, not theatrical.
- Presence alone can freeze tanker decisions even before a shot is fired.
Markets do not need a confirmed strike order to reprice. They need a credible path. This deployment is that path, written in steel.
November Is Doing a Lot of Work
The reported plan is blunt. Finish the buildup by November. Resume strikes the same month, after the midterms. I am not inside those rooms, so treat the sequence as reported intention, not destiny. Elections have a way of bending military timelines, and so do back-channel messages that never leak.
Still, the political logic is easy to sketch. A quieter October, a louder November. Voters see carriers leaving port in early autumn and may not connect that image to bombs weeks later. By the time the hulls are on station, the argument becomes “they are already there.” That is an old trick. It still works because distance makes the decision feel already spent.
Ships already at sea are harder to recall than speeches already drafted. Logistics has a vote, even when politics pretends it does not.
If you are positioning around energy into year-end, the calendar is the risk, not the headline. A delay of three weeks can look like de-escalation on a screen. It can also just be weather, maintenance, or a tanker queue.
Hormuz Is the Choke, Not the Metaphor
People throw the name around as if it were a slogan. It is a narrow seaway. A large share of seaborne crude and refined products still has to think about that bend of water, even when some volumes sneak out by other routes or sit idle. Iran’s medium tankers have been seen waiting off Bandar Abbas. Waiting is a strategy. It is also a bill.
The blocked deal was simple on paper and poisonous in practice. Reopen the strait. Lift the blockade. Washington said no. I get why both sides liked their own version. Iran wants revenue and a face-saving exit from a squeeze. The U.S. side does not want to trade a naval advantage for a promise that can be walked back the week after tankers start loading. Trust is the missing commodity, and you cannot store it in a tank.
On Thursday, maritime monitors said a tanker in the strait was hit by an unknown projectile. Fire broke out. The crew was reported safe. Unknown is doing heavy lifting in that sentence. In a crowded fight, attribution is often slower than the insurance email.
Why One Projectile Still Moves a Market
A single hit does not close a strait. It changes the price of fear. War-risk cover, crew bonuses, routing delays, and the decision to wait one more day outside the lane all stack. I have found that traders underweight the boring costs and overweight the dramatic ones. The dramatic clip gets the alert. The boring costs keep the barrel bid.
Think of it like a highway with one lane closed by a fender bender. Traffic still moves. Commute times do not. Oil is a commute for the global economy. Stretch the commute and someone pays, usually at the pump, then in freight, then in anything that moves.
Rough fear stack on a bad Hormuz day:
  headline shock
  + war-risk premium
  + slower loadings
  + deferred cargoes
  = a bid that outlasts the clip
None of that requires a formal closure. It requires enough doubt that a charterer would rather pay up than be the name on a damaged hull.
The Oil Tape Is Already Arguing
Crude has refused to sink back to the pre-war neighborhood. That is the market voting that the blockade, the stalled talks, and the strike risk are not a blip. Brent and WTI do not need to sprint every session to tell you the floor has moved. A higher floor is how stalemates get priced. Spikes are how escalations get priced. Right now we have the floor, and the carrier news is an invitation for the spike.
Treasury Secretary Scott Bessent said Iran loaded zero crude onto tankers in September. If that claim holds, it is a remarkable squeeze. Zero is a political word as much as a statistical one, and cargo tracking is messy when ship-to-ship transfers and dark fleet tricks are in play. Even so, the direction is hard to miss. Export capacity is being choked, or at least made expensive and slow.
A country that cannot load is a country that burns cash, delays wages, and looks for side doors. Side doors are exactly what the latest sanctions round is trying to brick up.
Sanctions Move From Oil Into the Ordinary Economy
Thursday’s Treasury action reached into Iran’s auto and rail sectors. State rail firms. Suppliers tied to the UAE, Hong Kong, Turkey, and Indonesia. The A7 network, described as a Russia-linked financial channel used to dodge restrictions, was hit as well. This is a different flavor of pressure than a tanker seizure. It goes after the plumbing that keeps a sanctioned economy looking vaguely normal.
Autos and rail are not glamorous. They move people, parts, and the illusion that daily life is intact. Squeeze those, and the pain shows up in factories and stations, not just in a budget line called “oil revenue.” I suspect that is the point. A blockade starves the export side. Sector sanctions starve the import-and-rebuild side.
- Block loadings so crude revenue stalls.
- Sanction the networks that launder what revenue remains.
- Hit civilian industrial sectors that rely on foreign parts.
- Keep the military option warm with ships already moving.
Whether that stack produces a deal or a harder fight is the open question. Pressure without an off-ramp has a habit of producing improvisation. Improvisation at sea is how projectiles get fired by “unknown” hands.
Diplomacy Left the Room Early
Indirect talks, with Qatar in the middle, failed to break the deadlock. Then came an unusual snub. Secretary of State Marco Rubio reportedly told Iranian Foreign Minister Abbas Araghchi’s delegation to leave New York sooner than planned. Diplomatic time is usually stretched, not cut. Cutting it is a message, and not a subtle one.
You can read that two ways. One: talks were so empty that hosting them longer was theater. Two: someone wanted the other side to feel the door. Both can be true. Mistrust was already the weather. This made it the forecast.
When envoys are asked to pack early, the communique has already been written in the empty chairs.
– a pattern old hands in shuttle diplomacy recognize
I do not think the early exit guarantees strikes. It does shrink the space in which a surprise compromise could land before the ships arrive. Compromises like quiet rooms and extra days. They rarely like cameras and deadlines.
Yemen’s Spark Is Not a Sideshow
The Saudi-led coalition in Yemen accused the Iran-backed Houthis of a drone strike on a power station in Medina that feeds the Prophet’s Mosque. Spokesman Turki al-Maliki said the hit on the Taibah distribution station knocked out one transformer and left the wider grid standing. A Houthi military figure called the claim a lie, meant to cover a failure to prove an earlier accusation about Mecca.
Holy cities change the temperature of a story even when the hardware damage is limited. One transformer is not a strategic collapse. The accusation is. If regional partners believe, or need to say they believe, that shrines are in play, the coalition politics around Iran get louder. Louder politics make it harder for Washington to park the carrier groups and call it deterrence.
There is a grim pattern here. A limited technical effect, a maximal political reading, a denial, and then everyone returns to their preferred map. Markets should care less about who is righteous and more about whether the denial sticks. If it does not, the southern Red Sea and the Gulf stop being separate files. They become one risk budget.
How Traders Tend to Misread a Stalemate
Stalemates feel stable because the map does not change color every morning. That feeling is expensive. Eight months in, crews are tired, rules of engagement get fuzzy, and small units start interpreting orders in ways capitals did not draft. The projectile on the tanker fits that fatigue better than it fits a grand strategy slide.
I have found that portfolios built for “nothing happens” break on the first afternoon when something small happens twice. Twice is a pattern. Once can be shrugged off as noise. The Medina claim plus the tanker hit plus the carrier departure is three data points in a short window. You do not need to believe they were coordinated to treat them as a cluster.
| Pressure point | What it does now | What would escalate it |
| Carrier buildup | Signals November options | On-station strikes or a boarding campaign |
| Hormuz blockade | Keeps the oil floor elevated | A second tanker hit or a declared closure |
| Sector sanctions | Tightens non-oil trade | Secondary hits on major trading hubs |
| Talks collapsed | Removes a near-term off-ramp | Public ultimatums from either capital |
| Yemen accusations | Pulls Gulf partners tighter | A confirmed strike near a holy site |
Read the right-hand column as a watchlist, not a prediction. Most of those boxes can stay empty and the oil price can still refuse to relax. Empty boxes are not the same as safety.
Defense, Energy, and the Awkward Middle
A buildup like this usually flatters defense contractors and unsettles airlines, shippers, and anyone whose margin is a fuel line. That split is obvious. The awkward middle is everything that needs both calm seas and steady governments: insurers, refiners with Gulf intake, petrochemical buyers, and emerging-market currencies that import diesel.
Refiners can look clever for a week if crack spreads widen, then look trapped if crude runs away from them. Shippers can charge more and still lose if a hull is the one that burns. I would rather own the scarcity narrative than the volume narrative while loadings are disputed. Scarcity does not need Iran to export zero forever. It needs the market to believe the next cargo is slower than the last.
There is also the dollar angle, quieter than the carrier photos. Geopolitical bids often support the greenback when energy stress is the source, because importers scramble for dollars to pay for the same barrel at a higher price. Not always. Sometimes the bid stays in crude and leaves currencies alone. Into November, I would not assume the quiet version.
What “Resume Strikes” Could Mean in Practice
The phrase is broad enough to cover a weekend of air raids or a month of pressure on air defenses, ports, and command nodes. It does not, by itself, mean an invasion. The Marine piece makes people jump to beaches. Beaches are not the only use. A raid on a boat, a seizure framed as sanctions enforcement, a show of force near an island: all of those fit inside an amphibious toolbox without becoming a land war.
Iran’s likely answers are the ones we have already seen in miniature. Drones, missiles, proxies, harassment in the strait, and deniable hits that complicate insurance. A state that cannot load crude still has cheaper ways to impose cost. That asymmetry is why blockades feel strong on a map and leaky in a ledger.
Could talks restart anyway? Sure. The same officials who sent a delegation home can invite another one after a strike package “restores deterrence,” which is the phrase capitals use when they want credit for stopping a fight they also extended. I am skeptical of clean off-ramps in the next few weeks. Skeptical is not the same as certain.
The Midterm Shadow
Domestic politics and naval timelines are sharing a bed here, and neither looks comfortable. A president who tells aides he expects to bomb again after voters have had their say is managing two audiences. One audience wants toughness. The other will ask why the bill arrived in winter fuel prices. Both audiences are real. Pretending one of them is imaginary is how administrations get surprised by their own polls.
From a market seat, the useful question is narrower. Does the political need for a visible result raise the odds of a kinetic November, even if diplomacy is not fully dead? I think yes, at the margin. Margins are where oil options live. You do not need a base-case invasion to own a little upside convexity into that window. You need the path to be open, which the San Diego departures suggest it is.
Simple path check: ships moving + talks cut short + oil floor sticky = November is live, not theoreticalThat is not a model. It is a napkin. Napkins have saved more P&L than elaborate decks when the input is political intent.
Shipping Desks Will Feel It First
Before a refinery in Europe reprints its slate, a freight broker has already rewritten a quote. The strait does that. So does any hint that naval rules are tightening around “unknown” fire. Crews ask questions. Owners ask for clauses. Charterers ask if the alternate route is worth the days. Those conversations are the real-time indicator, and they rarely wait for a formal briefing.
If you only watch futures settlement, you are late by a session or two. The futures catch up once the physical delays show up in inventories and loadings. September’s claimed zero loadings, if directionally right, are already that delay in official clothing. October and November will tell us whether the squeeze deepened or whether dark-fleet workarounds clawed some volume back.
Workarounds are not free. They are slower, riskier, and easier to sanction once named. The A7 hit is a reminder that financial side doors get boarded too, just with designations instead of rigid inflatable boats.
A Note on Claims and Counters
Every side in this fight is selling a version. Zero barrels. A lie about Medina. An unknown projectile. A delegation asked to leave. I try to separate the verifiable skeleton from the costume. Ships left port: that is checkable. A strike decision for November: that is reported intent. A transformer out at one station: limited, specific, disputed in motive. Hold the skeleton tighter than the costume and you will trade fewer rumors.
Rumors still matter, because other people trade them. The job is not to become a monk. The job is to know which headline can be faded by Monday and which one rewrites the quarter. Carrier movements are in the second bucket. They take weeks to undo.
Scenarios Worth Actually Writing Down
Three paths cover most of what I would underwrite. None of them require a novelist.
Quiet hardening. Ships arrive, strikes stay limited or paused, talks remain frozen, oil keeps a premium and chops. This is the stalemate extended. Boring, costly, and the base case until a tanker burns worse than Thursday’s fire.
November package. Air strikes resume once the group is on station, proxies answer, insurance spikes for a fortnight, then a new ugly equilibrium. This is the path the reported aide conversations point toward. It is also the path that makes defense names look smart and discretionary consumption look tired.
Accident ladder. A hit near a holy site, or a crew casualty in the strait, forces a faster response than anyone scheduled. This one is low probability and high gap risk. You do not hedge it with a clever relative-value trade. You hedge it by not being max short fear into a calendar everyone is circling.
I lean toward quiet hardening with a live November package, not because I enjoy gloom, but because the hardware and the diplomatic snub point the same direction. A genuine reopen-for-relief deal would need a climbdown neither side has advertised. Climbdowns happen. They rarely happen while new decks are still leaving California.
What Households Actually Notice
Most people will not track a San Diego departure. They will notice diesel, airfare, and the weird stubbornness of grocery freight. Energy shocks that refuse to mean-revert become political faster than strategists admit. Eight months is long enough for “temporary” to sound like a joke at a kitchen table.
That feedback loop matters for markets too. If pump prices stay elevated into winter, pressure grows for releases, waivers, or a louder demand for a deal. Those pressures can cap the upside in crude even while the military story gets hotter. It is a tug-of-war between naval reality and voter reality. Both pull.
Perhaps that tension is the real trade. Not “war or peace,” which is a false switch, but how much premium a tired public will tolerate before capitals look for a cheaper headline. Cheaper headlines have included partial waivers before. They could again, even with three carriers in theater. Hardware does not forbid diplomacy. It just raises the price of looking weak while you do it.
Regional Partners Are Not Props
Saudi accusations against the Houthis, Qatari mediation that went nowhere, Gulf suppliers watching their own water: none of these actors are waiting for a U.S. script. A drone claim near Medina pulls Riyadh’s credibility into the frame. A failed mediation pulls Doha’s usefulness into question for a week or two. Partners hedge. They buy cover, they message both sides, they avoid being the address on a retaliation list.
For oil flow, partner hedging can be as important as the blockade itself. A neighbor that slows cooperation on tracking, or speeds it, changes how leaky the squeeze is. I would watch official tone out of Gulf capitals more closely than another anonymous “options are on the table” line. Tone shifts before policy does.
Insurance, the Quiet Bellwether
If you want a single non-price tell, ask what war-risk underwriters are charging to cross, wait, or deviate. They do not hold press conferences. They do withdraw quotes. A withdrawn quote is a closure in miniature. Thursday’s fire, even with a safe crew, is the sort of event that makes a syndicate revisit a line it had half-forgotten.
Premiums can jump and still find buyers. The danger zone is when buyers disappear and cargoes wait. Waiting cargoes are how a paper blockade becomes a physical one without anyone announcing it. Iran’s tankers off Bandar Abbas already illustrate the pose. Add higher cover costs and the pose gets more expensive for everyone else in the queue too.
Reading the Next Two Weeks Without Fooling Yourself
A few checks are worth more than another hot take. Are additional escorts mentioned, or just the group already named? Do loading trackers contradict the zero-September claim for October, even partially? Does any official walk back the November strike expectation in public, or only in background quotes? Is the Medina accusation repeated with evidence, or left to fade? Does a second projectile report show up before the first investigation does?
Answer those and you will know whether the story is accelerating or being managed. I do not need a grand theory of the Gulf to do that work. I need a short list and the discipline not to add a sixth item because it went viral.
- Track hull movements, not adjectives.
- Track loadings, not slogans about zero.
- Track insurance availability, not just futures settles.
- Track whether diplomats are given days or shown the door.
- Track proxy claims only when hardware damage is specific.
That list will age better than a prediction of the exact night the first new strike lands. Exact nights are for people who enjoy being wrong in public.
The Stalemate’s Bill Comes Due in Barrels
Eight months is long enough to stop calling this a shock and start calling it a regime. Regimes get into models. Shocks get into headlines. The third carrier group is a headline that might lock the regime in place through winter. If strikes resume, the regime gets a violent chapter, not a new book. Oil cares about chapters. So do freight budgets, airline hedges, and any treasury desk that pretended the premium would fade by autumn.
I keep coming back to the rejected swap. Strait open, blockade lifted. It was the cleanest trade on the table, and it died. When the clean trade dies, the messy ones get funded. Messy looks like sanctions on rail suppliers in third countries, Marines on a ship, and a fire on a tanker nobody has claimed. Messy is bullish for caution and bearish for anyone who needed the old map.
None of this is an argument for panic buying. Panic is how people donate money to the bid. It is an argument for respecting a floor that policy has chosen, so far, not to remove. Floors chosen by policy move when policy moves. The ships are a hint that policy may move toward more force before it moves toward relief.
A blockade you will not trade away, plus ships you have already sent, is a strategy. It is not yet an outcome.
Outcomes arrive later, usually on a worse timetable than the press note promised. Between now and that arrival, the honest position is humble: the risk is higher than it was before San Diego emptied another pier, the talks are colder, and the oil market has already refused to pretend otherwise. If November stays quiet, good. The premium can bleed. If it does not, nobody should act surprised that the third group was exactly what it looked like on the way out of port.
I will be watching loadings, not speeches. Speeches are free. Barrels are not. And right now the people who move both seem in no hurry to make the water boring again.