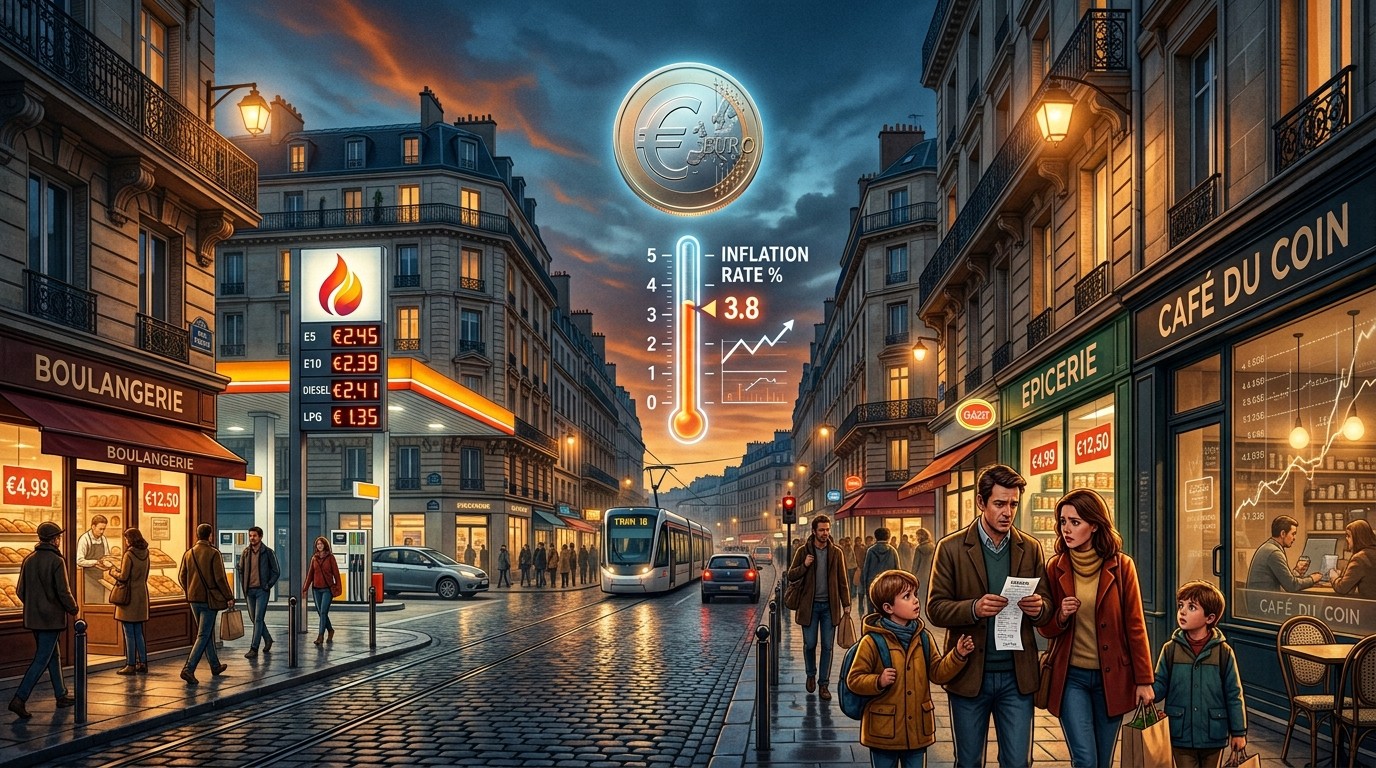

I was halfway through a coffee when the September figure landed, and I had to read it twice. Annual inflation across the euro area climbed to 3.8 percent. That is the hottest print since September 2023, a clear step up from 3.2 percent in August, and a notch above the 3.6 percent most desks had penciled in. Core inflation, which strips out the noisy stuff, held at 2.5 percent, right on the consensus. The headline jump was not a mystery. Energy prices tore higher as the Middle East conflict kept supply nerves tight. Still, a number can be explained and still feel heavy. Three years on from the last peak of this kind, households, firms, and rate-setters are staring at a target that suddenly looks farther away again.
Perhaps the most interesting aspect is how ordinary the shock feels until you put it next to a weekly shop. A few tenths of a percent do not sound dramatic in a briefing note. They land differently on a heating bill, a delivery surcharge, or a rent review that quietly indexes to last year’s prices. I’ve found that people rarely argue with the official definition of inflation. They argue with the receipt.
What The 3.8 Percent Print Actually Says
Start with the plain arithmetic. The annual rate moved from 3.2 percent to 3.8 percent in a single month. That is a six-tenths jump, not a rounding error. Markets had braced for something firm, around 3.6 percent, so the overshoot was modest in basis points and loud in narrative. The European Central Bank still aims at 2 percent over the medium term. A 3.8 percent headline sits almost twice that goal. Core at 2.5 percent is less alarming, and that split matters more than the headline alone.
Energy did the heavy lifting. Conflict in the Middle East has kept crude, refined products, and shipping insurance jumpy. When those costs filter into pump prices and industrial power, the consumer basket notices fast. Food can follow with a lag. Services, which are stickier and more wage-sensitive, did not appear to be the main villain this time. That is why core stayed put while the headline leapt.
A useful way to think about it: headline inflation is the weather outside your window. Core is the temperature inside the house after you close the doors. Right now the storm is mostly outside. The risk is that the storm lasts long enough to change the indoor climate too.
How Far This Sits From The Last Three Years
September 2023 was the last time the euro area printed a comparable annual rate. Between then and now, the disinflation story had been the dominant one. Rates were high, energy had cooled from the 2022 spike, and goods prices were easing as supply chains normalized. August’s 3.2 percent already hinted that the easy part of the descent was over. September confirmed it.
I would not call this a return to the 2022 crisis. Back then the energy shock was broader, the starting point was higher, and wage catch-up was only beginning. This episode looks narrower. It is also arriving when many households have already burned through pandemic-era buffers. That changes the politics of the number even if the economics are cleaner.
A headline can be energy, and still rewrite the mood. Mood is what boards, unions, and finance ministries actually trade on.
– Market strategist, speaking after the September release
Recent macro research keeps making the same point in dryer language. Temporary relative-price shocks do not automatically become trend inflation. They do become trend inflation if expectations slip, if wages reprice on the headline, or if fiscal policy leans against the shock in a way that keeps demand hot. September does not prove any of those channels are open. It does reopen the file.
Headline Versus Core, In Plain Terms
Core inflation at 2.5 percent, in line with forecasts, is the number policy people will underline. It suggests the underlying pulse did not suddenly accelerate. Goods disinflation and steadier services can coexist with an ugly energy month. That is the charitable reading, and it is probably the right base case for now.
The less charitable reading is simple. If energy stays elevated into winter, second-round effects show up with a delay. Transport firms reprice. Restaurants tweak menus. Landlords cite costs. None of that is dramatic on day one. It is how a one-off becomes a sequence.
- Headline at 3.8 percent: above both the prior month and the consensus
- Core at 2.5 percent: unchanged versus expectations, still above target
- Main driver: energy, tied to Middle East supply risk
- Policy gap: roughly 1.8 points between the headline and the 2 percent aim
- Time reference: hottest annual rate since September 2023
Why Energy Can Move The Whole Basket So Fast
Energy is a small slice of the consumer basket and a large slice of the variance. That is the annoying math. A 10 percent move in fuel can outweigh a quiet month in clothing or electronics. Europe still imports a heavy share of its hydrocarbons. When conflict risk lifts insurance premia and reroutes cargo, the price does not stay at the wellhead. It shows up in diesel, aviation fuel, fertilizer, and eventually bread.
In my experience, commentators underplay the speed of pass-through on the way up and overplay how fast it reverses on the way down. Pump prices adjust in days. Utility tariffs and industrial contracts adjust in weeks or quarters. Households feel the first before statisticians fully capture the second. That lag is one reason a single month can look worse than the trend, and also why you should not dismiss it as noise.
There is a second channel people skip. Energy inflation changes relative prices inside the euro area. Countries with more oil-intensive transport, colder winters, or weaker retail competition feel more of the hit. A single currency area does not mean a single cost of living. The aggregate 3.8 percent hides a spread that national governments will have to explain.
A Snapshot You Can Actually Use
| Measure | September | What It Suggests |
| Headline annual rate | 3.8 percent | Highest in three years, above forecasts |
| Prior month | 3.2 percent | Clear acceleration, not a drift |
| Market forecast | 3.6 percent | Modest upside surprise |
| Core rate | 2.5 percent | Underlying pace steady, still above 2 percent |
| Dominant driver | Energy | Geopolitical supply risk, not a wage spike |
| Policy benchmark | 2 percent | Gap reopened on the headline |
Treat that table as a map, not a verdict. One month never settles a cycle. It does reset the questions people ask at the next meeting.
The Forecast Miss, And Why It Matters
Missing by two tenths is not a crisis for forecasting models. It is a signal that the energy assumption was a bit soft. Models are only as calm as their oil path. If desks were using a flatter crude curve, September was always going to embarrass them. The miss also nudges positioning. Traders who had leaned into a smooth glide back toward target now have to mark that path later, or at least bump the uncertainty band.
I’ve found that the market reaction often hinges less on the miss itself than on the composition. A core upside surprise scares rate markets. An energy upside surprise scares growth markets and, with a lag, inflation markets. September looks like the second kind. That is uncomfortable, not catastrophic.
What Households Will Notice First
Fuel. Then heating, if the season turns cold before wholesale prices ease. Then anything that moves: groceries with a transport component, parcel fees, weekend travel. Wages do not reset on a Friday print. Budgets do. Families who set a monthly number in August are already short by September if they drive or heat with gas.
There is a quieter effect on savings behavior. When people think prices are rising again, some pull spending forward. Others freeze discretionary buys. Both can happen in the same city. Retailers hate that mix because it makes inventory planning guesswork. A 3.8 percent headline will not empty the high street. It will make October promotions a little more aggressive and a little less trusted.
Household pressure stack, rough order:
  1. Pump and heating costs
  2. Food with a freight component
  3. Indexed contracts and fees
  4. Wage talks that cite the headline
  5. Saving versus spending choice
Firms Are Not Passive In This
Companies with pricing power will test it. Companies without it will eat margin or cut hours. Energy-intensive industry in the euro area already spent two years rewiring supply. Another jump does not break that work. It does delay the moment when margins look normal again. Exporters who price in euros and buy inputs in dollars feel a second squeeze if the currency softens on the inflation news.
Smaller firms are the awkward middle. They cannot hedge fuel the way a multinational can, and they cannot raise prices the way a utility can. A baker, a regional haulier, a hotel outside the tourist core: those are the balance sheets that turn a macro print into late invoices. I keep coming back to them because the aggregate data always looks smoother than their week.
The Policy Gap, Restated Without Jargon
Two percent is not a decoration. It is the rate policymakers say they will deliver over the medium term so that people can plan. At 3.8 percent headline and 2.5 percent core, the zone is not in emergency territory. It is also not home. The distance matters because credibility is a stock, not a flow. You spend it when you explain away prints, and you rebuild it when prints cooperate.
According to monetary policy specialists who track expectation surveys, households often anchor on the prices they see, not on the core series economists prefer. Fuel on a station board is a better communicator than a statistical release. That is inconvenient if you are trying to say the shock is temporary. It is also why communication this month will matter almost as much as the next rate decision.
How Rate Setters Are Likely To Read It
Nobody sensible flips a rate path on one energy month. The question is whether this month is a blip or the start of a cluster. If oil and gas ease and core stays near 2.5 percent, the case for patience holds. If energy embeds itself into services and wage claims, patience gets expensive. The middle path, which is where I lean, is a hold with harder language and a willingness to wait for winter data before calling the disinflation trend intact.
Cuts that had been sketched for later in the cycle look less automatic. Not cancelled. Less automatic. There is a difference, and bond markets are built to trade that difference. A single upside print does not restore a hiking bias. It does remove the comfort of a straight line down.
Temporary is a claim you earn with the next three prints, not a label you stick on the one that just disappointed you.
Watch the language around second-round effects. That phrase is doing a lot of work. It means wages, margins, and expectations reacting to a shock that was supposed to pass through and leave. If officials start using it more often, they are telling you the energy story is no longer self-contained.
What Bond Markets Tend To Do With A Print Like This
Shorter-dated yields usually react first, because they price the next few meetings. Longer-dated yields react if investors decide the inflation premium itself needs to be larger. An energy-led surprise often lifts the front end a little and leaves the long end arguing with itself: higher inflation premium versus weaker growth if the shock taxes consumers. That tug-of-war can flatten or steepen the curve depending on the day. There is no single correct chart.
Credit spreads are the sleeper. If investors treat 3.8 percent as a growth tax, weaker borrowers pay more to refinance. If they treat it as a one-month energy squall, spreads barely move. Early trading often splits the difference, which is another way of saying nobody is sure yet.
- Front-end rates reprice the odds of near-term easing
- Inflation swaps pick up the energy path, not the whole cycle
- Long bonds weigh growth damage against a fatter inflation premium
- Credit looks at margins in energy-sensitive sectors
- The currency absorbs whatever rate gap opens versus peers
The Currency Channel Is Easy To Underestimate
A softer euro makes imported energy more expensive in local terms. That can feed the same inflation you are already worried about. A firmer euro, if rate expectations jump, does the opposite and also pinches exporters. September’s print pushes in both directions at once, which is why the first currency move is often messy. Traders fade the knee-jerk and then rebuild a view once they see whether officials sound relaxed or rattled.
For households this is abstract until a holiday or an imported appliance gets priced. For industry it is immediate. German machinery, Italian components, French luxury: the euro is part of the quote. A few big figures on the exchange rate will not rewrite order books. A trend will.
Growth Is The Other Side Of The Same Coin
Inflation at 3.8 percent is not only a price story. It is an income story. Real wages improve when pay rises faster than prices, and they stall when the reverse happens. If nominal pay deals were set against a glide path toward 2 percent, a renewed energy bump clips real incomes into winter. Consumption in the euro area has already been cautious. Another reason to wait on a big purchase does not help fourth-quarter growth.
Investment faces a similar fog. Projects that looked viable with stable input costs get a fresh sensitivity test. Some go ahead. Some slip a quarter. The aggregate might only shave a tenth off growth. The distribution is lumpier than that average suggests, especially in chemicals, transport, and parts of construction.
Could the shock be inflationary and contractionary at the same time? Yes. That combination is awkward for policy, because the tool that cools prices can also cool an already soft economy. It is the old uncomfortable corner, and Europe has stood in it before. Standing there again does not mean repeating 2022. It means remembering why that year felt so stuck.
Fiscal Politics Will Not Stay Quiet
Governments like to say monetary policy handles inflation and budgets handle fairness. A visible energy jump tests that division. Fuel tax cuts, targeted transfers, windfall debates: the menu is familiar. Each option has a cost. Broad cuts support demand and can keep inflation firmer. Narrow transfers protect the bottom of the income scale and leak less into prices. Doing nothing is also a choice, and it shows up in approval ratings faster than in GDP.
I am wary of blanket relief that looks generous in October and sloppy in March. Targeted help for households that spend a large share of income on energy is easier to defend. It is also harder to administer, which is why politics often prefers the blunt version. The inflation print does not force a package. It forces a conversation, and those conversations have a habit of becoming packages.
Wages, Bargaining, And The Next Round
Union calendars do not sync with statistical releases, but negotiators read the headlines. A 3.8 percent print is a talking point in any room where last year’s deal is up for review. Employers will point at core and at softer orders. Employees will point at the station price board. Both can be sincere. The settlement that comes out of that argument is what turns an energy month into a broader inflation process, or not.
Recent labor-market research suggests euro-area wage growth has already cooled from its catch-up phase, though it remains above the pace consistent with 2 percent inflation once you add trend productivity. That cushion is real. It is not infinite. A winter of expensive energy would use some of it.
Simple pass-through check: energy shock + wage response + margin response = how temporary "temporary" really isCountry Differences Inside One Number
The euro area figure is an average with weights. Larger economies pull it. Smaller ones can still diverge a lot, especially if regulated energy prices reset on different dates. A country that froze tariffs last winter may show a sharper statistical rebound when the freeze ends, even if households feel no fresh pain. Another country with market pricing will show the pain immediately and the statistics in the same month. Comparing national prints without that context is how bad arguments start.
Tourism-heavy economies also mix a different services basket into the average. A strong late summer can lift restaurant and hotel prices for reasons that have little to do with oil. September sits on the edge of that season. Some of the national detail, once it is fully published, will be energy. Some will be calendars. Both count in the headline. Only one of them tells you about the conflict.
What Investors Should Separate From What They Should Not
Separate the level from the impulse. 3.8 percent is the level. The impulse is the jump from 3.2 percent and the miss versus 3.6 percent. Separate energy from core. Separate a geopolitical risk premium from a demand boom. September fails the demand-boom test. Demand in the zone has not been roaring. The impulse is supply-side and political, which means it can fade if cargoes move and headlines cool, and it can linger if they do not.
Do not separate the print from positioning. A lot of portfolios had been built for gentle disinflation and a slow easing cycle. Those portfolios do not need to be torn up. They do need a wider error bar. In my experience, the expensive mistake is treating a one-month energy shock as either nothing or everything. The useful stance is conditional: here is what I do if the next print cools, and here is what I do if it does not.
- If energy fades and core holds: patience on rates still makes sense
- If energy sticks and wages follow: the easing path slips, and duration needs a rethink
- If growth cracks first: the inflation scare can coexist with a bid for safer bonds
- If fiscal packages broaden: watch the demand impulse, not just the relief headlines
A Practical Read For Savers And Borrowers
Savers who locked cash into short deposits are not suddenly wrong. Real returns depend on what inflation does over the life of the deposit, not on one September. Borrowers with variable rates should not assume cuts vanished. They should assume the timetable is less friendly than it looked in August. Fixed-rate offers can reprice quickly when front-end yields twitch, sometimes by more than the economic news justifies. Shopping the same loan a week apart is not paranoia. It is how this market works.
Mortgage holders in countries where resets are annual will feel any sustained shift later. Credit-card and overdraft users feel financing costs more through bank margins than through the policy rate itself. The link is real and imperfect. A hotter inflation print is a reason to check the rate on rolling debt, not a reason to panic-sell a retirement fund.
Business Planning Through The Winter Window
If I were sitting with a finance director this week, I would not ask them to rebuild the annual plan. I would ask three narrower questions. Where does fuel or power sit in the cost stack, hedged and unhedged? Which customer contracts allow a pass-through, and how fast? Which wage talks land before spring? Those answers tell you more than a refreshed macro slide.
Inventory is the sneaky one. Firms that stocked up expecting stable input costs may look clever if prices keep rising, and stuck if they fall. The September print raises the value of flexibility over precision. A slightly smaller order, a slightly shorter hedge, a clause that shares an energy spike: unglamorous tools, and usually the ones that survive contact with a jumpy quarter.
Pricing communication matters too. Customers tolerate a surcharge they can see and date. They resent a quiet increase that arrives with no story. Energy gives you a story. Using it honestly is different from using it as cover for a margin grab. The second version works once.
Scenarios Worth Keeping On One Page
Call the base case a noisy autumn. Energy stays choppy, headline inflation eases from 3.8 percent but does not sprint back to 2 percent, core hovers near the mid-twos, and rate setters wait. Growth muddles through. That is not exciting. It is plausible.
The sticky case is uglier. Conflict risk keeps a floor under oil and freight, winter demand lifts gas, and wage rounds cite the headline. Core drifts up, not explodes. Easing gets pushed out, and fiscal arguments get louder. Markets spend the winter repricing a longer plateau.
The fade case is the one optimists want. Supply fears ease, energy reverses part of the September jump, and the 3.8 percent print becomes a spike on a chart people screenshot and then forget. Core never left 2.5 percent, so the underlying story was intact the whole time. Possible. Not something I would budget as the only outcome.
| Scenario | Energy Path | Policy Lean | Market Feel |
| Noisy autumn | Choppy, partial fade | Hold, watch data | Range-bound rates |
| Sticky winter | Floor stays high | Easing delayed | Firmer front end |
| Fast fade | Reversal into year-end | Patience rewarded | Relief in duration |
None of these require a hero call. They require a trigger. Mine would be the next two inflation prints plus one clean read on wage settlements. If those cooperate, the fade case earns weight. If they do not, the sticky case stops being a tail.
Common Misreads I Keep Hearing
First misread: this means the target is abandoned. It does not. A target is a medium-term claim. One September does not rewrite a mandate. It does test patience around that mandate.
Second: core at 2.5 percent means there is nothing to see. Core is still a half point above 2 percent, and it has been the stubborn part of this cycle. In line with expectations is not the same as solved.
Third: energy shocks never stick. Sometimes they do not. Sometimes they reset the whole price level and leave a higher plateau even after the rate of change cools. The level is what your rent and your grocery baseline remember. The rate is what the year-on-year chart celebrates when it falls.
Fourth: markets will force an immediate hike. Unlikely, given core and given growth. Forcing a hike and removing a cut are different trades. September leans toward the second.
How To Follow The Story Without Drowning In It
You do not need a terminal. You need a short list. The next headline inflation rate. The next core rate. A credible read on retail fuel and wholesale gas. Any official comment that shifts from “energy” to “broader pressures.” Wage headlines from the larger economies. That is enough to know whether September was a squall.
Ignore single-day currency spikes unless they persist. Ignore commentators who treat 3.8 percent as either the return of a crisis or a statistical quirk with no household meaning. Both postures are a way to avoid the middle, and the middle is where this print actually lives.
The useful question is not whether 3.8 percent is scary. It is whether the forces that produced it are still in the room next month.
– Independent macro analyst
Where I Land After Sitting With The Number
I take the 3.8 percent seriously and I refuse to mythologize it. It is the highest euro-area annual rate in three years. It beat a 3.6 percent forecast. It rose from 3.2 percent. Energy, linked to an unresolved conflict, explains the jump better than a sudden domestic boom. Core at 2.5 percent says the foundation did not crack this month. Foundations can still crack later if the weather stays bad.
For households, the practical version is dull and correct. Check the costs that reset with fuel and power. Do not rebuild your whole financial life around one release. For anyone setting prices, wages, or portfolios, widen the range of winter outcomes and decide in advance what would change your mind. That is less satisfying than a bold call. It is how you avoid being the person who was certain, and early, and wrong.
The developing nature of the release is its own caution. Revisions, national detail, and the split between energy, food, goods, and services will refine the story. They are unlikely to erase the headline. 3.8 percent is already doing the work headlines do: resetting expectations before the full appendix arrives. If the next prints cool, this month becomes a marker on the way down that took a detour. If they do not, September will read as the month the detour became the road.
Either way, the coffee went cold. The number did not.