
I keep coming back to one uncomfortable question. If a private bank that sits inside Italy’s largest banking group can be talked into sending close to €95 million overseas in roughly forty-eight hours, what exactly is a callback procedure worth on a Tuesday afternoon? The Fideuram AI scam is not a cartoon heist. It is a sequence of ordinary messages, a cloned voice, a stack of documents that looked internal, and a payments desk that treated urgency as a kind of authorization. By the time the alarms caught up, investigators say a large slice had already been clawed back. Court papers cited in later reporting still put the unresolved hole at €39.5 million, with at least part of a smaller chain ending in Bitcoin wallets.
That number is slippery, and it should be. Early accounts spoke of at least €36 million converted toward crypto. Later court detail lifted the missing figure to €39.5 million. Recoveries moved too. One wire snapshot put overall retrieval near €53 million. Another described about €42 million blocked on the way to China and more than €13 million seized in Portugal. The gap is not a conspiracy. It is what an active inquiry looks like when freezes, returns and residual balances are counted on different days. I have found that readers get lost when headlines freeze a moving total. Better to hold both figures in view and watch the path, not the slogan.
How a Confidential Deal Story Moved Almost €95 Million
Fideuram is the private-banking arm of Intesa Sanpaolo. In late February 2026, then-chairman Paolo Molesini received a WhatsApp message that appeared to come from Carlo Messina, the group’s chief executive. The number was not one he recognized. That detail matters more than people admit. Familiar names travel. Familiar numbers are the actual credential. The sender framed a confidential acquisition of an international bank, the sort of deal that senior people are trained to treat as quiet until it is not.
According to summaries of court documents, the purported Messina said a direct purchase by the parent could not proceed. A leak, the story went, might prompt Consob, Italy’s securities regulator, to halt the transaction. Fideuram was cast as the vehicle that could finish the job without lighting up the market. It is a clever frame. It borrows real institutional fear, regulator attention, and turns the subsidiary into the hero of a secret. Nobody had to invent a fantasy product. They borrowed the bank’s own caution and aimed it inward.
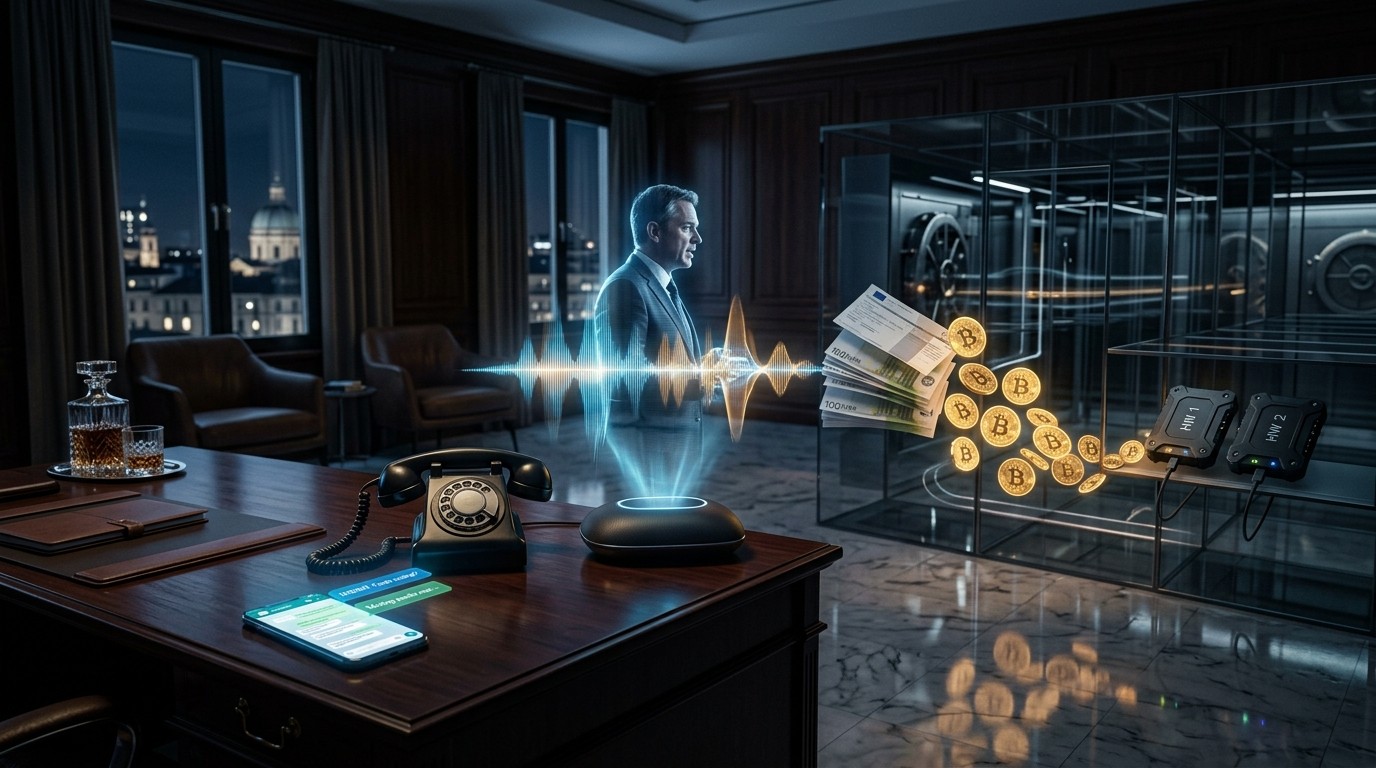
A second contact then arrived, apparently from Paolo Nastasi, managing partner of A&O Shearman Italia, a lawyer Molesini knew. Nastasi had nothing to do with the scheme. Reporting based on the inquiry says the caller’s voice had been reproduced with artificial intelligence. Emails built to resemble the law firm’s correspondence supplied payment instructions and foreign account details. Molesini was shown documents that included a confidentiality agreement and what looked like a special power of attorney carrying Messina’s signature.
The most expensive sentence in a fraud is often not a lie about money. It is a lie about why normal checks would spoil the deal.
The fraud did not live on one channel. Investigators say the treasury and payments manager received a separate call from someone posing as a senior Fideuram executive, with the message that Molesini would authorize urgent confidential payments. Eleven transfers, totaling close to €95 million, went abroad between 23 and 25 February. Substantial amounts were routed toward accounts in China and Portugal. Three days. Eleven wires. A chairman, a payments desk, and a story about secrecy. That is the whole machine.
Why the Story Felt Plausible Inside a Real Bank
People outside finance hear “AI voice scam” and picture a gullible relative. That framing misses the design. Private banking runs on discretion. Acquisition talk really is compartmentalized. Lawyers really do send powers of attorney. A chairman really can set a payment in motion if the culture treats his word as the last stamp. The impersonation did not ask anyone to abandon procedure in the abstract. It asked them to treat procedure as the threat.
I have sat through enough control reviews to know the weak joint. Dual control fails when both controllers are fed the same narrative from different phones. One hears the chairman. The other hears a senior executive confirming the chairman. Each believes the other has already done the awkward question. Perhaps the most interesting aspect of this case is how little novelty the technology needed once that loop closed. The clone did not have to be perfect for an hour. It had to survive a short call.
There is a second bias at work, and it is status. Questioning a chief executive, or a lawyer you have met, feels like career risk. Fraudsters know this. They do not start with a junior clerk. They start at the top so the middle cannot easily say no. In my experience, the institutions that survive these weeks are the ones that have already rehearsed the sentence, “I am calling you back on a number I already have.” Anything softer is theater.
What the AI Voice Actually Changed
Voice cloning is no longer a lab trick. A few minutes of public audio, an earnings call, a conference panel, a podcast, can be enough for a passable short impression. The Fideuram case, as described by investigators, used a reproduced version of a lawyer’s voice rather than a cartoon robot. That choice is tactical. A known outside counsel carries trust the chairman already holds. Messina’s name opened the door on WhatsApp. The lawyer’s voice made the paperwork feel staffed.
Technology did not replace social engineering. It decorated it. The WhatsApp number was unfamiliar. The emails were lookalikes. The signature on the power of attorney was apparent, not proven. A suspicious colleague with ten quiet minutes could have broken several of those props. Speed was the solvent. Confidential acquisition, regulator risk, urgent wires. Each phrase is a reason not to pause.
For anyone who still thinks deepfakes only hunt retail crypto users, this file is a correction. The same costume, executive face, executive voice, urgent wallet or urgent account, shows up in campaigns aimed at token holders. Founders have warned for years about fake images and cloned talks. The banking version simply swaps a seed phrase for a correspondent account. The psychology is twins.
A Timeline You Can Actually Hold
Dates keep a story honest. Here is the sequence as public reporting and court summaries have it, without pretending every hour is public.
- 23 February 2026: a WhatsApp message reaches Molesini, styled as Messina, pitching a confidential acquisition that Fideuram should carry.
- The same window: a call using what investigators describe as an AI reproduction of Nastasi’s voice, plus emails mimicking the law firm.
- Documents land, including a confidentiality agreement and an apparent special power of attorney with Messina’s signature.
- A separate call hits the treasury and payments manager, posed as a senior Fideuram executive, saying the chairman will clear urgent confidential payments.
- 23 to 25 February: eleven transfers, close to €95 million, leave for foreign accounts, with large flows aimed at China and Portugal.
- Detection follows quickly enough to freeze or reclaim a majority of the original amount.
- 12 March: Fideuram announces Molesini’s resignation as chairman of Fideuram and of Intesa Sanpaolo Private Banking, citing personal reasons. Tommaso Corcos assumes the chairman’s functions.
- Later court detail: unresolved loss stated at €39.5 million. A reconstructed chain of about €4 million reaches two Bitcoin wallets after hops through Malta, Luxembourg, the Netherlands and a Canadian money-transfer platform.
The March announcement did not publicly tie the departure to the fraud. Reporting says Molesini is not under investigation, and that the bank had not brought proceedings against him over the incident. That distinction is easy to smear and hard to keep. Resignation after a shock is not a confession. Absence from the suspect list is not a clean bill for the control environment. Both can be true.
Where the Money Stopped, and Where It Did Not
Banks are better at recalling a wire than the movies suggest, if they move before the next hop. In this file they did move. Roughly €42 million sent toward China was blocked and returned, according to agency accounts. Italian investigators secured more than €13 million at a Portuguese bank after a Milan judge authorized the seizure and local authorities cooperated. An earlier account put the Chinese recovery nearer €40 million. A wire report around the same period said about €53 million was back and about €36 million was still missing.
Court documents cited later put the unresolved amount at €39.5 million. I would not treat that as a contradiction so much as a later cut of the same cloth. Recoveries get rebooked. Fees and partial releases shift totals. What did not shift is the uncomfortable core. Some money had already left the first foreign accounts and entered crypto-linked channels before a freeze could catch it.
| Figure in public reporting | What it describes | How to read it |
| About €95 million | Eleven overseas transfers, 23–25 February | Gross amount set in motion, not the final loss |
| About €42 million | China-bound funds blocked and returned | Largest single recovery cited |
| More than €13 million | Portuguese bank funds seized | Judicial cooperation, not a voluntary return |
| About €53 to €55 million | Broad recovery estimates at different stages | Snapshots, not a final audit |
| €36 million, then €39.5 million | Earlier unaccounted sum, later court figure | Moving residual, still the live hole |
| About €4 million | Chain reconstructed into two Bitcoin wallets | One traced path, not the whole missing sum |
Notice what the table cannot do. It cannot tell you who sits at the end of those wallets. Tracing a hop is not the same as proving control, and proving control is not the same as proving the person built the voice clone. Investigators have been careful on that point, and so should anyone retelling the file.
The €4 Million Path Into Bitcoin
One reconstructed chain is unusually specific. About €4 million moved through accounts in Malta, Luxembourg and the Netherlands, then through a Canadian money-transfer platform, and on to two Bitcoin wallets. Reporting links those wallets to a person now under investigation. No court, on the public record available, has established who ultimately controlled the funds, or whether that person took part in the original impersonation.
That route is a lesson in rails. Europe’s passporting culture makes Malta, Luxembourg and the Netherlands ordinary stops for legitimate money. A Canadian platform is a familiar off-ramp into crypto for clients who cannot, or will not, use a local exchange. Bitcoin at the end is the point where recall gets ugly. A bank freeze works on a correspondent balance. It does not work on a key someone else holds.
People ask why fraudsters still bother with Bitcoin when privacy coins and mixers exist. Habit, liquidity, and exit optionality. Bitcoin is deep. It is watched, yes, but it is also spendable, splittable, and bridgeable. Two wallets are not a hiding place forever. They are a delay. Chain data is public. The hard part is the off-chain identity glued to the deposit, which is exactly where the Canadian platform and the earlier bank accounts become evidence, if foreign counterparts answer.
Who Investigators Are Looking At
Milan prosecutors are investigating a 48-year-old Israeli citizen as a suspected member of the group involved. He has not been publicly named. The link described in reporting runs through one of the foreign accounts that carried roughly €4 million before the two Bitcoin wallets. Italian authorities are still trying to establish whether the identity documents tied to him match a real person or another mask. That sentence should slow anyone drafting a villain caption. A document set is not a biography until someone checks it.
International judicial requests are going out for banking records, payment-platform data and crypto information. That is the unglamorous middle of every cross-border fraud. The money moved in days. The letters move in months. I do not find that lag surprising. I do find it expensive. Every week of unanswered request is a week in which a wallet can split, a platform can offboard, and a witness can relocate.
Molesini, again, is not a suspect in the public account. The resignation landed several weeks after the transfers. Personal reasons was the company’s phrase. Readers can infer a connection. The inquiry, so far, has not turned that inference into a charge. Keeping those lanes separate is not softness. It is how you avoid turning a control failure into a character assassination before the file is finished.
This Was Not the Only Italian File That Spring
Milan prosecutors have been looking at other frauds that used a similar mix of fake email, impersonation and voice cloning. One bank manager was reportedly persuaded in May to authorize almost €24 million. Around €20 million later came back, with funds traced through Spain, Singapore, Hong Kong and Bahrain. Those investigations are separate. A smaller institution lost roughly €2 million in another case, with part of the money recovered in Croatia.
Prosecutors have said the techniques rhyme. They have not said, publicly, that one crew ran all of them. That restraint is worth copying. Pattern is not identity. A shared playbook can sit on forums, in contractor networks, in a voice model anyone can rent. Treating three files as one gang because the script feels familiar is how defense lawyers earn their afternoon.
Still, the cluster tells risk teams something practical. The spring of 2026 was not a one-off embarrassment at a single private bank. It was a season in which urgent confidential payment became a repeatable costume. If your treasury playbook still treats a known executive’s voice as a factor of authentication, you are running last year’s control against this year’s tool.
What a Callback Is Supposed to Do
A callback is dull on purpose. You do not return the call on the number that just rang. You use the number already on file for that person, or a switchboard you dial yourself. You do not approve a new beneficiary because a PDF arrived with the right letterhead. You match the beneficiary against a change request that traveled a second, slower path. You split the people who can add an account from the people who can release a wire.
None of that is exotic. The Fideuram story, as told so far, suggests the confidential frame was allowed to compress those steps. Eleven payments in three days is not a system operating at a thoughtful pace. It is a system that decided thinking was the risk. I would rather a deal slip a day than explain €39.5 million to a board. That is not a brave opinion. It is the opinion every control officer holds until a powerful person is on the line.
- Out-of-band confirmation on a stored number, not the inbound one.
- No new beneficiary released inside the same day it appears, absent a pre-cleared exception with two logged names.
- Voice, even a familiar one, treated as a prompt to verify, never as proof.
- A hard ceiling on confidential wires that cannot be lifted by the same executive the story claims to serve.
- A payments manager with explicit cover to delay, written down before the crisis, not invented during it.
The last item is the cultural one. If delaying a chairman’s urgent payment can end a career, the control is fiction. Banks that want this not to happen again have to make the delay survivable. Publicly. In the policy. In the performance review. Otherwise the next clone will find the same soft joint.
Crypto Rails After the Bank Freeze Fails
Once value hits a money-transfer platform and leaves as Bitcoin, the recovery game changes costume. Bank secrecy letters become exchange requests and blockchain clustering. Two wallets can be watched. They can also be peeled into dozens of addresses, bridged, or sold over the counter to someone who never saw the original fraud. Speed still matters, just on a different clock.
Italy has been tightening a different crypto rule set at the same time. The Bank of Italy has told crypto service providers to run sanctions screening without a transaction-value threshold, under rules that expect checks on every crypto transfer. That policy is about compliance, not about this scam. It does, though, shrink the idea that small hops are invisible. A platform that must screen every transfer has less room to shrug at a sudden inbound from a European account.
Do not confuse screening with rescue. Sanctions filters catch listed names and some typology hits. They do not catch a fresh mule with clean documents. The Fideuram chain, if the identity papers are themselves a costume, is exactly the case a name-match misses. Behavior is the remaining signal. New account, rapid pass-through, crypto exit, multi-country hops in a week. Platforms that only score the customer at onboarding will watch the money leave and call it a completed transfer.
A Plain Map of the Social Script
Strip the brand names and the script is short enough to tape above a treasury desk. I keep a version like this when I review payment fraud write-ups, because the technology changes and the beats do not.
Confidential deal
  plus regulator fear
  plus known outside counsel
  plus cloned voice
  plus lookalike email
  plus chairman will approve
  equals same-day wires
  equals foreign hop
  equals crypto exit
Break any single line and the total collapses. The deal can be real and the counsel fake. The counsel can be real and the number wrong. The number can look internal and the beneficiary new. Fraud teams who hunt for one magic red flag will miss a file that is only slightly wrong in five places. Slightly wrong, five times, was enough for €95 million to start moving.
What Private Clients Should Take From a Bank’s Bad Week
Most readers will never authorize a €10 million wire. They will, however, get a call that sounds like their adviser, their exchange support desk, or a relative who “just needs the code.” The Fideuram file is a corporate cousin of that call. Authority was borrowed. Urgency did the rest. Crypto was the exit, not the bait.
A few habits travel well from the dealing room to a kitchen table. Hang up and dial the number you already saved. Refuse any instruction that arrives with a new account and a reason you must not tell colleagues. Treat a voice note, however familiar, as a request for a second channel. If someone mentions a regulator, a lawsuit, or a frozen account to rush you, slow down on purpose. Scammers quote real agencies because fear is faster than curiosity.
On the crypto side, the unglamorous rule still wins. Do not move life savings because a voice on a video said a founder endorsed a wallet. Deepfake clips of executives have been used for exactly that pitch. The banking case and the retail case share a costume department. Different amounts. Same impatience.
If the reason you cannot verify is the same reason you must pay, you are not in a deal. You are in a script.
A payments control test worth keeping
Recovery Is Real, and It Is Uneven
It would be easy to write this as a total loss. It was not. A majority of the €95 million appears to have been stopped or pulled back, depending on which snapshot you trust. China-bound funds returned. Portugal yielded a judicial seizure. That is what early detection buys. The bank noticed fast enough that correspondent banks still held balances. Credit where it is due, even inside a failure.
The residual is the part that stings, and it is the part that found faster rails. €39.5 million is not a rounding error for a private bank, and it is not a sum retail victims can imagine replacing. Some of it may still sit where a later freeze can reach. Some of it may already be split across wallets that will take years of mutual legal assistance to attribute. Anyone promising a full clawback is selling comfort. Anyone declaring the money gone forever is ahead of the letters still in transit.
There is also a reputational bill that does not show on the transfer list. Clients of a private bank pay for judgment. A chairman resigns. A parent group absorbs the headline. Competitors will mention it in pitches, quietly, the way bankers mention things. Whether that costs more than €39.5 million over a decade is a board question, not a crime question. I suspect the control rebuild will be priced in either way.
Legal Lanes, and What They Do Not Prove Yet
A suspect under investigation is not a convicted organizer. An Israeli citizen aged 48, tied by investigators to an account on the €4 million path, is a lead. Identity documents that might belong to someone else are a warning label on that lead. International requests are a method, not a result. Until a court tests the evidence, the fair sentence is the dull one. Prosecutors are looking. They have not finished looking.
The same care applies to the bank’s own people. Not under investigation is a meaningful status. It does not mean every decision between 23 and 25 February was wise. It means the inquiry, so far, has not treated those decisions as criminal. Civil questions, employment questions, and regulatory questions can still sit in other rooms. They often do, out of the crime pages, which is why the public file always feels unfinished.
Nastasi and the law firm were props, not participants, on the account given so far. Messina’s name was borrowed. Using a real person’s identity as a tool is part of the harm, even when the money never touched them. That is worth saying plainly, because impersonation stories sometimes leave the impersonated as a footnote. They are not a footnote to their own clients.
Why Bitcoin Keeps Showing Up in Bank Fraud Exits
Cash is heavy. A second bank account in a cooperative jurisdiction can be frozen by lunchtime if the first bank writes a clear letter. Bitcoin is lighter than both, and it does not ask the receiving bank’s permission to move again. That is the entire appeal for someone who has just received stolen wires. Not ideology. Latency.
The public ledger cuts both ways. Investigators can follow the two wallets without a warrant for the chain itself. They need warrants, or platform cooperation, for the name at the on-ramp. The Canadian money-transfer stop in this reconstruction is therefore more important than the wallet addresses as a human clue. Addresses are coordinates. The platform is where a person had to show a face, or a document pretending to be a face.
Readers who hold Bitcoin for ordinary reasons should not hear this as a moral stain on the asset. Rails get used. The same week, legitimate transfers crossed the same countries. The policy question is narrower. How fast can a platform freeze a pass-through that arrived from a bank already screaming? How often does it require a court order before it even looks? Those operational answers decide whether the next €4 million chain ends in a seizure or in a shrug.
A Board Checklist That Is Less Boring Than It Sounds
If I were writing the post-incident note for a similar bank, I would skip the slogan about embracing innovation and ask seven rude questions. Were any of the eleven beneficiaries pre-existing? Who could add a beneficiary that week? Did the payments manager have a written right to delay a chairman? Was there a stored number for Messina that was actually dialed? Was outside counsel confirmed through the firm’s switchboard? Did anyone compare the power of attorney to a known specimen? How many hours passed between the first WhatsApp and the first release?
Those questions are answerable. They also travel into training without needing a vendor’s slide about the future of AI. The model that cloned a voice is a detail. The hour that was not used to call back is the control. Boards who buy another monitoring tool and leave the callback optional will buy this headline again, with a different city on the dateline.
Training has to include the emotional bit, or it will fail in the room that matters. Play the clone. Have the chairman, or an actor, demand the wire. Watch who flinches. Then reward the person who stops it. I have watched tabletop exercises where everyone nods and nobody is allowed to embarrass a senior guest. Those exercises are rehearsals for the loss, not for the stop.
What This Does Not Tell Us
We do not have the full beneficiary list. We do not have the wallet addresses in a form the public can audit. We do not know whether the 48-year-old’s documents will survive a proper identity check. We do not know how much of the €39.5 million sat briefly in crypto versus how much is still in accounts that have not yet been frozen. We do not know whether the May case and the February case share contractors. Certainty past those lines is fan fiction.
We also should not pretend the recovery figures are a league table of competence. China returning a blocked sum and Portugal executing a seizure are different legal acts. A later court number of €39.5 million may include costs, partial releases, or balances the earlier €36 million estimate did not. Comparing them as if one reporter was right and another wrong wastes the only useful reading, which is direction. Most of the gross came back. A very large residual did not.
The Retail Echo Is Already Here
Related coverage over the past few years has shown the same costume pointed at crypto users. Fake videos of executives. Cloned voices telling holders to move coins to a “safe” wallet. Founders warning that images of them are circulating in pitches they never made. The Fideuram matter is the institutional mirror. Different door, same hallway. If a chairman can be walked through it, a customer with a six-figure balance should assume the costume will be tried on them too.
The defense is repetitive because the attack is repetitive. Saved numbers. Second channel. No seed phrase read aloud. No “support” session that asks for a screen share of a wallet. No investment that vanishes if you sleep on it. Boring rules. They are boring because they work, and they fail only when someone with status asks you to suspend them for an afternoon.
A Note on the Resignation and the Chair That Followed
Leadership changes after a shock are read as signals even when the press line says personal reasons. Tommaso Corcos taking the chairman’s functions gave the bank a public handoff. Clients needed a name. Staff needed a name. The inquiry did not need the resignation in order to proceed, and the resignation did not need to be a finding. Holding both ideas at once is possible. It is also rarer than it should be in comment sections.
What I would watch next is not the personal story. It is whether payment policy changed in a way an outsider can describe. New beneficiary delays. Mandatory callbacks on stored lines. A documented right for treasury to stop a confidential wire. If those three exist on paper by the next annual report, the institution learned the expensive lesson. If they exist only as a memo about vigilance, the lesson was rented for a news cycle.
How to Read the Next Update Without Getting Spun
More letters will come back from Malta, Luxembourg, the Netherlands, Canada, China and Portugal. Some will add a name. Some will add a dead end. A wallet may get attributed. A platform may say the account was already closed. When that happens, match the new fact to the old structure instead of replacing the structure.
- Gross sent is still the February total near €95 million, unless a bank restates the payment file.
- Recovered is a moving sum, already seen near €53 million and, in broader descriptions, around €55 million.
- Unresolved, on later court papers, is €39.5 million until a judge or the bank publishes a different residual.
- The Bitcoin path currently described is about €4 million, not the entire hole.
- The investigated individual is a suspect in a group, not a proven architect of the voice clone.
If a future update collapses those lines into one villain and one missing pile, it is simplifying for the thumbnail. The file is messier, and the mess is the point. Money that can be frozen in China is not the same object as money that has become Bitcoin in a wallet tied to documents investigators still do not trust.
What I Think the Case Is Really About
Not the model weights. Not even Bitcoin, except as the exit that beat the freeze. The Fideuram AI scam is about a permission structure that treated a familiar voice and a frightening story as a substitute for a slow check. AI made the voice cheaper to fake. It did not invent the appetite for secrecy, or the fear of being the person who delayed the chief executive’s deal.
€39.5 million is a large tuition fee for that lesson. Some of it may come back. The traced €4 million chain shows that crypto did not make the money metaphysical. It made it faster. Faster is enough, if the institution on the other side is still debating whether a callback would be impolite.
I will be watching the international requests more than the next demo of a voice tool. Tools are already good enough. The open question is whether a payments desk, the next time a chairman’s number is not the chairman’s number, is allowed to be rude for twenty minutes. Twenty minutes, on 23 February, would have been cheap.