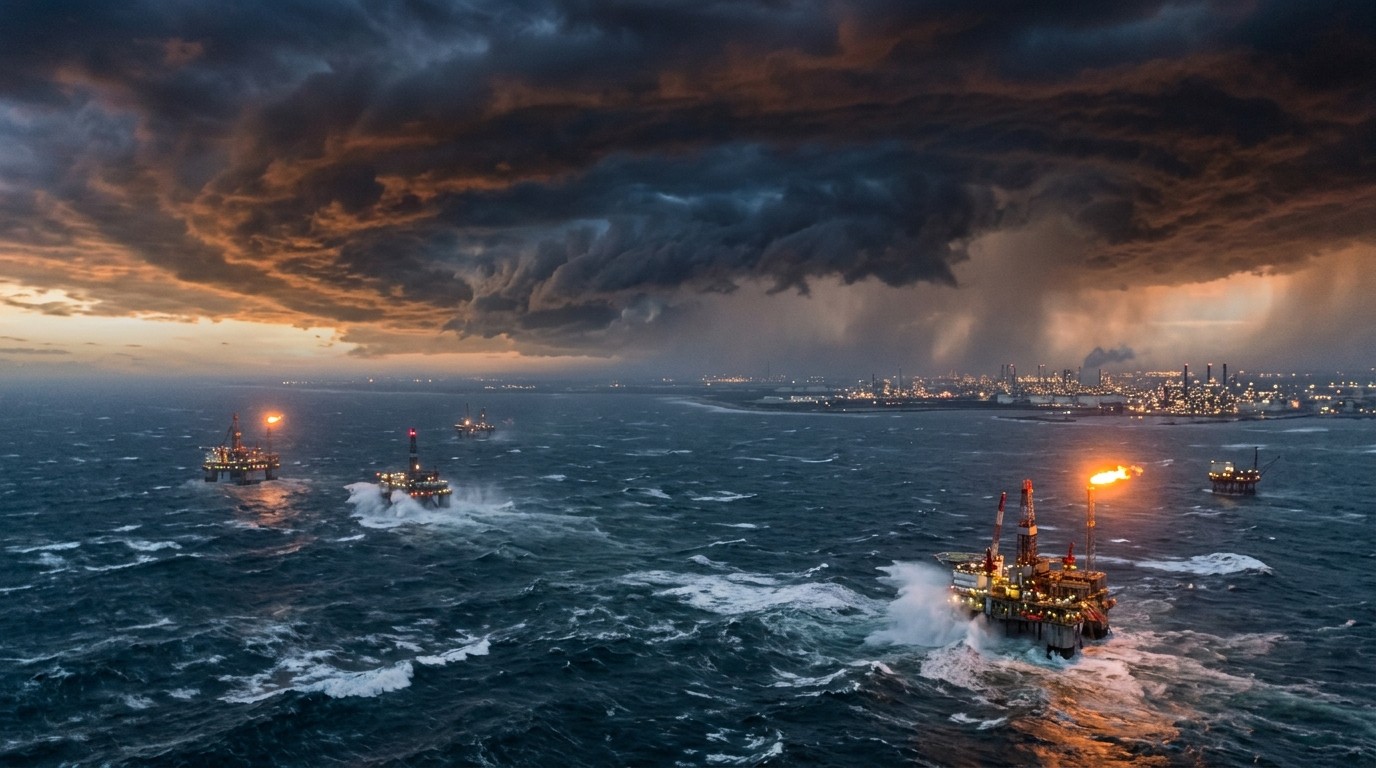

I was checking the latest storm updates this morning when the numbers hit me harder than expected. Nearly two-thirds of all U.S. oil production in the Gulf of Mexico has already been shut in because of Hurricane Isaias. That’s 1.3 million barrels every single day sitting idle while a Category 3 storm with 120-mile-per-hour winds barrels toward the northern Gulf Coast. And the timing could hardly be worse.
Why This Storm Hits Energy Markets At The Worst Possible Moment
Fuel markets around the world were already running tight before Isaias even formed. Wars in Eastern Europe and the Middle East have knocked out significant refining capacity. One major producer had to ban diesel exports after repeated strikes on its facilities. Other attacks have hit refineries farther east. In that environment, U.S. refiners stepped up and started shipping diesel overseas at strong profit margins, especially to Europe. Now a powerful hurricane is threatening to interrupt both the crude supply and the refining side of the equation at the same time.
I’ve watched these Gulf storms for years, and the pattern is familiar yet never comfortable. Companies pull workers off platforms early, close production valves, and wait. This time the shut-in percentage reached about 63 percent of total Gulf output by Thursday. That’s not a small number when global balances are already stretched.
The Scale Of The Production Shutdown
Offshore operators moved quickly once the storm’s track became clearer. Platforms across a wide stretch of the central and eastern Gulf went into safe mode. The result is that 1.3 million barrels per day of crude are no longer flowing. For context, that volume represents a meaningful slice of total U.S. output, even if the Gulf itself is only one piece of the national puzzle.
What makes the situation more delicate is the lack of spare capacity elsewhere. Refineries along the Gulf Coast have been running near 95 percent utilization. There simply isn’t much slack left in the system to absorb a sudden loss of crude or a temporary drop in refined product output. When everything is already running hot, even a short disruption can create ripples that last longer than the storm itself.
When refineries lose crude supply and cannot produce fuel for consumers, prices for products often rise even as crude prices soften. The two sides of the market pull in opposite directions for a while.
That observation tracks with what several market watchers have noted in past storms. Crude demand from the refining complex drops, which can pressure benchmark prices downward, while gasoline, diesel, and jet fuel become scarcer on the product side. The net effect for consumers is rarely pleasant.
Refineries In The Crosshairs
The storm’s projected path appears to spare the densest concentration of refining capacity around southern Louisiana. That is the good news. The less welcome news is that facilities in Mississippi and Alabama sit closer to the expected landfall zone. One major refinery in Pascagoula and another in Saraland together account for roughly 466,000 barrels per day of capacity. That works out to about 2.4 percent of total U.S. refining ability.
Both areas remain under hurricane warnings. As of the most recent updates, the Pascagoula facility was still operating. Information on the Alabama plant was not immediately available. Even if both sites ride out the storm without major damage, the surrounding infrastructure, power supply, and transportation networks could face interruptions that keep throughput lower for days or longer.
I’ve always found the coastal refining corridor fascinating because of how concentrated the capacity is. A relatively small geographic area handles a surprisingly large share of the nation’s fuel production. When a storm draws a bead on any part of that corridor, the entire system feels it.
Tanker Traffic And Downstream Delays
Production and refining are only part of the story. Shipping schedules take a hit as well. Tankers that would normally deliver crude to Gulf Coast plants face delays. Other vessels waiting to load gasoline, diesel, and jet fuel for export or domestic distribution also sit idle. The knock-on effects reach farther than many people expect.
Florida, for example, relies heavily on waterborne deliveries of refined products. Any interruption in Gulf loading operations can translate into tighter supplies and higher prices at the pump in the days that follow. The same logic applies to jet fuel for airports and diesel for trucking fleets across the Southeast.
- Crude deliveries to refineries slow or stop
- Product loadings for domestic and export markets face delays
- Coastal states that depend on marine transportation feel the pinch first
- Inventory draws can accelerate if the disruption lasts more than a few days
None of these outcomes is automatic. A lot depends on the exact track, the storm’s forward speed, and how quickly operators can restore production and logistics after the winds die down. Still, the baseline risk is clearly elevated.
Global Context Makes Local Disruptions Louder
What turns a regional weather event into a broader market story is the backdrop of already tight diesel and fuel markets. With certain overseas refining systems under pressure, the United States has become a more important supplier of middle distillates to the rest of the world. Wide crack spreads encouraged higher utilization rates and stronger export volumes. That strategy works well until something interrupts the Gulf Coast machine.
In my view, the current environment leaves less room for error than we saw in quieter years. When inventories are lean and every barrel of diesel finds a ready buyer, the loss of even a few hundred thousand barrels of daily refining capacity carries more weight. The same holds for crude. Removing 1.3 million barrels of Gulf production, even temporarily, tightens the prompt market until those volumes return.
How Operators Typically Respond
Oil companies have refined their storm protocols over decades. They evacuate non-essential personnel well ahead of tropical-force winds. Production is shut in according to established safety thresholds. Platforms are secured, and the industry essentially goes into a defensive crouch until the system passes.
Restoring output afterward is rarely instantaneous. Platforms must be inspected, any damage assessed, and personnel returned. Subsea infrastructure needs checking. The timeline can stretch from a couple of days for a glancing blow to weeks if a facility takes a direct hit or if onshore support systems remain offline.
Refineries follow a parallel playbook. They may reduce rates, secure loose equipment, and in extreme cases shut down entirely if the threat is severe enough. Restarting a complex refining unit after an unplanned outage is a careful, multi-day process. Safety always comes first, which is exactly as it should be.
What Past Storms Teach Us About Price Reactions
History offers some useful patterns, even if every storm is different. When Gulf refining capacity goes offline, product prices often climb while crude prices can soften because the refineries are no longer pulling as much feedstock. The divergence usually narrows once operations normalize, but the interim period can be uncomfortable for drivers and airlines.
Diesel has been particularly sensitive in recent months. Strong export demand and constrained global supply have kept the market firm. Any additional loss of Gulf Coast diesel production would likely reinforce that firmness. Gasoline and jet fuel would face similar pressures, especially in the Southeast where logistics depend heavily on waterborne movements.
Perhaps the most interesting aspect is how quickly markets can rebalance once the physical disruption ends. Inventories, imports, and higher utilization at unaffected plants all help fill the gap. The question is always how long the gap lasts and how much precautionary buying occurs in the meantime.
Looking Ahead To Landfall And Beyond
Isaias is expected to make landfall Friday night or early Saturday along the Mississippi, Alabama, or Florida Panhandle coast. Maximum sustained winds are currently near 120 miles per hour. The exact point of landfall and the storm’s forward speed will determine how long production stays offline and how much stress the coastal infrastructure endures.
After the system moves inland and weakens, attention will shift to damage assessments and restart timelines. Offshore operators will publish updated shut-in figures. Refinery status reports will trickle out. Product markets will watch inventory data and export schedules closely.
I’ve found that the first 48 to 72 hours after landfall often set the tone for the recovery narrative. Early reports of minimal damage can calm markets quickly. Signs of more extensive problems tend to keep prices elevated longer. Either way, the underlying tightness in global fuel markets means the margin for error remains slim.
Broader Implications For Energy Security
Events like this serve as reminders of how concentrated certain parts of the U.S. energy system remain. The Gulf of Mexico still accounts for a meaningful share of domestic crude production. The Gulf Coast refining complex is even more dominant in terms of capacity and sophistication. Geographic concentration brings efficiency under normal conditions and vulnerability when extreme weather arrives.
At the same time, the industry has invested heavily in resilience. Platforms are engineered for severe conditions. Evacuation and shut-in procedures are practiced regularly. Refineries maintain detailed severe-weather plans. Those preparations limit the damage, yet they cannot eliminate the temporary loss of production and the associated market impact.
From a market perspective, the episode also highlights the interconnected nature of global fuel trade. When one region faces constraints, other regions feel the effects through price signals and trade flows. The current combination of geopolitical disruptions and a major weather event simply amplifies those linkages.
Practical Takeaways For Market Watchers
Anyone following energy markets in the coming days will want to track a few key indicators. Updated shut-in volumes from official sources provide the clearest picture of lost crude production. Refinery status reports, even informal ones, help gauge the product side. Inventory statistics and export data will reveal how quickly the system is rebalancing.
Price differentials between regions can also tell a story. Strength in Southeast gasoline or diesel relative to other parts of the country would signal localized tightness caused by logistics constraints. Widening or narrowing crack spreads will show how the refining margin environment is evolving in real time.
- Monitor official shut-in statistics for the Gulf of Mexico
- Watch for any confirmed reductions at coastal refineries
- Track product inventory changes, especially in the Southeast
- Follow tanker scheduling and port status updates
- Observe price spreads between different fuel grades and regions
None of these steps requires specialized access. Most of the information becomes public within a reasonable timeframe. The challenge is putting the pieces together into a coherent view of how long the disruption is likely to last and how markets are adjusting.
A Personal Observation On Timing
What strikes me most about the current situation is the layering of risks. Geopolitical tensions have already reduced available refining capacity in other parts of the world. Strong demand for diesel has kept U.S. plants running hard. Inventories in some categories sit below comfortable levels. Into that mix comes a major hurricane that forces a large share of Gulf production offline and threatens additional refining capacity.
Each individual factor is manageable. Together they create a tighter environment than we have seen in some time. That does not guarantee dramatic price spikes. It does mean that any further surprises, whether weather-related or otherwise, would land on a market with less cushion than usual.
Storms come and go. Markets adapt. The process is rarely smooth, and the interim period often feels more uncertain than the eventual outcome justifies. This episode looks likely to follow a similar path. The next several days will tell us how severe the physical impact proves to be and how quickly the energy system can return to normal operations.
Until then, the shut-in barrels remain offline, the threatened refineries sit under warning flags, and fuel markets continue to navigate an already challenging global landscape. The story is still unfolding, and the details that emerge after landfall will shape the recovery narrative for weeks ahead.
Final Thoughts On Resilience And Vulnerability
Hurricane Isaias is a vivid illustration of both the resilience and the vulnerability built into the modern energy system. Companies can shut in production safely and protect workers. They can restart operations with practiced efficiency once the threat passes. At the same time, the sheer concentration of activity in the Gulf region means that a single storm can remove a noticeable share of national supply for a period of time.
For consumers, the most visible effects usually appear at the pump or in higher costs for goods that move by truck. For markets, the effects show up in price volatility, shifting trade flows, and temporary changes in inventory trajectories. For the industry itself, each storm becomes another data point in the ongoing effort to balance efficiency with preparedness.
As the system moves ashore and begins to weaken, the focus will shift from preparation to assessment and recovery. The numbers that emerge in the coming days—how many barrels stay offline, how quickly platforms return, whether any refining capacity suffers lasting damage—will determine the ultimate market impact. Until those numbers become clearer, caution remains the prevailing mood across energy markets.
The situation underscores a simple reality. Weather still matters a great deal in the energy business. Even in an era of sophisticated forecasting, advanced engineering, and global trade, a powerful storm can force the system to pause. How long that pause lasts, and how the rest of the market responds, will be the central questions as Hurricane Isaias completes its journey across the northern Gulf Coast.