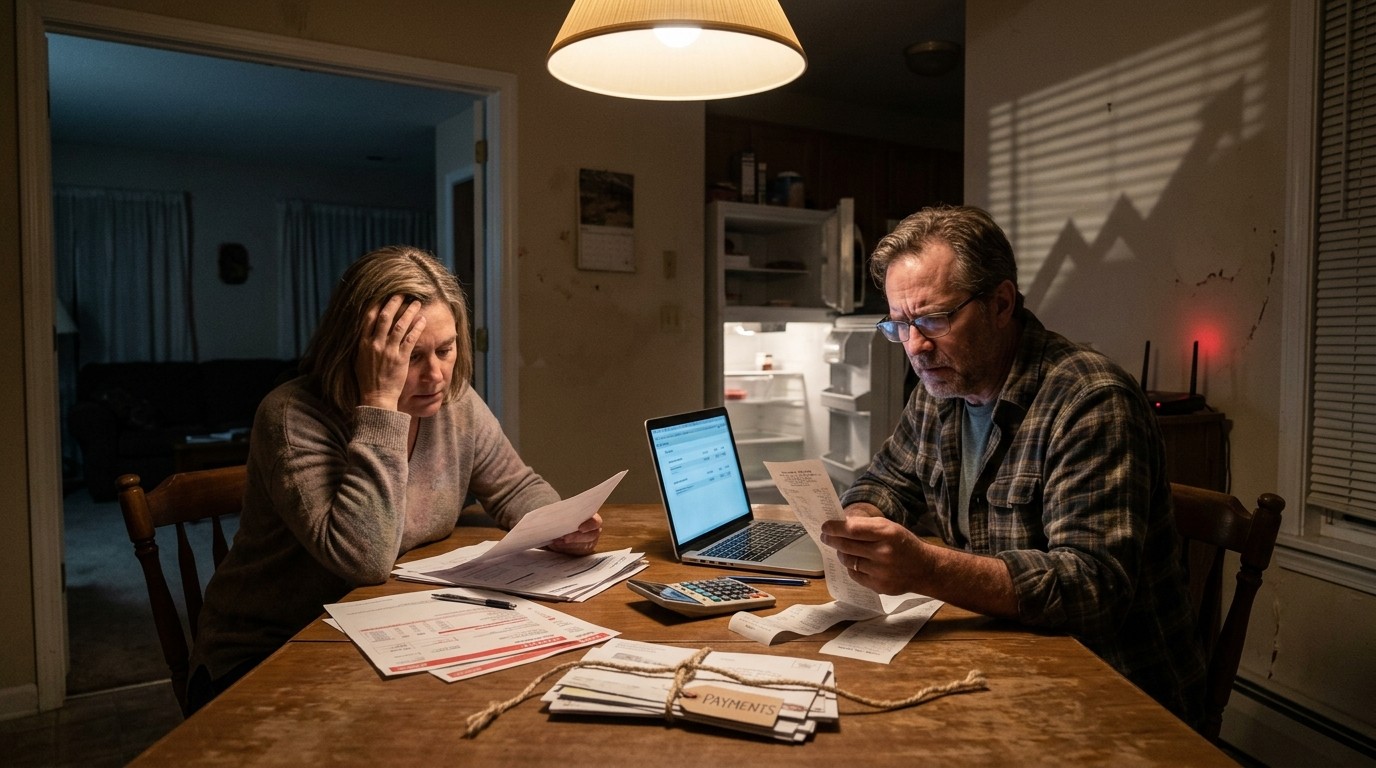

I still remember sitting across from a friend last winter as she sorted through a stack of overdue notices. She kept saying the same thing: “We never used to miss payments.” That quiet confession stuck with me. Now the newest numbers from the latest Federal Reserve survey make it clear her experience is far from isolated. For the three-year stretch ending in 2025, the share of families behind on loan payments climbed from roughly 12 percent to nearly 20 percent. That is the highest reading since the 2010 survey, right when the country was still shaking off the Great Recession.
What the Latest Survey Actually Shows About Household Strain
The Survey of Consumer Finances lands every three years and paints the most detailed picture we get of how ordinary households are doing with money. This time the message feels heavier than the growth headlines we keep hearing. Families were more likely to be behind on their obligations than at any point since that 2010 snapshot. The jump is steep—about 67 percent higher than the previous survey. Those behind by two months or more also rose sharply, moving from 5 percent to more than 8 percent.
At the same time the share of families with payment-to-income ratios above 40 percent climbed to 8.6 percent, up from 6.5 percent and the highest level since 2013. In plain language, more households are stretching their monthly budgets past the point that most financial planners consider comfortable. I’ve found that once a family crosses that 40 percent threshold, the stress starts showing up in conversations at the dinner table, in delayed home repairs, and in the quiet decision to skip a medical checkup.
Wealth Gains That Did Not Reach Everyone
While debt trouble deepened, overall net worth still moved higher. Inflation-adjusted average net worth rose 7 percent to $1.24 million. Median net worth, the number that better reflects a typical family, increased only 2 percent to $215,900. That gap between average and median tells its own story. Gains concentrated at the higher end of the distribution. Families in the top income group saw median net worth climb 31 percent. Lower-income families, by contrast, watched median net worth slip 6 percent and average net worth fall 4 percent.
Education continues to draw a sharp line. Households headed by someone with a college degree held nearly three times the median net worth of those with only some college. Income patterns followed a similar split. Real median family income rose 7 percent, yet average income dropped 6 percent. Families at the lower ends of the income and net worth scales recorded modest gains, while those at the upper ends saw declines. The report noted that income inequality decreased slightly between surveys—an unusual shift given the decade that came before.
Families were more likely to be behind on their financial obligations than at any point since the 2010 survey.
Age mattered too. Families aged 75 and older enjoyed particularly strong income gains. Those between 35 and 44 watched income fall 25 percent, largely because of lower capital gains. Black non-Hispanic families, Asian families, and households already near the top of the income and net worth distributions also recorded declines in both median and mean income. These details matter because they shape the day-to-day reality for couples trying to plan a future together.
How Rising Delinquency Feels Inside a Relationship
Debt stress rarely stays on the spreadsheet. When nearly one in five families falls behind on payments, that pressure shows up in living rooms and bedrooms across the country. Couples start arguing about small purchases. One partner may hide a late notice. Trust erodes a little each time a due date passes unpaid. I’ve watched friends who once talked openly about money suddenly grow quiet on the subject. That silence is often the first sign trouble is deepening.
The period covered by the survey included inflation rates not seen since the early 1980s. Grocery bills, rent, and insurance premiums all climbed. Even households that kept their jobs felt the squeeze. Higher earners could absorb the higher costs and still add to their net worth. Lower- and middle-income couples often had less room to maneuver. The result is a quiet divergence that can strain even strong partnerships.
- More families carrying payment burdens above 40 percent of income
- Sharper increases in serious delinquency (two months or more)
- Wealth growth skewed toward the highest income group
- Modest income gains at the bottom, declines at the top for some groups
- Education still acting as a major wealth divider
Why This Moment Feels Different From Past Cycles
During the Great Recession the pain was concentrated in housing and unemployment. This time the economy kept growing. Jobs remained available. Yet the ability to stay current on debt worsened. That combination is unusual. It suggests that the cost of living has outrun wage growth for a meaningful share of households. When inflation runs hot for years, even steady paychecks lose purchasing power. Families that once managed their debt service suddenly find the same payments harder to make.
Perhaps the most interesting aspect is the narrowing of measured income inequality alongside rising payment trouble. On paper the distribution of income looked a bit more even. On the ground more families fell behind. That tension points to something deeper than simple averages. The cost of essentials rose faster than many incomes, and higher interest rates made existing debt more expensive to carry. Couples who refinanced or took on new loans during the low-rate years now face a different reality.
Practical Steps Couples Can Take Right Now
Facing these numbers does not mean every household is doomed. It does mean open conversation becomes more important than ever. Start by listing every monthly obligation and the exact due date. Many couples discover they have never put the full picture on one page. Seeing the total payment-to-income ratio in black and white can be uncomfortable, yet it is the first step toward control.
Next, rank the debts by interest rate and consequence of missing a payment. Mortgage or rent usually sits at the top. Credit cards and personal loans often carry the highest rates. Automobiles sit somewhere in the middle. Once the ranking is clear, any extra money can attack the most expensive balance first while minimums stay current on the rest. This approach is not new, but it still works better than spreading small payments across every account.
- Gather every statement and create a single master list of obligations
- Calculate the true payment-to-income ratio including insurance and utilities
- Identify one high-interest balance that can be reduced faster
- Agree on a short weekly money check-in, even if it lasts only ten minutes
- Review insurance deductibles and subscriptions that may have crept upward
Some couples benefit from a short cooling-off rule. Any purchase above a set amount requires a 48-hour pause. The rule sounds simple, yet it interrupts the impulse spending that often follows a stressful week. I’ve seen partners who adopted the pause report fewer arguments and a clearer sense of shared priorities.
The Role of Age and Life Stage
The survey data showed income rising for the oldest households and falling for those in their late thirties and early forties. That pattern carries relationship implications. Younger couples may be carrying student loans, childcare costs, and housing payments at the same time their capital gains income dropped. Older couples often benefit from paid-off homes and required minimum distributions that count as income. The result is two very different financial realities under the same broad economic headline.
For couples in the 35-to-44 group the 25 percent income drop linked to capital gains is especially notable. Many in that age band had begun investing more actively in recent years. When markets cooled or gains simply did not materialize at the same pace, household income figures reflected the change. That volatility can feel personal even when it is driven by broader market conditions.
Looking Ahead Without Panic
These survey results are a snapshot, not a permanent verdict. Households adjust. Some will refinance when rates allow. Others will increase hours or add a side stream of income. A few will downsize housing or vehicles. The key is recognizing the pressure early rather than waiting until two or three payments have already been missed.
In my experience the couples who navigate these periods best treat money as a shared project instead of a source of blame. They schedule regular, low-drama conversations. They celebrate small wins such as paying off a single credit card or building a one-month emergency buffer. They also give each other grace when progress is slower than hoped. Financial strain tests a relationship; it does not have to define it.
The newest data makes one fact unavoidable. A larger share of American families is struggling to keep up with debt payments than at any time since the recovery from the last major crisis. Wealth continues to grow for some while others slip further behind. For couples the practical response begins with clear numbers, honest conversation, and a willingness to adjust habits together. The warning lights are flashing. Paying attention now can keep a temporary squeeze from becoming a lasting rupture in both the household budget and the relationship itself.
What stands out most to me after reading the full set of findings is the quiet nature of the pressure. Unemployment did not spike. The economy did not collapse. Yet nearly one family in five is now late on payments. That kind of widespread, low-grade stress can be harder to spot than a sudden crisis, and therefore easier to ignore until the late notices start arriving. Couples who choose to face the numbers early give themselves the best chance of staying ahead of the curve.
Breaking Down the Numbers in Everyday Terms
Let’s translate the percentages into something closer to daily life. A jump from 12 percent to nearly 20 percent means that in a neighborhood of fifty families, roughly six more households are now behind on loans than three years earlier. Those six families are not abstract statistics. They are the neighbors who stop answering the door when the mail carrier brings certified letters. They are the coworkers who skip the Friday lunch because every dollar is already spoken for.
The rise in serious delinquency—from 5 percent to more than 8 percent—carries even heavier weight. Missing two full months of payments usually triggers late fees, higher interest, and the first steps of collection activity. Once that process begins, catching up becomes substantially harder. For a couple already stretched thin, the added costs can turn a temporary setback into a multi-year recovery project.
| Indicator | 2022 Survey | 2025 Survey | Change |
| Families behind on payments | About 12% | Nearly 20% | +67% |
| Behind two months or more | 5% | More than 8% | Sharp rise |
| Payment-to-income above 40% | 6.5% | 8.6% | Highest since 2013 |
| Top income group median net worth | — | — | +31% |
| Bottom income quartile median net worth | — | — | -6% |
These figures do not capture every nuance. Some families behind on payments may still own homes that have risen in value. Others may have strong job prospects that will eventually close the gap. Still, the direction of the trend is clear enough to warrant attention inside any household that carries debt.
When Higher Earners Pull Ahead
The 31 percent jump in median net worth for the top income group stands in sharp contrast to the declines recorded at the lower end. That divergence is not simply a matter of investment returns. Higher earners often have more flexible budgets, greater ability to refinance, and larger cushions against inflation. When prices rise, they can maintain savings rates. When markets offer opportunities, they can take them. Lower-income couples frequently lack those options.
For relationships the practical effect is that two households living on the same street can experience the same economic period in completely different ways. One couple adds to retirement accounts and plans a home renovation. The other couple debates whether to pay the electric bill or the credit-card minimum. Over time those different realities can influence everything from social invitations to long-term plans for children or aging parents.
Income Patterns That Defy Simple Stories
Median income rose while average income fell. That combination usually signals that gains at the lower and middle parts of the distribution outweighed declines higher up, or that the very top experienced larger drops. The survey confirmed both dynamics in places. Families at the lower ends saw modest increases. Some groups near the top recorded declines. Black non-Hispanic families, Asian families, and households already high in the usual income distribution all saw both median and mean income fall.
Age added another layer. The strong gains for families 75 and older likely reflect a mix of Social Security adjustments, required withdrawals from retirement accounts, and the simple fact that many in that group carry less debt. The sharp drop for the 35-to-44 cohort tied to capital gains is a reminder that investment income is volatile. Couples who counted on portfolio growth to supplement wages found themselves with less than expected.
These patterns matter because they shape the emotional climate inside a relationship. A couple that expected rising investment income and instead saw it decline may feel a sense of failure even if their jobs remained stable. Conversely, an older couple enjoying higher reported income may feel more secure and therefore more generous with time and attention. Money is never just numbers; it is also the stories people tell themselves about progress or setback.
Education as a Continuing Divider
Households with a college degree continue to hold roughly 1.9 times the median income and nearly three times the median net worth of those with only some college. That gap has persisted across multiple surveys and shows little sign of closing quickly. For couples the implication is straightforward. Educational attainment still functions as one of the strongest predictors of financial resilience. Partners who both hold degrees generally start with a larger buffer against the kind of payment trouble the latest survey documents.
That does not mean education is a guarantee. Plenty of degree-holding households appear in the delinquency statistics. It does mean that, on average, the margin for error is wider. When inflation spikes or interest rates rise, those wider margins can be the difference between staying current and falling behind.
Turning Awareness Into Action Inside the Home
Data alone rarely changes behavior. What changes behavior is a clear plan that both partners accept. One approach that works for many couples is the weekly money date. It does not need to last long. Ten or fifteen minutes with the calendar and the bank balances is often enough. The goal is not to solve every problem in one sitting. The goal is to keep small issues from becoming large ones through consistent attention.
Another useful habit is the automatic transfer. Once a couple agrees on a realistic amount that can go toward high-interest debt each month, setting that transfer to happen the day after payday removes the need for repeated decisions. Willpower is finite. Systems that run without constant willpower tend to succeed more often.
Some couples also benefit from a visible progress tracker. A simple chart on the refrigerator that shows the balance of one targeted debt declining each month can turn an abstract goal into something both partners can see. Celebration of milestones—paying off the first $1,000, reaching the halfway point—keeps momentum alive when the remaining balance still looks large.
The Broader Context Without the Headlines
It is easy to treat survey results as distant abstractions. They are not. They describe the financial weather that millions of couples are walking through right now. The fact that the economy continued to expand while payment trouble worsened suggests that growth alone is not reaching every household in equal measure. Inflation, higher borrowing costs, and uneven income gains combined to create a more difficult environment for staying current on debt.
At the same time the modest narrowing of income inequality and the continued rise in overall net worth show that the picture is not uniformly bleak. Some families improved their position. The challenge is that improvement concentrated among those already further ahead. For couples starting further back, the same three years felt heavier.
I keep returning to that conversation with my friend and her stack of notices. She and her partner eventually sat down, listed every obligation, and built a plan that felt realistic. Progress has been slower than they hoped, yet the late notices have stopped arriving. That small shift restored a measure of calm to their evenings. Multiply that experience across the households now reflected in the nearly 20 percent figure, and the potential for both strain and recovery becomes clear.
The warning lights are on. They have not been this bright since the years immediately after the Great Recession. Couples who treat the data as useful information rather than distant news give themselves the best opportunity to adjust before temporary pressure hardens into lasting difficulty. Clear numbers, regular conversation, and a shared plan remain the most reliable tools available. They are not glamorous. They simply work.
Looking forward, the next survey will tell us whether the rise in delinquency proved temporary or marked the beginning of a longer period of household strain. Until then each couple retains the ability to influence its own small corner of the larger picture. That ability begins with facing the numbers honestly and deciding, together, what to do about them.