
Have you ever watched a long-standing isolation suddenly crack open right in front of the world’s cameras? That is exactly what unfolded this week when Russia’s finance minister took a seat at the G20 table in Bangkok. The invitation came from the United States, and the reaction from several European capitals was immediate and icy. I found myself pausing over the seating chart more than once. It felt less like routine diplomacy and more like a quiet stress test of alliances that have held firm for years.
The Quiet Return That Changed The Mood In The Room
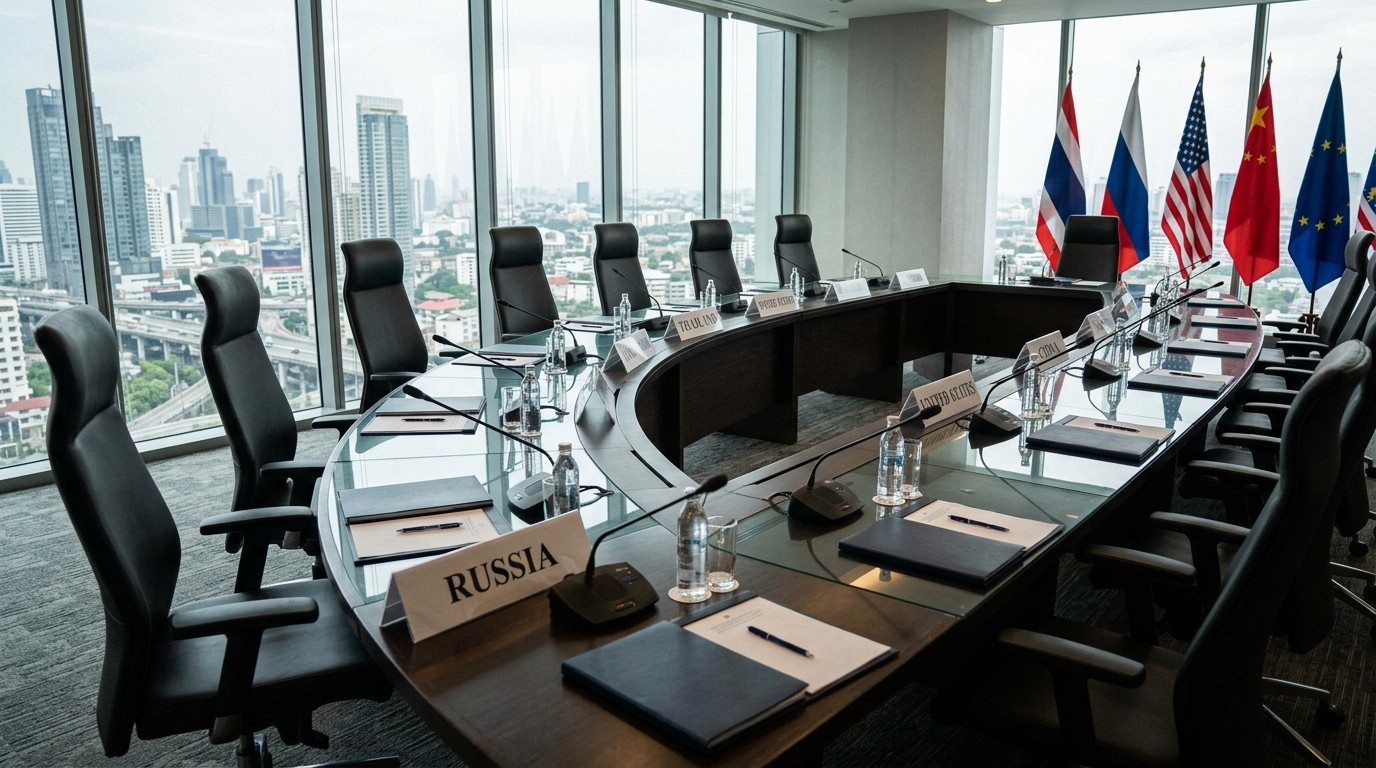
Anton Siluanov walked into the finance ministers and central bank governors meeting on the sidelines of the larger international gatherings in Thailand. Alongside him sat a deputy from the Russian central bank. Their names appeared on the official seating plan, placed between delegates from South Korea and the United Arab Emirates. That small detail mattered. It signaled that Russia was no longer standing outside the door.
This marked only the second time the Russian finance chief had attended in person since the full-scale invasion of Ukraine began. The previous appearance, held on American soil earlier in the year, had already caused friction. At that earlier gathering a group photo was carefully arranged without the Russian delegation after several European officials made their objections clear. One German minister had even spoken directly to Siluanov, insisting the war must end before normal relations could resume.
This time the same German minister was listed as present again. Yet the atmosphere remained strained. After the Bangkok session he reportedly made it plain that no one should pretend Russia was simply sliding back into the club as if nothing had happened. In my view, that comment captured the core tension better than any formal statement could.
Why The United States Chose This Moment
The current American administration holds the G20 presidency this year. Bringing Russia back into the finance track was a deliberate choice. Officials in Washington appear to believe that complete isolation has run its course and that limited engagement on economic issues might open channels for broader discussion. Whether that calculation proves wise remains an open question.
At the same time, a temporary arrangement allowing certain Russian energy products back into select markets until spring drew sharp criticism. Ukrainian leadership and several European governments made their disapproval public. One senior European official told reporters that easing pressure right now sends the wrong signal. The contrast between American openness and European caution could hardly be clearer.
I keep coming back to the practical side. Global energy markets remain tight. Public debt in many advanced economies sits at record levels. Coordinating responses to these pressures is harder when major players stay locked out of the room. Still, the human cost of the ongoing conflict cannot be set aside for the sake of smoother meetings. That balance is what makes this return so politically charged.
European Pushback And The Limits Of Rapprochement
European finance chiefs have spent years treating Russia’s presence as unacceptable while the war continues. Their position has not softened. The German minister’s refusal to treat the Bangkok attendance as a return to normalcy reflects a wider view shared across several capitals. They argue that allowing Moscow a seat without meaningful progress on the battlefield undermines the principle that aggression carries lasting consequences.
One Australian official used the post-meeting statement to link Russia’s actions in Ukraine with fresh instability in the Middle East. The message was straightforward: the war continues to amplify global economic risks. Calls for an end to the conflict and respect for Ukrainian sovereignty appeared once more. These points are not new, yet their repetition at every gathering shows how little common ground exists.
There will be no pretending that Russia is now returning as a normal member of the G20 and simply taking its seat at the table again.
That kind of language leaves little room for ambiguity. It also raises a practical problem for the American hosts. How far can Washington go in easing diplomatic isolation without fracturing the very partnerships it relies on for other priorities? The answer is still forming, and Bangkok offered an early, uncomfortable glimpse.
No Joint Statement And The Deeper Divisions
By the end of the day the finance chiefs left without a shared communique. That outcome was not entirely surprising. Similar meetings earlier in the year had already stumbled over disagreements involving trade imbalances, language around the Middle East, and the Ukraine conflict. When consensus proves impossible, the chair sometimes issues a separate summary. This time even that option stayed off the table.
The absence of a joint text itself becomes a signal. It tells markets and governments that the world’s major economies still cannot speak with one voice on the most pressing issues. For investors watching energy prices, currency moves, and debt sustainability, the lack of coordination is more than a diplomatic footnote. It shapes expectations about future policy responses.
Perhaps the most interesting aspect is how ordinary the meeting looked on the surface. Delegates began with a carefully plated breakfast featuring local ingredients. Name cards carried the American presidency logo and a slogan marking a national anniversary. Everything appeared orderly. Underneath, the seating arrangement and the missing communique told a different story.
What This Means For Global Economic Coordination
Finance ministers and central bankers usually use these sessions to compare notes on growth, inflation, and financial stability. This year the list of challenges feels longer than usual. Energy disruptions linked to regional conflicts continue to ripple outward. Advanced economies carry heavy public debt loads that limit fiscal room. Emerging markets watch capital flows with heightened caution.
Having every major economy represented can, in theory, improve the quality of those conversations. Russia remains a significant energy producer and a participant in certain commodity markets. Shutting that perspective out entirely creates blind spots. At the same time, treating the return as purely technical ignores the political reality that many governments still view Moscow as an aggressor state.
I’ve found that these tensions rarely stay confined to closed-door sessions. They spill into bilateral meetings, into public statements, and eventually into market sentiment. When European officials publicly distance themselves from American outreach, the perception of Western unity takes a quiet hit. Markets notice those cracks even when the official language stays measured.
- Persistent disagreement over how to handle Russia’s participation
- Failure to agree on language about ongoing conflicts
- Continued friction around trade imbalances and surplus economies
- Growing concern about energy market volatility
- Record public debt levels limiting policy flexibility
Each of these items would be difficult on its own. Together they explain why a single seating plan generated so much commentary.
Looking Ahead To The Leaders Summit
The next major gathering of G20 leaders is scheduled for December in an American city. That meeting will test whether the cautious re-engagement visible in Bangkok can survive the higher political temperature of a full leaders’ summit. Finance track discussions often serve as early indicators. If the same divisions reappear at the top level, the presidency will face a more public challenge.
Some observers argue that gradual reintegration is inevitable. Others insist that any normalization without concrete progress on the battlefield rewards aggression. Both sides can point to recent history for support. The United States appears to be testing the first path. Several European partners remain firmly on the second.
In practical terms, the coming weeks will show whether the Bangkok attendance becomes a one-off experiment or the start of a new pattern. Watch for further statements from European capitals. Watch also for any adjustment in the American approach. Markets will parse every signal for clues about sanctions policy, energy trade, and the broader direction of Western coordination.
The Human And Political Stakes Behind The Seating Chart
It is easy to treat these meetings as abstract exercises in protocol. They are not. Behind every nameplate sits a government that must answer to its own public. For countries that have supplied weapons, imposed sanctions, and welcomed refugees, the idea of Russia simply reclaiming a seat feels premature at best and offensive at worst. For others focused primarily on commodity prices and growth numbers, the political symbolism matters less than the practical conversation.
That gap in priorities is what makes the current moment so awkward. The American hosts clearly hope that limited engagement can create space for progress on shared economic risks. European partners fear that the gesture itself weakens the collective stance. Neither side is entirely wrong. Both are operating under real constraints.
One detail that stayed with me was the simple fact that the traditional group photograph has become a political act. In an earlier meeting the photo was taken without the Russian delegation. In Bangkok the seating plan itself became the story. When something as basic as who sits where generates headlines, you know the underlying disagreement runs deep.
Broader Implications For International Economic Forums
The G20 was never designed as a security alliance. It exists to coordinate economic policy among the world’s largest economies. Yet security questions keep invading the economic agenda. When a major member remains locked in a high-intensity conflict with a neighboring state, every discussion about trade, energy, or debt carries an extra layer of tension.
Other international bodies have faced similar dilemmas. Some have chosen continued isolation. Others have experimented with limited technical engagement. The results have been mixed. Pure isolation can reduce certain forms of cooperation that still serve mutual interests. Full normalization without conditions can undermine the credibility of earlier measures. Finding a middle path is harder than it sounds.
In this case the American decision to invite Russia back into the finance track represents one possible middle path. Whether it holds will depend on events far outside the meeting rooms in Bangkok. Battlefield developments, energy market shocks, and domestic political pressures in multiple capitals will all influence the next steps.
I keep wondering how long the current arrangement can last. If the conflict remains unresolved, European resistance is unlikely to fade. If conditions on the ground shift, the political space for engagement could expand. Right now neither scenario looks imminent. That leaves the G20 stuck in an uncomfortable holding pattern.
Market Reactions And Quiet Calculations
Financial markets tend to look past the diplomatic theater and focus on concrete outcomes. The lack of a joint communique itself carries limited direct market impact. What matters more is any signal about future sanctions policy, energy trade rules, or coordinated fiscal responses. So far those signals remain mixed.
Energy traders will watch closely for any further easing of restrictions on Russian products. Currency markets will track whether the broader Western approach to Russia stays unified or begins to fragment. Debt markets already price in elevated uncertainty; another layer of geopolitical noise does not help.
From an investor perspective the episode reinforces a familiar lesson. Geopolitical risk is no longer a distant backdrop. It sits inside the meeting rooms where economic policy is discussed. Ignoring the political dimension of these gatherings is no longer realistic.
A Test Of Alliance Cohesion
Perhaps the most lasting effect of the Bangkok meeting will be the quiet strain it placed on transatlantic coordination. The United States and its European partners still share broad strategic goals. They differ, however, on the tactical question of how and when to re-engage with Russia on economic issues. Those differences are manageable for now. They become more costly if they harden into public disagreement at every major forum.
Alliance management has always required careful balancing. One partner may prefer dialogue while another insists on continued pressure. The current American approach leans toward testing limited engagement. Several European governments prefer to keep the pressure high. Bridging that gap will require more than clever seating arrangements.
In the end the story is not only about one finance minister returning to a conference table. It is about whether the world’s major economies can still find ways to talk when they disagree on fundamental questions of war and peace. Bangkok showed both the possibility of conversation and the depth of the remaining divide.
The coming months will reveal which of those two realities proves stronger. For now the image that lingers is simple: a nameplate on a table, a missing joint statement, and a set of allies who no longer sound entirely in sync. That combination should keep policymakers, markets, and observers watching closely.
Diplomacy rarely moves in straight lines. This particular turn feels especially sharp. Whether it leads toward gradual reintegration or simply underscores how far apart the parties remain is a question that will be answered outside the meeting rooms, on battlefields and in capital cities far from Bangkok. Until then, the G20 will continue to function under the shadow of a conflict that refuses to stay in its lane.
One final thought stays with me. International forums exist to manage differences, not to erase them. The fact that Russia’s presence still generates such strong reactions years into the conflict shows how deeply the original decisions about isolation still resonate. Changing those decisions, even partially, was never going to be quiet or easy. Bangkok made that reality impossible to ignore.