
Something feels different this time. When a senior Iranian official publicly announces that the armed forces have prepared a response far more devastating than previous conflicts, and at the same time commercial vessels start reporting direct hits near some of the world’s busiest shipping lanes, the market does not stay calm for long. Oil prices already reacted sharply. I have been watching these developments closely, and the combination of military rhetoric and actual maritime incidents creates a level of uncertainty that traders and energy analysts cannot ignore.
Iran Signals A New Kind Of Response
Mohsen Rezaei, who serves as secretary of Iran’s Supreme National Security Council, made the statement on Sunday. He said the country’s military has prepared a response to any new act of adventurism by the United States and Israel. According to him, this new operational plan would not follow the rules with which they are familiar. The wording is deliberate. It suggests that previous patterns of engagement may no longer apply.
Rezaei referred to earlier periods of conflict, describing the potential new response as far more devastating than the 12-day and 40-day wars of recent memory. Those earlier episodes already disrupted regional stability and sent energy markets into periods of elevated volatility. A plan that deliberately avoids familiar rules raises the stakes even higher.
In my view, the language chosen here is meant to create strategic ambiguity. It does not specify targets or methods. Instead, it leaves room for interpretation while signaling readiness. Markets hate ambiguity almost as much as they hate clear escalation. That is why the statement landed with weight.
What The Official Statement Actually Conveys
The core message is straightforward. Iran claims it has prepared for renewed military pressure. The response would be more severe than past confrontations. And it would operate outside the expected playbook. These three elements together form a deliberate warning.
At the same time, Iranian foreign ministry voices have indicated a willingness to keep diplomatic channels open. The country maintains it will not surrender sovereign rights under pressure, yet it remains ready for dialogue. This dual track of firmness and openness is familiar in regional diplomacy. Still, the military side of the message currently dominates headlines.
Iran’s new operational plan will not follow the rules with which they are familiar.
That single sentence has already been dissected by analysts. Some interpret it as a reference to asymmetric tactics. Others see it as a broader signal that escalation ladders may look different this time. Either way, the market is pricing in higher risk.
Recent Context From Leadership Comments
Just days earlier, President Donald Trump stated that he does not intend to use nuclear weapons against Iran and does not foresee deploying ground troops. He described the United States as the greatest nuclear power and indicated that such weapons would not be necessary. Questions had circulated about potential use of large conventional munitions, yet the public stance remained measured on those specific points.
These comments arrived against a backdrop of ongoing regional friction. The contrast between restrained language from one side and heightened operational rhetoric from the other creates a complex information environment. Investors trying to assess the probability of further escalation have limited clear signals.
Shipping Vessels Report Multiple Incidents
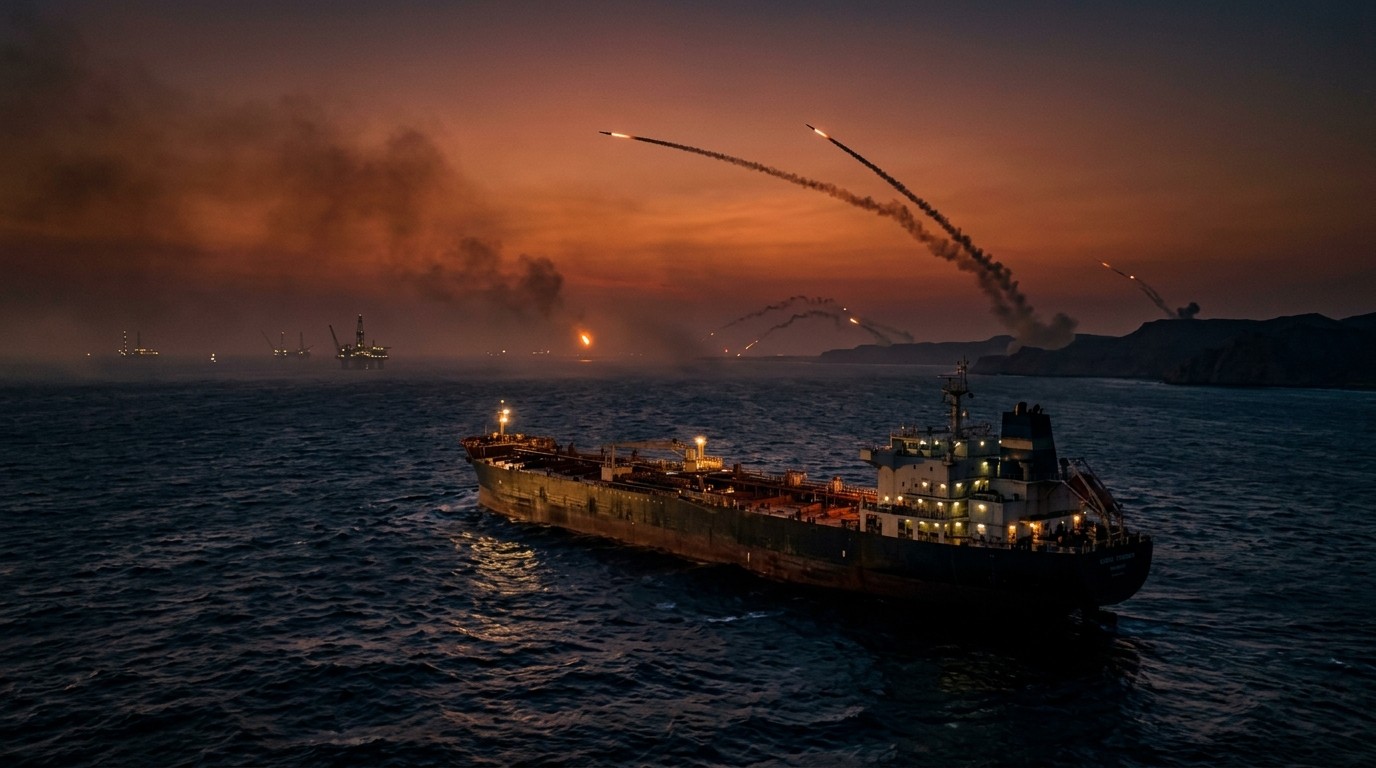
While official statements focused on potential future responses, actual incidents were already occurring at sea. Maritime authorities recorded several separate attacks on commercial vessels operating around the Arabian Peninsula in recent days. These reports arrived from the British Navy-affiliated United Kingdom Maritime Trade Operations Centre and painted a picture of elevated risk for commercial shipping.
On Sunday a tug traveling south northeast of the United Arab Emirates was hit by two unknown projectiles. The vessel was operating in waters that form part of critical energy transit routes. Damage assessments and the exact nature of the projectiles were not immediately detailed in public summaries, yet the fact of the strike itself raised immediate concern.
The day before, the master of a liquefied natural gas tanker southwest of Yemen reported being approached by a small skiff carrying seven persons. The skiff fired twice. The tanker’s security team responded with two warning shots. The encounter ended without further reported escalation, but it demonstrated that even large energy carriers remain potential targets for small boat operations.
On Friday another tanker northeast of Saudi Arabia reported being hit by a rocket-propelled grenade fired from a small boat. These three incidents, occurring across different locations within a short window, suggest a pattern rather than isolated events.
- Tug hit by two unknown projectiles near the United Arab Emirates
- LNG tanker approached by armed skiff southwest of Yemen
- Tanker struck by rocket-propelled grenade northeast of Saudi Arabia
Each of these events adds friction to already sensitive maritime corridors. Insurance costs for vessels operating in the region have risen in previous periods of heightened risk. Charter rates can also move quickly when operators become more cautious. The cumulative effect is higher transportation costs that eventually filter into energy pricing.
Saudi Arabia Intercepts Missiles And Drones
Saudi Arabia reported its own defensive actions over the same period. Military spokesmen stated that several missiles fired over the Red Sea were intercepted on Friday. One of those missiles had been heading toward the oil export terminal at Yanbu. Three drones were also destroyed in the kingdom’s Riyadh and southern regions.
Iran-allied Houthi militants in Yemen had repeatedly fired at Saudi Arabia in the preceding days. The kingdom’s energy ministry confirmed that oil giant Aramco came under attack when militants hit one of its administrative buildings in Dhahran on Tuesday. Although the strike targeted an administrative structure rather than production facilities, any attack on energy infrastructure assets tends to heighten market sensitivity.
I find the timing of these incidents particularly notable. They coincide with the Iranian official’s public warning about a new operational plan. Whether coordinated or parallel, the combination of rhetoric and kinetic activity keeps risk premiums elevated.
Oil Prices React With Sharp Gains
Energy markets did not wait for further clarification. Brent crude futures climbed sharply on Friday amid rising tensions. Prices hit a session high of 110 dollars per barrel for the first time since May before settling at 109.86 dollars, a gain of 3.7 percent. U.S. West Texas Intermediate rose 3.5 percent to settle at 101.41 dollars per barrel.
Looking at the weekly picture, WTI added more than 10 percent while Brent advanced nearly 5 percent. These moves reflect both the immediate incidents and the broader uncertainty created by official statements. When shipping lanes face disruption risk and major producers sit near potential flashpoints, traders often move quickly to price in supply concerns.
Perhaps the most interesting aspect is how quickly the market can reprice when maritime incidents and military rhetoric arrive together. Previous episodes of regional tension have shown that even temporary threats to transit routes can produce lasting effects on inventory strategies and hedging behavior.
| Benchmark | Friday Close | Daily Change | Weekly Move |
| Brent Crude | $109.86 | +3.7% | Nearly +5% |
| WTI Crude | $101.41 | +3.5% | More than +10% |
These numbers matter beyond the trading screens. Higher crude prices feed into refined product costs, transportation expenses, and broader inflation measures. For economies still navigating post-pandemic recovery dynamics and varying monetary policy paths, an extended period of elevated energy costs creates additional pressure.
Why Maritime Routes Matter So Much
The waters around the Arabian Peninsula and the Red Sea carry a substantial share of global oil and liquefied natural gas shipments. Disruptions in these corridors do not need to be complete blockades to affect pricing. Even intermittent attacks or credible threats can force vessels to slow transit, alter routes, or increase security measures. Each of those adjustments carries cost.
When a tug is hit by projectiles, an LNG carrier faces armed skiffs, and a tanker absorbs a rocket-propelled grenade strike, operators reassess risk calculations. Some may choose longer routes that avoid the highest risk zones. Others may demand higher insurance coverage. Both outcomes reduce effective capacity and support higher freight rates.
In my experience following these markets, the psychological component often proves as important as the physical one. Once the perception of elevated danger takes hold, it can persist even after specific incidents decline. That persistence keeps risk premiums in place longer than pure supply data might suggest.
Broader Regional Security Dynamics
The current situation sits inside a longer pattern of friction. Previous periods of direct and indirect confrontation have already demonstrated how quickly local incidents can acquire wider significance. Proxy activity, missile and drone exchanges, and maritime harassment have all featured in recent years.
What distinguishes the latest developments is the explicit reference to a new operational plan that deliberately steps outside familiar rules. Combined with simultaneous reports of vessel strikes and defensive interceptions, the information flow creates a denser sense of unpredictability.
Saudi Arabia’s interception of missiles heading toward an oil export terminal underscores the potential economic stakes. Yanbu is not a minor facility. Any credible threat to major export infrastructure tends to focus attention on supply reliability. Even successful interceptions leave residual uncertainty about future attempts.
Market Implications Beyond The Immediate Spike
Short-term price spikes attract the most attention, yet the secondary effects often prove more lasting. Refiners adjust run rates when feedstock costs rise rapidly. Airlines and shipping companies face higher fuel expenses. Manufacturers that rely on petrochemical inputs see cost pressures. Central banks monitoring inflation data must weigh whether energy moves represent temporary noise or a more persistent shift.
Inventory levels and strategic reserves provide some buffer, yet they do not eliminate the need for continuous commercial flows. When those flows face elevated risk, the system absorbs the cost through higher prices or reduced flexibility.
I have found that periods of geopolitical stress in energy-producing regions frequently produce two phases of market reaction. The first is the immediate risk premium. The second is a more gradual reassessment of supply chain resilience and diversification strategies. The current episode appears to be moving through the first phase. Whether it triggers the second depends on how events evolve in the coming weeks.
The Role Of Ambiguity In Deterrence And Markets
Strategic ambiguity serves a purpose in military signaling. It complicates an adversary’s planning by expanding the range of possible responses. For financial markets, the same ambiguity expands the range of possible outcomes that must be considered. Scenario analysis becomes wider. Probability weightings grow more uncertain. Position sizing often turns more conservative.
When an official states that a new operational plan will not follow familiar rules, market participants must consider a broader set of contingencies. That process alone can support higher risk premiums even before any new action materializes.
At the same time, the parallel diplomatic messaging about readiness for dialogue provides a counterbalancing signal. Markets tend to assign some probability to de-escalation pathways when such language appears. The net effect is a more volatile pricing environment rather than a simple one-directional move.
Looking At The Shipping Data More Closely
The three reported vessel incidents share certain characteristics. They involved commercial rather than military targets. They occurred in different sectors of the waters surrounding the Arabian Peninsula. And they employed relatively low-cost methods: unknown projectiles, small skiffs, and rocket-propelled grenades. This pattern of low-cost, distributed pressure has appeared in previous periods of regional tension.
Such tactics complicate defensive planning. Large warships and advanced air defenses are optimized for higher-end threats. Small boat attacks and limited projectile strikes require different layers of protection and different rules of engagement. Commercial vessels often rely on private security teams and coordinated naval awareness systems. Those systems work, yet they cannot eliminate every risk.
The LNG tanker incident is particularly instructive. The vessel’s security team responded with warning shots after the skiff fired. The encounter de-escalated. Still, the fact that an energy carrier of that size faced an armed approach in open waters illustrates the residual vulnerability of commercial traffic.
Energy Infrastructure As A Focal Point
Attacks or attempted attacks on energy-related targets carry outsized market impact. The strike on an Aramco administrative building in Dhahran, the missile trajectory toward the Yanbu terminal, and the broader pattern of Red Sea activity all touch the energy sector directly or indirectly. Even when physical production remains largely unaffected, the perception of vulnerability influences pricing.
Major producers in the region have invested heavily in defensive systems and operational redundancy. Those investments have limited the physical damage from previous incidents. Markets nevertheless continue to assign a geopolitical risk premium because the possibility of more significant disruption cannot be ruled out entirely.
This dynamic has become a structural feature of oil pricing over the past decade. Geopolitical risk no longer appears only during acute crises. It remains a background factor that rises and falls with the intensity of regional messaging and activity.
Potential Pathways Forward
Several paths remain open. Continued low-level maritime incidents could keep risk premiums elevated without producing a major supply shock. A period of reduced activity combined with diplomatic engagement could allow prices to ease from recent highs. Alternatively, a significant escalation involving larger-scale operations would likely produce a sharper and more sustained price response.
The Iranian reference to a new operational plan that avoids familiar rules introduces an additional variable. If that plan involves methods or targets outside previous patterns, market models calibrated on historical episodes may understate the potential impact. Conversely, if the statement primarily serves deterrent purposes and activity remains limited, the market may gradually adapt to a higher but stable risk environment.
I tend to watch two indicators particularly closely in situations like this. The first is the frequency and severity of maritime incidents. The second is the tone and specificity of official statements from all involved parties. When both move in the same direction, pricing usually follows. When they diverge, volatility often increases as participants struggle to assign clear probabilities.
Implications For Broader Market Sentiment
Energy markets do not operate in isolation. Sharp moves in crude prices influence equity sectors, currency pairs of energy exporters and importers, and inflation expectations that feed into fixed income markets. A sustained period of elevated oil prices can complicate the policy calculus for central banks that have been focused on bringing inflation back toward target levels.
Equity investors with exposure to energy producers may view the current environment as supportive for that sector. Those with heavy exposure to energy-consuming industries may see rising cost pressures. Portfolio managers often rebalance risk allocations when geopolitical premiums expand, reducing overall risk appetite in some cases and rotating toward perceived safe havens in others.
The speed of the recent price advance also matters. Rapid moves can trigger stop-loss orders, margin adjustments, and forced repositioning that amplify short-term volatility. Once those technical factors settle, the underlying fundamental and geopolitical drivers reassert themselves.
Historical Parallels And Their Limits
Previous episodes of tension in the same region have produced a range of market outcomes. Some led to temporary spikes that faded within weeks. Others contributed to more prolonged periods of elevated prices. The difference often lay in the duration of disruption risk and the degree to which physical supply was actually constrained.
The current combination of explicit new operational planning language and concurrent maritime incidents sits somewhere in the middle of that historical spectrum. It is more than pure rhetoric, yet it has not so far produced major supply losses. That intermediate status leaves markets in a state of heightened alert without clear resolution.
One lesson from earlier periods is that the market’s capacity to absorb geopolitical risk can expand over time if the risk becomes familiar. What begins as a sharp premium can gradually become a more stable component of the price. Whether that process occurs this time depends on the evolution of both the military and diplomatic tracks.
Practical Considerations For Market Participants
Participants with direct exposure to energy prices face immediate decisions about hedging ratios and position sizes. Those further downstream in the energy value chain must assess the potential pass-through of higher costs. Broader investors need to consider second-order effects on inflation, growth, and sector relative performance.
Scenario planning becomes more valuable when the range of possible outcomes widens. Mapping a base case of continued low-level friction, an upside case of successful de-escalation, and a downside case of significant escalation helps clarify risk tolerances. The official reference to unfamiliar rules makes the downside case harder to quantify with precision.
Communication between commercial operators, insurers, and security providers in the maritime domain will likely intensify. Higher awareness and faster information sharing can reduce the probability of successful attacks, yet they cannot eliminate residual risk entirely.
The Human And Economic Dimensions
Behind the price charts and official statements sit real economic consequences. Higher energy costs affect household budgets, industrial competitiveness, and fiscal balances in importing nations. For exporting nations, elevated prices can provide revenue support, yet the accompanying security costs and investment uncertainty create their own challenges.
Crews aboard commercial vessels operating in the affected waters face elevated personal risk. Security teams must remain on constant alert. Shipping companies must balance commercial schedules against safety considerations. These human factors rarely appear in market summaries, yet they form part of the operational reality that ultimately influences costs and availability.
I believe it is worth remembering that markets ultimately reflect collective assessments of risk and reward. When those assessments shift rapidly, prices move. The current shift has been driven by a clear increase in the perceived probability of further disruption. How long that perception remains elevated will determine the duration of the current premium.
Monitoring The Next Phase
In the days and weeks ahead, attention will focus on several indicators. Further maritime incident reports will either reinforce or ease current concerns. Additional statements from Iranian officials or responses from other parties will shape the narrative around the new operational plan. Defensive activity by regional states will provide evidence of the ongoing threat level.
Oil inventory data, tanker tracking information, and freight rate movements will offer quantitative measures of any actual disruption to flows. Equity and currency markets will reveal how broader risk appetite responds to the energy price path.
The situation remains fluid. A single significant incident or a clear diplomatic breakthrough could shift the balance quickly. Until then, the combination of military signaling and maritime activity keeps the risk premium in place and the market on edge.
What stands out most is the deliberate framing of the Iranian statement. By emphasizing that the new plan will not follow familiar rules, the message expands the uncertainty set. Markets can price known risks with some confidence. Unknown or unfamiliar risks tend to command higher premiums. That dynamic is currently on full display.
The coming period will test whether the current tension settles into a manageable elevated baseline or moves toward more significant disruption. Energy markets, shipping operators, and policymakers will all be watching the same signals. For now, the price action has already delivered a clear verdict on the immediate rise in perceived risk.
As developments continue, the interaction between official rhetoric, actual incidents at sea, and market pricing will remain the central story. The new operational plan language has raised the stakes. The vessel attacks have demonstrated that risk is not purely theoretical. Together they have produced a market environment that demands careful monitoring and disciplined risk management.