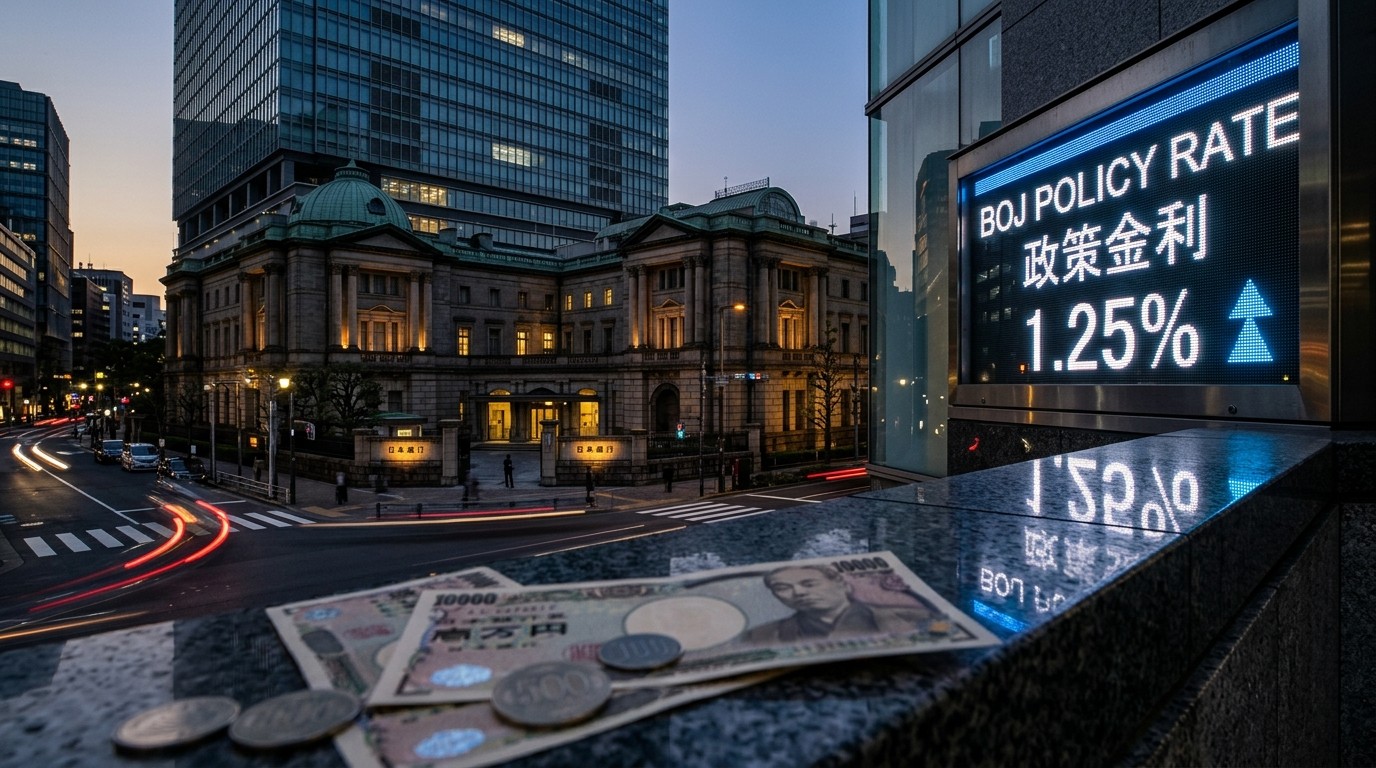

I’ve been watching the Bank of Japan for years, and this week feels like one of those quiet moments that can still move markets more than people expect. After raising rates last month to the highest level in three decades, almost everyone now believes the central bank will pause. Yet the same people are equally convinced that the pause will be temporary. That combination of near-term caution and medium-term determination is what makes the current situation so interesting.
What The Latest Survey Tells Us About The Coming Decision
Every single participant in a recent survey of sixteen economists and analysts expects the policy rate to remain at 1.25 percent when the two-day meeting ends on Friday. No one is calling for an immediate move. That unanimity is rare. At the same time, every respondent also anticipates another increase either in December or January. The message is clear: the Bank of Japan is not finished tightening, but it wants a bit more evidence before acting again.
This stance makes sense when you look at the recent data. Core inflation excluding fresh food climbed to 2.1 percent in September, the highest reading this year. A weak yen continues to push up import costs, while energy prices remain elevated even after government subsidies soften the blow for households. Real wages have now risen for eight consecutive months, gaining 1.5 percent in August. That combination of rising prices and improving pay is exactly what the central bank has been waiting for.
Still, the path is not straightforward. Domestic bond markets have shown some fragility, and successive hikes could test that stability. Several strategists note that while the macroeconomic case for further tightening is solid, the policy board may prefer to move carefully rather than in rapid succession.
Inflation And Wages Keep The Hawkish Case Alive
The latest inflation numbers matter more than the headline might suggest. Reaching 2.1 percent is not just another data point. It shows that price pressures are broadening beyond temporary factors. Higher import costs linked to the yen’s earlier weakness are feeding through, and energy remains expensive. Government support has limited the impact on consumers, yet the underlying trend is still upward.
Wage growth provides the more structural story. After years of stagnation, inflation-adjusted pay is finally rising on a sustained basis. Eight months in a row is hard to dismiss. Finance Minister comments last week captured the shift well: Japan appears to be moving toward a period in which wage gains themselves help drive inflation rather than simply reacting to external cost pressures. That transition, if it holds, would represent a meaningful change for an economy long accustomed to falling or flat prices.
In my view, this dual picture of sticky inflation and improving labor compensation is the strongest argument for further policy action. The Bank of Japan has spent years trying to escape the old low-inflation equilibrium. Data like this suggests the escape may finally be underway.
The Yen Outlook Remains Complicated
Currency markets are watching closely. Nine of the sixteen survey respondents expect the yen to trade between 157 and 158 against the dollar over the next month. The three-month forecasts are more dispersed, stretching from 150 to 160. That spread reflects genuine uncertainty about how quickly interest rate differentials will narrow.
Higher domestic yields and gradual policy normalization should eventually encourage capital to flow back toward Japanese assets. Institutional investors that have kept large positions overseas may begin to rethink those allocations. At the same time, elevated yields in the United States continue to support the dollar. A straight-line appreciation of the yen looks unlikely in the near term. Safe-haven demand can still produce sharp moves, as seen last week when equity market volatility briefly lifted the currency and pulled Japanese government bond yields lower.
Perhaps the most interesting aspect is the interplay between policy signaling and market positioning. If the Bank of Japan uses this week’s statement to strengthen its language around inflation, the yen could respond even without an immediate rate change. Traders will be listening carefully for any shift in the description of underlying price pressures.
Bond Yields Point To Higher Levels Ahead
Japanese government bond markets have already started pricing in a more determined central bank. The ten-year yield currently sits near 2.8 percent. Nine survey respondents expect it to finish the year between 3.0 and 3.1 percent. The thirty-year yield, now around 3.8 percent, is forecast by seven respondents to reach the 4.0 to 4.1 percent range. Those moves would be significant in a market long known for ultra-low rates.
The expectation of resumed tightening after the October pause is the main driver. When the Bank of Japan eventually raises rates again, longer-term yields should continue to grind higher. That process will not be linear. Global risk sentiment, U.S. Treasury moves, and domestic demand for bonds will all influence the path. Yet the direction of travel looks clear to most analysts.
I’ve found that investors sometimes underestimate how sensitive Japanese yields remain to policy communication. Even modest changes in the official outlook can shift the curve. This week’s statement therefore carries weight beyond the immediate decision to hold rates steady.
When Might The Next Rate Increase Arrive
Timing is the open question. Some economists lean toward December. Others prefer January, when the central bank releases its next quarterly outlook report. That document provides a natural opportunity to update economic and price projections and to justify further action. January also allows additional time to observe wage negotiations and incoming inflation prints.
There is broad agreement that consecutive hikes are not guaranteed. The policy board appears mindful of bond market stability and the broader economic backdrop. A measured pace remains the more likely approach. Still, the fact that every survey participant sees another increase within the next few months is noteworthy. The pause this week is not viewed as the end of the cycle.
Looking further ahead, thirteen respondents place the terminal rate somewhere between 1.75 and 2.0 percent, reached around the middle of 2027. That range sits close to many estimates of neutral. One senior economist argued that the current policy rate is already approaching the level consistent with the two-percent inflation target, yet the economy’s overall condition still argues for stopping short of a full two percent. An eventual ceiling near 1.75 percent feels realistic to several observers.
Why The Pause Makes Sense Right Now
Raising rates last month already marked a historic step. Moving again so quickly could risk over-tightening just as the data is still settling. The Bank of Japan has repeatedly emphasized the importance of confirming that inflation is becoming more durable and wage-driven. Waiting a meeting or two provides that confirmation without abandoning the broader normalization path.
Bond market conditions also favor caution. Fragility in domestic fixed income has been noted by several strategists. Successive increases might amplify volatility at a time when the central bank would prefer orderly adjustment. By holding steady this week, officials can observe market reactions and gather more information before deciding on the next move.
In my experience following these meetings, the communication around the decision often matters as much as the decision itself. A carefully worded statement that acknowledges progress on inflation while leaving the door open for further action would align with the survey consensus and with the data trajectory.
Broader Implications For Global Markets
The Bank of Japan’s gradual shift away from ultra-loose policy carries consequences beyond Japan. Higher Japanese yields can influence global capital flows. Investors who borrowed in yen to fund positions elsewhere may gradually reduce those trades as the interest rate differential narrows. That process has already begun in modest form and could accelerate if the central bank continues tightening.
Equity markets, particularly those sensitive to currency moves, will also take note. A stronger yen over time can pressure exporters, while a weaker yen has historically supported them. The current expectation of only gradual yen appreciation suggests that this pressure will build slowly rather than arrive overnight. Still, portfolio managers are already adjusting assumptions about Japanese assets.
Commodity markets and emerging currencies sometimes feel secondary effects as well. When one of the world’s largest pools of savings begins to reprice risk and return, the ripples travel far. This week’s meeting is unlikely to produce dramatic headlines, yet it forms part of a longer transition that markets will continue to digest for years.
What Investors Should Watch Closely
Several concrete items deserve attention in the coming days and weeks. First is the exact language in the monetary policy statement. Any change in how officials describe underlying inflation will be scrutinized. A move from “approaching” two percent to “reaching” or “around” two percent would signal greater confidence.
Second, the governor’s press conference remains essential. Tone, emphasis, and answers to specific questions about the timing of future hikes often move markets more than the formal decision. Third, incoming data on wages and prices will shape expectations for the December and January meetings. Strong readings would reinforce the case for action; softer numbers could push the timeline out.
- Policy statement wording on inflation
- Governor’s comments during the press conference
- Upcoming wage and price data releases
- Japanese government bond market reaction
- Yen trading range over the following sessions
These markers will help investors gauge whether the consensus view of a December or January hike remains on track.
Historical Context Helps Frame The Moment
It is easy to forget how unusual the current rate level still is for Japan. For many years the policy rate sat near zero or even in negative territory. Last month’s increase to 1.25 percent marked the highest setting in thirty-one years. That fact alone underscores the scale of the shift already underway. A further rise later this year or early next year would continue a process that once seemed almost unimaginable.
The journey has been deliberate. Officials have stressed the need to avoid premature tightening that could choke off the recovery in prices and wages. They have also been careful about the pace of balance-sheet adjustment. The current pause fits that patient approach. It does not signal doubt about the broader direction.
Looking back, the combination of sustained wage gains and core inflation near the target is precisely the environment the Bank of Japan hoped to create. Reaching this point has taken longer than many expected. Maintaining progress will require continued vigilance, which is why the survey respondents remain confident about further increases even while endorsing a hold this week.
Potential Risks That Could Alter The Path
No forecast is without risks. A sharper-than-expected slowdown in global growth could dampen Japanese exports and weaken domestic demand. Renewed volatility in bond markets might make the policy board more cautious. Conversely, a stronger surge in wages or a further jump in inflation could pull the next hike forward.
Currency moves themselves create feedback loops. A significantly weaker yen would intensify import-driven inflation and potentially accelerate the need for tighter policy. A rapid strengthening could ease price pressures and give the central bank more room to wait. These dynamics explain why the three-month yen forecasts remain so widely dispersed.
Political developments and fiscal policy choices also matter. Spending plans can influence growth and inflation trajectories, while the overall economic strategy of the government interacts with monetary decisions. Officials will be mindful of these broader conditions as they calibrate the next steps.
How The Terminal Rate Debate Is Evolving
The discussion around the eventual peak in rates has become more concrete. Most survey participants see the cycle ending in the 1.75 to 2.0 percent range. That estimate reflects a balance between the desire to anchor inflation near the target and the need to avoid excessive restraint on growth. Japan’s economy still carries structural features that differ from those of other major economies. Neutral rate estimates remain subject to debate, yet the emerging consensus provides a useful reference point for markets.
Reaching that terminal level around mid-2027 implies a measured path of increases rather than a rapid series of moves. Such a pace would allow the Bank of Japan to assess the impact of each step before taking the next one. It would also give households, companies, and financial institutions time to adjust to higher borrowing costs after decades of ultra-low rates.
In my view, the gradual approach is appropriate. The goal is not simply to raise rates but to establish a sustainable regime in which inflation stays near two percent without constant policy support. Achieving that outcome requires patience as much as determination.
Practical Considerations For Portfolio Positioning
Investors with exposure to Japanese assets face a shifting landscape. Higher local yields improve the attractiveness of domestic bonds relative to the recent past, though they remain low by global standards. Currency hedging costs and expected yen moves will influence total returns for foreign holders. Equity investors need to weigh the benefits of stronger domestic demand against potential pressure on exporters from any sustained yen appreciation.
Global portfolios that have relied on yen funding for carry trades should continue monitoring interest rate differentials. As those gaps narrow, the economics of such positions change. Even gradual policy normalization can produce cumulative effects over multiple quarters.
Diversification remains useful. The Japanese market offers characteristics that differ from those of the United States or Europe. As policy continues to evolve, those differences may become more pronounced rather than less. Staying informed about the data and the communication from Tokyo will help investors adapt as the cycle progresses.
The Bigger Picture Of Policy Normalization
What is unfolding at the Bank of Japan is part of a longer global story. After years of extraordinary monetary accommodation, major central banks have been adjusting to a world of higher inflation and tighter labor markets. Japan’s journey began later and has proceeded more carefully, reflecting its unique history of deflation and demographic challenges. The current phase represents meaningful progress along that path.
Success will ultimately be measured by whether inflation settles near the two-percent target in a self-sustaining way. Wage growth that supports demand without triggering excessive price spirals would be an important marker. Stable financial conditions during the transition would be another. The pause expected this week gives officials a chance to evaluate both.
I remain constructive on the broader direction. The data has moved in the right way. The policy board has shown a willingness to act when the evidence supports action. Holding rates steady now does not erase that progress. It simply allows a more deliberate assessment of the next appropriate step.
Looking Ahead To The Coming Months
Between now and the end of the year, several data releases and events will shape expectations. Wage negotiations in the spring will provide further insight into the durability of income gains. Inflation prints will show whether the recent uptick continues or moderates. Global financial conditions will influence the yen and domestic yields. Each of these elements will feed into the Bank of Japan’s deliberations.
The survey consensus of a hike in December or January sets a clear benchmark. If the data cooperates, that timeline looks achievable. If surprises emerge, the calendar can shift. Either way, the central bank has established a framework that prioritizes confirmation of the inflation and wage trends it has long sought. That framework is likely to guide decisions for the remainder of the tightening cycle.
Markets will continue to price the evolving outlook. Volatility around meetings and data releases is normal. Over a longer horizon, the gradual rise in Japanese rates and the associated adjustment in the yen and bond yields form part of a structural change that investors cannot ignore.
Final Thoughts On A Careful But Determined Path
The expected decision to hold rates this week is neither a surprise nor a setback. It is a logical pause after last month’s historic increase. The real story lies in the near-universal expectation of further action in the months ahead and in the data that supports that view. Inflation is running near the target. Wages are rising. The policy board retains the flexibility to respond as conditions evolve.
For anyone following global markets, the Bank of Japan’s next steps matter. They influence currency dynamics, capital flows, and the relative attractiveness of Japanese assets. They also represent a rare case of a major central bank still in the process of exiting an ultra-accommodative stance. Watching how officials balance caution with determination will remain worthwhile.
I’ve found that these periods of quiet confirmation often prove more important than the dramatic meetings. By pausing now, the Bank of Japan can strengthen the foundation for the moves that still lie ahead. The survey results suggest that foundation is already solid. The coming months will show whether the data continues to cooperate and how quickly the next increase arrives.
In the end, the combination of a near-term hold and a medium-term hawkish bias looks well calibrated to the current environment. Markets that understand this balance will be better positioned for the adjustments that follow. The story is still unfolding, and the next chapters will be written by the data and by the careful choices of policymakers in Tokyo.