
I was scanning the closing numbers late yesterday and one thing kept jumping out. The market finished higher, the Dow climbed more than 140 points, yet underneath that surface calm a whole collection of stories is lining up that could easily change the tone in the next session. Consumer companies are about to open their books, technology names continue to show cracks after sharp pullbacks, energy stocks just printed fresh highs, and a couple of overseas elections are still settling. In my view this mix creates one of those sessions where selective buying and careful risk management matter more than broad market direction.
What Stands Out Ahead Of The Next Trading Day
The consumer remains the quiet center of attention. We are about to hear directly from companies that sell food, beverages, and vacation experiences. Hormel Foods has struggled lately. Shares sit roughly 17 percent lower over the past three months and about 21 percent below the June peak. The chief executive is scheduled to appear on morning television, which often brings fresh commentary on pricing power, volume trends, and how households are adjusting their grocery baskets. I have found that these conversations sometimes reveal more than the formal earnings release itself.
Coca-Cola sits at the opposite end of the recent performance spectrum. The stock has advanced nearly 13 percent in three months and recently touched a new high. Results arrive in the morning. Investors will parse volume growth, pricing actions in key international markets, and any comments on input costs. A solid print could reinforce the idea that certain branded consumer names still command loyalty even when budgets feel tighter. A softer report might raise questions about whether the recent rally has already priced in too much optimism.
Royal Caribbean adds the travel and leisure angle. Shares are down about 4 percent over three months and sit roughly 21 percent below the February high. The chief executive will also join the same morning broadcast. Booking trends, onboard spending, and guidance for the rest of the year will matter. Cruise operators have benefited from strong demand, yet any sign of slower bookings or higher costs could pressure the stock and spill into related travel names. Taken together, these three reports offer a real-time window into how Americans are choosing to spend on food, drinks, and experiences.
Consumer Strength Or Emerging Caution
One observation circulating among market watchers caught my eye. A research note pointed out that the share of United States firms adopting artificial intelligence in regular business functions now shows a statistically significant negative correlation with employment growth and a positive correlation with unemployment. That is a heavy statement. It does not prove causation, yet it raises a legitimate question about whether productivity gains from new technology are beginning to affect hiring plans. I expect at least some of the consumer executives to face questions on labor costs and staffing levels. If they sound cautious, the market may start to weigh the longer-term employment picture more carefully.
In my experience, consumer stocks often act as an early signal. When households feel confident they keep buying the familiar brands and booking the trips. When they grow more careful, the first places they cut are discretionary items and premium experiences. Watching the language used by these management teams tomorrow should give a clearer sense of which environment we are actually in right now.
Big Tech Fundraising And Capital Markets Pressure
Another theme that refuses to fade involves the capital needs of large technology companies. A well-known market commentator spent time highlighting the sheer scale of recent fundraising. Amazon has tapped the bond market, Meta has explored equity routes, and names such as SK Hynix, Oracle, Intel, and Alphabet continue to require substantial resources to stay competitive in artificial intelligence infrastructure. The concern voiced was straightforward: the debt and equity markets may be running low on available capital, and rising rates would only tighten conditions further.
He was careful not to call a market top. Still, the caution felt genuine. Nvidia leadership has also noted the importance of capital availability. When the companies that need the most funding start competing for the same pool of money, valuations and financing costs can shift quickly. I have watched similar periods before. Capital does not disappear overnight, yet it does become more selective. Companies with weaker balance sheets or less proven returns on their technology investments can find the environment suddenly less friendly.
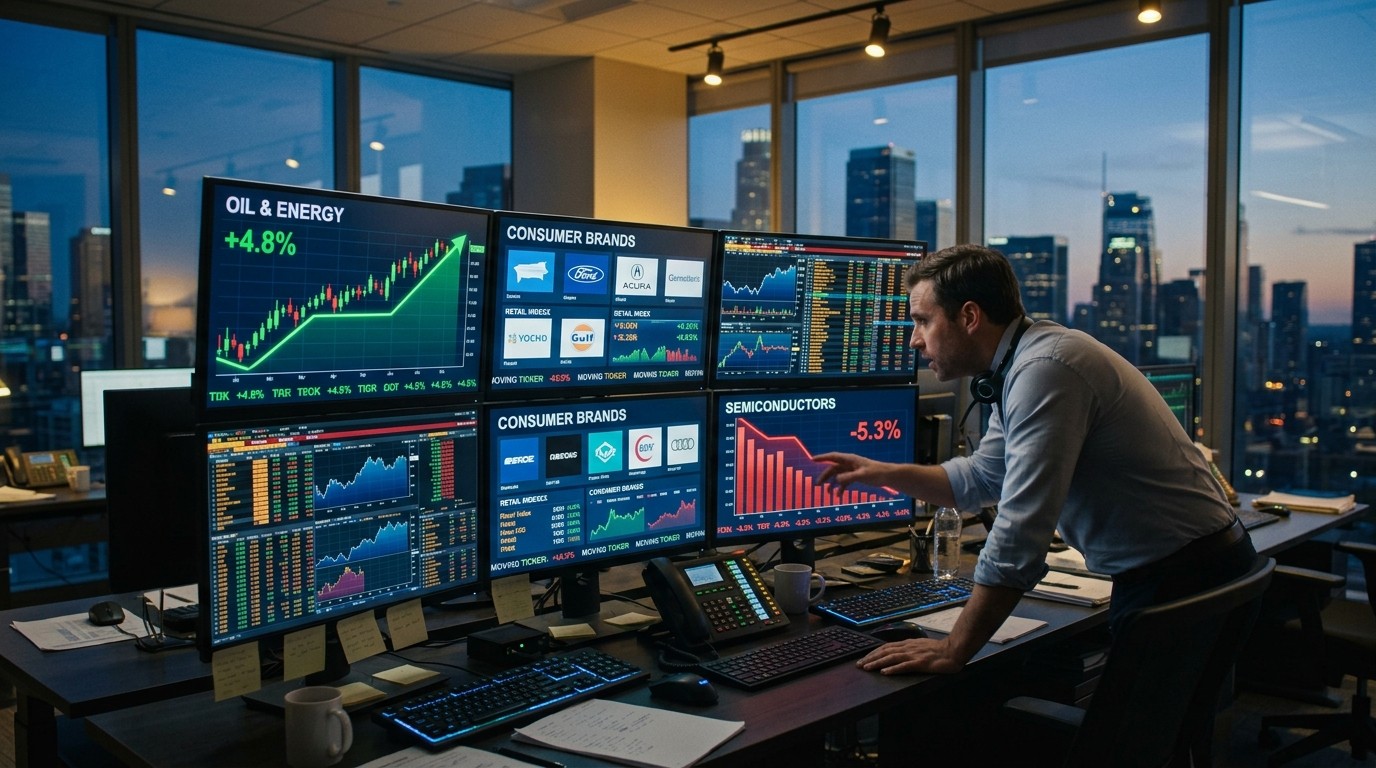
The Nasdaq-100 has already pulled back about 6.66 percent from its recent high. The VanEck Semiconductor ETF sits roughly 20 percent below its June peak. The Roundhill Memory ETF has dropped around 41 percent from the same period. The iShares Semiconductor ETF is down about 25 percent. Individual names show similar patterns. AMD has retreated nearly 20 percent from its early October high. Nvidia is off roughly 11 percent from the same point. Amazon sits about 13 percent below its early August level. These are not catastrophic declines, yet they represent a clear change in tone after the strong run earlier in the year.
The debt and equity markets are running out of money, and there are plenty of companies that will find it hard to raise funding.
That observation may prove more important than any single earnings report. Technology spending cycles have always been capital intensive. The current artificial intelligence build-out is simply the latest and perhaps the most expensive version. Investors will need to decide whether the expected returns still justify the rising cost of capital. That debate is unlikely to be settled in one session, but any incremental comments from management teams or shifts in bond yields could nudge sentiment.
Communication Services Hit Fresh Lows
The communication services sector has quietly moved into weaker territory. It recently touched levels not seen since mid-2025. Two names in particular, AppLovin and T-Mobile, registered 52-week lows. Overall the sector sits about 15.5 percent below its May high and is essentially flat over the past twelve months. Advertising-related businesses and certain wireless operators have faced their own unique pressures. Any further softness here could weigh on broader growth indexes because the sector still carries meaningful weight in major benchmarks.
I tend to watch this group as a secondary confirmation of risk appetite. When investors are eager to own growth they often rotate into these names. When they grow more defensive the sector can lag. The current price action suggests a more cautious posture is already in place. Tomorrow’s session will show whether that posture deepens or begins to stabilize.
Energy Stocks Print All-Time Highs
While technology has cooled, energy has heated up. Chevron reached an all-time high in the previous session. ExxonMobil did the same. That kind of simultaneous strength at the top of the sector rarely goes unnoticed. Morning coverage is expected to focus on the latest developments in the group. Strong oil prices, disciplined capital returns, and steady demand have clearly supported these names. Whether the momentum continues depends in part on broader commodity trends and any fresh supply news.
From a portfolio perspective the contrast is striking. Capital has rotated toward cash-flow generative energy companies at the same time it has grown more selective toward high-multiple technology names. That rotation can persist for longer than many expect. It can also reverse quickly if oil prices soften or if technology delivers surprisingly strong results. For now the price charts favor energy.
Brazil Election Aftermath And Market Reaction
Overseas political developments added volatility. On the first trading day after the Brazilian presidential result, the iShares MSCI Brazil ETF dropped almost 20 percent. The market had clearly positioned for a different outcome. The ETF now sits roughly 30 percent below its 52-week high. Currency moves, fiscal policy expectations, and foreign investor flows will continue to influence the path from here. Emerging market specialists will watch closely for any stabilization signals or further selling pressure.
Political surprises of this magnitude often create multi-session adjustments rather than one-day events. Liquidity can thin, and positioning can remain offside for some time. Investors with exposure to the region will need patience and a clear view on the new policy direction.
Israel Election Day And Regional Uncertainty
Israel holds its election on Tuesday. The contest has been contentious. The iShares MSCI Israel ETF has pulled back about 12 percent from its May high, yet it remains up roughly 11 percent year to date and about 22 percent over the past twelve months. Geopolitical risk premiums can expand or contract quickly around election results. Equity markets in the region often react more to the perceived stability of the outcome than to any single policy detail. The session will provide the first real-time price discovery after votes are counted.
Emerging Markets Broader Context
World Bank Group leadership is scheduled to appear on morning television. That conversation may touch on global growth, capital flows into developing economies, and any shifts in development finance. The iShares MSCI Emerging Markets ETF sits about 13.6 percent below its June high but remains up roughly 13 percent for the year. The divergence between year-to-date gains and the more recent pullback mirrors patterns seen in other risk assets. Selective strength has given way to broader caution in recent months.
I have long believed that emerging markets require a higher tolerance for volatility. Currency swings, political transitions, and commodity dependence all amplify moves. The current environment, with two notable elections in focus, simply raises the stakes for the near term.
Putting The Pieces Together For Tuesday
So what is an investor supposed to do with this collection of stories? First, recognize that the consumer reports will set an early tone. Strong numbers from Coca-Cola or constructive commentary from the cruise and packaged food executives could support a risk-on bias in the first hour. Soft guidance or cautious language on spending could quickly reverse that bias.
Second, keep an eye on technology and semiconductor price action. The recent declines have been orderly so far. A further break lower on heavy volume would suggest the capital concerns are gaining traction. Stabilization or a bounce would indicate that buyers still see value after the pullbacks.
Third, energy strength may continue to act as a relative bright spot. As long as the commodity complex holds up, the large integrated names can attract defensive and income-oriented capital.
Fourth, respect the political calendar. Brazil has already delivered a sharp reaction. Israel’s results will land during the session. Emerging market volatility can spill into broader risk sentiment, especially if currency moves become disorderly.
- Monitor the language used by consumer executives on pricing power and demand trends
- Watch semiconductor and memory-related ETFs for signs of further technical breakdown or support
- Track energy leadership as a potential relative strength signal
- Stay alert to any sharp moves in Brazil and Israel related funds
- Listen for comments on capital availability and financing costs from technology leaders
None of these factors exists in isolation. A soft consumer report combined with another down day in semiconductors and a messy election reaction could produce a more defensive session. Conversely, solid consumer numbers, a pause in technology selling, and calm political markets could allow the previous session’s modest gains to extend.
Perhaps the most interesting aspect is how little the broad indexes have reflected the underlying divergences so far. The Dow managed a respectable advance while important growth and cyclical subgroups told different stories. That kind of internal dispersion often precedes a period of clearer leadership. Tuesday’s news flow has the potential to accelerate that process.
Risk Management Considerations
In environments like this I prefer to keep position sizes reasonable and avoid concentrated bets on any single narrative. The consumer data could surprise in either direction. Technology funding concerns may prove temporary or may deepen. Political outcomes carry their own unpredictable elements. Spreading exposure across a few of these themes while maintaining dry powder for opportunities feels more prudent than swinging hard at one idea.
Volatility itself can become an opportunity. Sharp intraday moves around earnings releases or election headlines sometimes create better entry points than the closing prices of the previous day. Having a short list of names or sectors already researched makes it easier to act when those moments appear.
Longer-Term Context Worth Remembering
Stepping back, the market continues to digest a powerful technology investment cycle, shifting consumer behavior, and a complex global political calendar. None of these forces will resolve in a single session. What Tuesday offers is simply the next set of data points and price reactions. Treating them as incremental information rather than definitive answers helps keep perspective.
The companies reporting earnings will provide hard numbers on volumes, margins, and outlooks. The political events will clarify policy directions in two important markets. The ongoing debate about capital availability for technology investment will continue in the background. Together they form a dense but navigable landscape for those willing to stay flexible.
I plan to watch the open with particular attention to the consumer names and the semiconductor complex. Those two areas seem most likely to set the early emotional tone. From there the session will reveal whether energy leadership persists and whether emerging market volatility remains contained. It is rarely dull when this many storylines converge on the same trading day.
Markets have a way of surprising even when the calendar looks full. Sometimes the expected catalysts produce little reaction while an overlooked comment or secondary data point drives the real move. Staying alert to that possibility remains part of the discipline. The next session will add another chapter to the ongoing story of how investors are balancing growth ambitions, capital constraints, consumer resilience, and geopolitical uncertainty. That balance is still being negotiated in real time.
One final observation. The modest advance in the Dow on the previous day occurred against a backdrop of mixed internal signals. Leadership was not broad. That often leaves the market vulnerable to whatever narrative gains the most traction the following day. Whether that narrative turns out to be consumer strength, technology caution, energy momentum, or political risk will become clearer once the opening trades begin to print. Until then preparation and selective focus remain the most practical approach.
The coming hours will test several competing theses at once. Investors who have already mapped the key levels in the major ETFs and individual names will be better positioned to respond. Those waiting for perfect clarity may find the session moves before the picture fully forms. In that sense Tuesday looks like a classic opportunity for active observation rather than passive assumption.
Consumer spending patterns, technology capital needs, energy cash flows, and political transitions do not usually align so neatly on the calendar. When they do, the resulting price action often carries information that lasts beyond a single day. Paying close attention to the details, the language of executives, and the reaction of related sectors should prove more useful than trying to predict the exact closing level of any index.
That is the mindset I am carrying into the next session. The stories are clear enough. The market’s response to them will tell us which ones currently matter most.