
I was half listening to the radio while making coffee when the first numbers started rolling in from the 2026 Autumn Budget. One moment it was the usual talk about global shocks, the next it was concrete measures that will land in bank accounts and on energy statements within weeks. Chancellor John Healey had finally delivered his first full fiscal statement, and the mix of relief for households and fresh tax adjustments left plenty to unpack. If you only caught the headlines, you probably missed some of the finer points that will shape household budgets for the next few years.
What Stood Out Most From The Day
The speech itself ran longer than many expected, yet the core message stayed consistent. The government wanted to give working households a bit of breathing space while still keeping the public finances on a path that markets would accept. Growth forecasts were nudged higher by the independent Office for Budget Responsibility, borrowing was set on a downward track, and debt as a share of the economy was projected to ease gradually. That provided the backdrop for the practical measures people actually notice in their monthly outgoings.
I’ve followed enough of these statements to know that the detail often matters more than the big numbers. A freeze here, a temporary surcharge there, an extension of a previous cut – these are the decisions that either ease pressure or quietly add to it. In this case the package leaned toward targeted help on energy costs and wages, paid for in part by higher charges on banks and certain forms of unearned income.
Energy Support That Reaches Millions
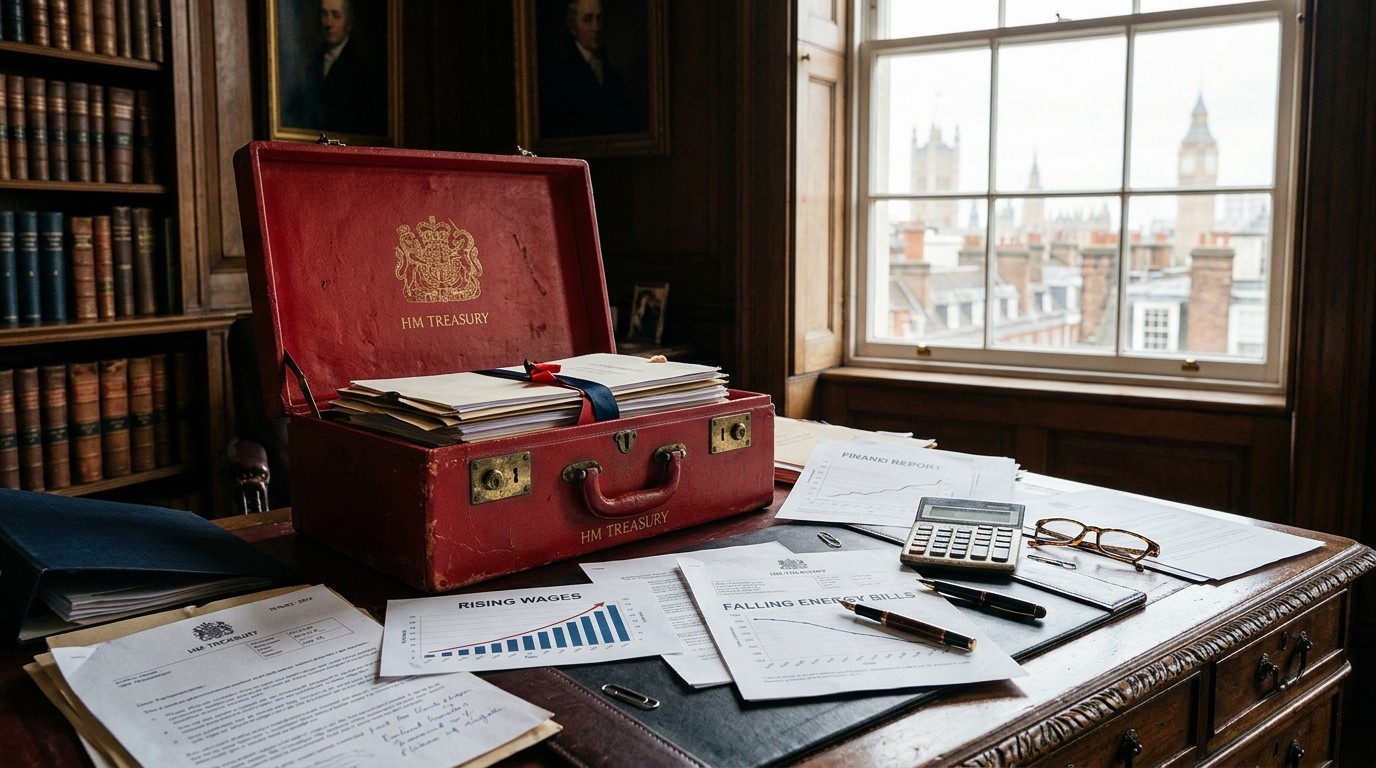
The clearest win for ordinary households came on the energy front. Standing charges on gas bills will be scrapped from next year, with those fixed costs moved onto the unit rate instead. Official estimates suggest around sixty percent of homes could save an average of forty-five pounds a year. That may not sound dramatic on its own, but combined with other steps it starts to add up.
At the same time the temporary removal of VAT from electricity bills is being extended through to July. The Chancellor put the annual saving at fifty pounds against the price cap. For many families that extra stretch of relief will cover the colder months when heating demand peaks. On top of those structural changes, twenty million households living in council tax bands A to D will receive a one-off one hundred pound energy payment this winter. The total cost sits around two point six billion pounds, and the money is due to arrive directly in bank accounts.
In my view this combination shows a deliberate choice to prioritise immediate cost-of-living pressure over broader tax cuts. Whether it proves enough depends on how wholesale prices move in the months ahead, but the direction is clear. Households in the lower council tax bands get the cash boost, while the standing charge reform aims at a longer-term rebalancing of how energy is charged.
That’s what a buffer is for. Use it when you need it. Rebuild it when you can.
Those words from the Chancellor captured the fiscal philosophy behind the statement. The headroom against the government’s stability rule sits at fifteen billion pounds in 2029-30, rising later to twenty-two billion. It is tighter than some earlier forecasts, yet still enough to absorb the higher debt interest costs caused by recent global turbulence.
Wage Increases For The Lowest Paid
Another tangible change affects the lowest earners directly. Both the National Minimum Wage and the National Living Wage will rise by three point nine percent. For the main adult rate that takes the figure to thirteen pounds twenty-one an hour. Workers aged eighteen to twenty will see their rate climb to eleven pounds twenty-seven. Roughly two point three million people stand to benefit.
These annual uplifts have become a regular feature, yet the timing matters. With energy and food costs still elevated after recent global events, the extra income arrives when many households need it most. Employers will feel the pressure on wage bills, of course, and some smaller firms may find the adjustment tricky. Still, the policy keeps the focus on supporting those at the bottom of the pay scale without touching income tax thresholds for the broader workforce.
I have spoken to a few people who work shifts in retail and hospitality. For them the difference between this year’s rate and next year’s is the difference between scraping by and having a little room for unexpected expenses. It is not transformative, but it is real money in real pockets.
Tax Adjustments On Banks And Investment Income
To help fund the spending side, the bank surcharge on corporation tax moves from three percent to six percent for a limited period of fifteen months starting in January. The change is expected to raise a few hundred million this year and close to a billion the following year. It sits below the eight percent level that applied until a few years ago, so the sector had braced itself for a steeper rise.
Property and savings income faces an extra two pence on the rates from April. Basic rate becomes twenty-four percent, higher rate forty-four percent, and additional rate forty-nine percent. The measure is projected to bring in around a billion pounds a year. For anyone relying heavily on rental income or larger savings interest, the change will register. Basic rate taxpayers with modest savings will notice less, yet the direction of travel is unmistakable.
One relief that surprised some observers was the decision to keep the cash ISA annual allowance at twenty thousand pounds. An earlier plan to reduce it had been floating around, but it was dropped. Savers who use the full allowance each year will welcome the continuity. In a climate where many feel squeezed, preserving that tax-free space feels like a small but useful concession.
Fuel Duty And Everyday Shopping
Motorists received another extension of the five pence fuel duty cut, now running through to July 2027. The freeze has become almost traditional, yet each renewal still helps keep pump prices lower than they would otherwise be. Hauliers and farmers, who use red diesel, also benefit from rates held at historically low levels.
On the supermarket front, import tariffs were removed from more than a hundred everyday items including baked beans, chocolate and gherkins. The practical effect should be modest price reductions on those specific products. It is the kind of measure that rarely makes front-page news yet can shave a few pence off the weekly shop for families who buy those staples regularly.
Mileage rates for employees using their own cars for work also rose, with the higher rate moving from twenty-five pence to thirty-five pence per mile. For anyone who claims business travel expenses, that is a noticeable improvement.
The Broader Economic Picture
Behind the individual measures sits a set of forecasts that try to balance caution with cautious optimism. Growth is now expected at one point two percent this year, one percent next year, then climbing toward one point six to one point eight percent in the later years of the forecast. Borrowing falls steadily as a share of national income, from four point two percent this year down to one point eight percent by the early 2030s. Debt peaks and then declines slowly toward eighty-one point seven percent of GDP by 2031-32.
These numbers matter because they determine how much room future Chancellors will have. A smaller fiscal buffer means less flexibility if another shock arrives. At the same time the commitment to eliminate the current budget deficit within three years signals an intention to restore more conventional fiscal discipline. Markets appeared to take the overall package in their stride, which is never guaranteed when global conditions remain unsettled.
Perhaps the most interesting aspect is how the statement tried to thread several needles at once. Support for households on energy and wages, modest extra revenue from banks and investment income, continued freezes on fuel duty, and a preservation of popular savings vehicles. It is not a radical rewriting of the tax system, nor is it a pure austerity exercise. It sits somewhere in the middle, reacting to the immediate pressures while attempting to keep longer-term rules intact.
How Households Might Feel The Changes
For a typical family in a band C property the one hundred pound energy payment plus the extended VAT cut and standing charge reform could ease winter bills by a meaningful amount. Someone on the National Living Wage will see their weekly pay rise by several pounds once the new rates take effect. A basic rate taxpayer with a small amount of savings interest will notice only a minor increase in tax, while a landlord with significant rental income will feel the two pence rise more sharply.
Businesses in hospitality and retail gain from extended small business rates relief covering more firms. That should help some high-street operators stay afloat. Banks will pay more for a limited period, which they will no doubt pass on in some form, yet the temporary nature of the surcharge limits the long-term impact.
I keep coming back to the idea of breathing space. That phrase appeared more than once in the surrounding commentary, and it captures the mood of the statement better than any single policy. After years of successive shocks – pandemic after-effects, energy crises, geopolitical tensions – the priority was to stop the squeeze from tightening further for those least able to absorb it.
Points That Deserve A Second Look
Not every announcement received equal attention on the day. The decision to retain the full cash ISA allowance, for example, reverses an earlier direction of travel and preserves a popular tool for ordinary savers. The first-time buyer ISA replacing the Lifetime ISA, together with a new equity loan scheme for those without family support, points to ongoing efforts to help younger people onto the housing ladder. Details on the exact terms will matter a great deal, yet the intention is clear.
Defence spending continues to rise, with the budget already fourteen billion pounds higher than the final year of the previous government. A pathway toward the NATO target of three point five percent of GDP by 2035 is promised for next year’s spending review. Support for Ukraine remains in place. These are longer-term commitments that sit alongside the more immediate household measures.
On the welfare side, adjustments to the triple lock and progress toward a National Care Service were flagged. The precise shape of those changes will emerge later, but they form part of the broader attempt to manage demographic and cost pressures without sudden cliff edges.
- Energy standing charges removed from gas bills
- VAT relief on electricity extended to July
- One hundred pound payment for twenty million lower-band households
- Minimum and living wages up three point nine percent
- Bank surcharge raised temporarily to six percent
- Extra two pence on property and savings income tax rates
- Cash ISA limit held at twenty thousand pounds
- Fuel duty cut extended again
Looking across that list, the balance becomes easier to see. Help is concentrated where living costs bite hardest, while revenue is drawn from sectors and income types that the government judges can contribute more. Whether that judgement holds up will depend on economic performance over the next couple of years.
Putting The Numbers In Context
Fifteen billion pounds of headroom sounds large until you set it against the scale of the public finances. Debt interest alone is running higher because of recent market movements. Using part of the previous buffer to absorb those costs and still deliver targeted support is a calculated risk. The OBR’s upgraded growth forecasts provide some comfort, yet growth of one to one point eight percent remains modest by historical standards.
Borrowing falling to one point eight percent of GDP by the early 2030s would mark a return to more sustainable levels. Debt declining slowly from its current peak would ease pressure on future budgets. Those trajectories assume no major new shocks, an assumption that recent history has repeatedly challenged. Still, the framework is clearer than it has been at certain points in the past.
For investors and markets the absence of large unfunded commitments and the presence of a residual buffer appear to have been reassuring. Sterling and gilt yields reacted without drama, which is often the best outcome a Chancellor can hope for on Budget day.
Practical Steps Worth Considering Now
Anyone who can should check whether they fall into the council tax bands that qualify for the energy payment and make sure bank details are up to date where necessary. Workers on the minimum wage rates will want to confirm the new hourly figures with their employers ahead of the implementation date. Savers who have been close to the ISA limit can continue planning on the full twenty thousand pound allowance.
Landlords and those with substantial savings or dividend income should recalculate their tax positions for the new rates from April. The two pence increase is not catastrophic for most, yet it is real and cumulative. Businesses eligible for the extended rates relief should check the expanded criteria so they do not miss out.
I have found that the weeks immediately after a Budget are the best time to run these numbers, while the announcements are still fresh and before the practical details get buried under the next wave of news. A quick conversation with an accountant or a careful look at payslips and energy statements can prevent small surprises later.
Looking Ahead From Here
This Autumn Budget will not be remembered as a dramatic turning point. It is more of a steadying statement delivered under difficult external conditions. The Chancellor accepted a tighter fiscal buffer, delivered tangible help on energy and wages, and raised modest extra revenue from specific sources. The growth and borrowing forecasts provide a credible path, provided nothing else goes badly wrong.
For households the near-term effect should be a little more room on energy bills and a slightly higher wage floor. For savers the ISA rules stay familiar. For those with property or significant investment income the tax rates edge higher. Taken together the package aims to protect the most exposed while keeping the overall fiscal framework intact.
Whether it succeeds will become clearer over the coming months as the energy payments arrive, the new wage rates take effect, and the next set of inflation and growth figures appear. For now the main points are on the record, and remembering them accurately is the first step toward understanding what they mean for personal finances.
The details will keep emerging in the technical notes and secondary legislation that follow every Budget. Yet the broad shape is already visible. Support where costs are highest, revenue from those judged able to pay a bit more, and a continued effort to bring the public finances onto a more stable footing. That is the essence of what was announced, and it is worth keeping those elements in mind as the practical consequences begin to appear in everyday life.