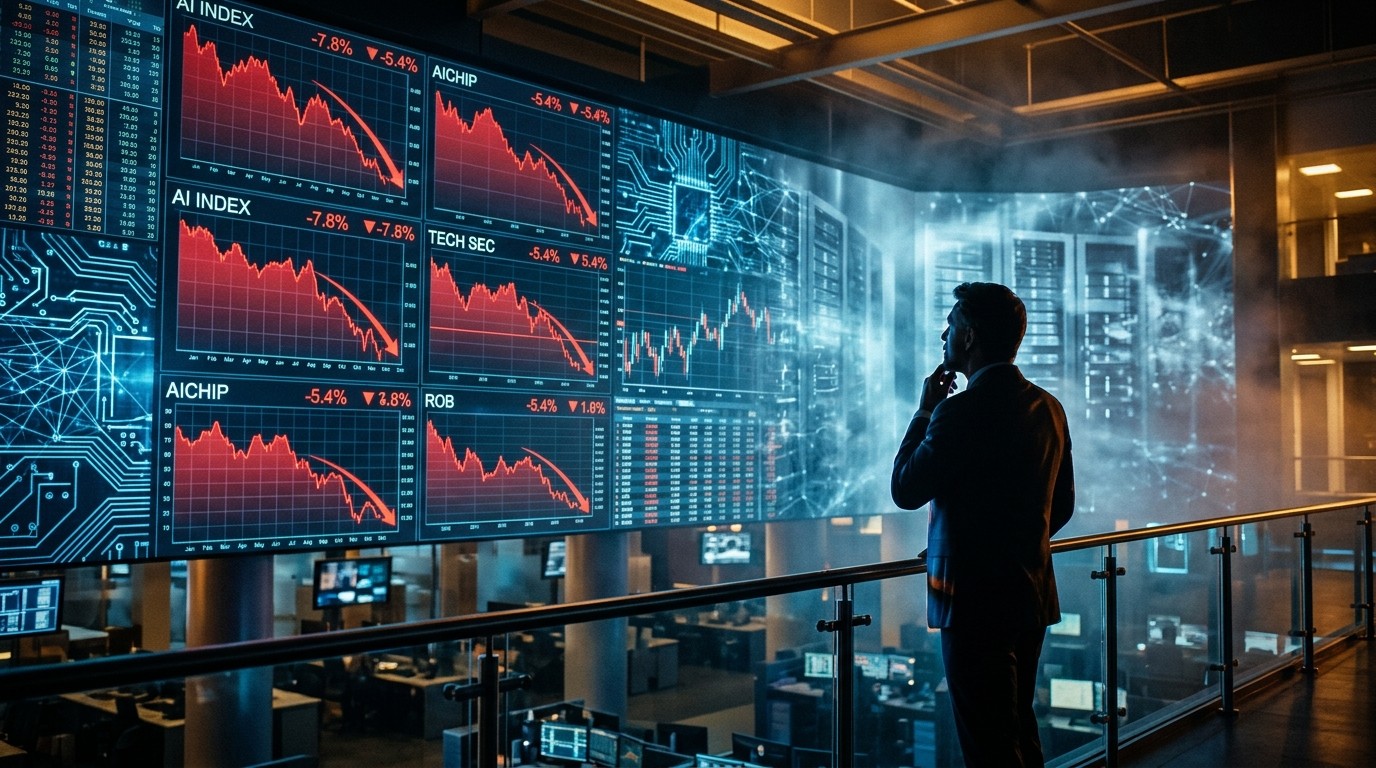

Something shifted this week and you could almost feel it in the air. Tech names that had been the market’s favorite children for months suddenly looked vulnerable. The Nasdaq took a hard hit, semiconductors got punched harder, and conversations that used to center on endless growth started sounding more cautious. I kept thinking about how quickly confidence can evaporate when numbers and politics collide. That is the moment we are in right now with the so-called AI trade.
Understanding The Sudden Pressure On Artificial Intelligence Stocks
The drop was not gentle. Major indexes showed clear stress and specialized funds tied to artificial intelligence and chip makers recorded some of their steepest single-day declines in years. What stood out to me was how the selling refused to stay contained. Even companies with little direct connection to data centers felt the pressure. When one corner of the market sneezes this loudly, the rest of the room tends to catch the cold.
A big part of the unease traces back to shifting political winds. After recent elections, investors began recalculating the likelihood of tighter rules around large-scale data center construction. Some voices on the policy side have grown more critical of the energy demands and local impact of these facilities. That kind of uncertainty hits growth forecasts hard because the entire AI story has rested on the assumption of rapid, largely uninterrupted infrastructure expansion.
I have watched markets long enough to know that forecasts of more than a trillion dollars in capital spending next year suddenly look less automatic when the regulatory weather changes. One experienced portfolio manager put it plainly: people are starting to question whether that spending wave will arrive on schedule. The moment those doubts surface, valuations that priced in smooth acceleration begin to look stretched.
Why Capex Assumptions Matter More Than Headlines
Capital expenditure is the quiet engine behind the AI narrative. Companies need physical capacity before they can deliver the computing power everyone talks about. When investors start wondering whether new facilities will face delays or higher costs, the growth math changes. Existing capacity suddenly becomes more valuable, yet the path to additional capacity grows rockier.
One seasoned observer noted that cloud businesses are still posting very strong year-over-year gains, which suggests demand remains robust. The constraint appears to sit more on the supply side. If building new capacity becomes politically or logistically harder, the companies that already own working infrastructure may hold a stronger hand. That distinction feels important right now.
In my view the market is doing what it always does when a dominant theme faces friction. It tests the weakest assumptions first. The broad, almost automatic bet on every company loosely connected to artificial intelligence is getting a reality check. Selective ownership starts looking smarter than blanket exposure.
Broader Market Ripple Effects Beyond Pure AI Names
The selling did not stop at semiconductor and software firms. Blue-chip averages also slid meaningfully as risk appetite cooled. Higher yields on longer-term government bonds added another layer of pressure. When a relatively safe return sits near five percent, the case for holding highly volatile growth stocks needs to be stronger.
Some managers openly said portfolios had become too concentrated in technology. Reducing that heavy tilt does not require abandoning the sector entirely. It simply means asking harder questions about position size and valuation. I find that kind of self-check healthy, even if it feels uncomfortable while prices are falling.
You do not need to keep an outsized allocation to the most volatile names when safer alternatives offer competitive returns.
That practical observation captures the mood shift. Risk-free rates have become competitive again, and investors notice. The opportunity cost of staying fully committed to high-beta AI exposure is no longer theoretical.
Voices Suggesting The Trade Is Not Finished
Not everyone believes the story has ended. Several experienced investors argue that the recent decline simply makes the remaining opportunities more interesting. They point out that demand for computing power has not disappeared. What changed is the ease of expanding supply. In that environment, companies with proven capacity and disciplined capital plans can still deliver solid results.
One portfolio manager highlighted a few names that held up better or even advanced while the broader group fell. Those relative winners tended to have clearer near-term catalysts or less direct exposure to the most contested infrastructure spending. The market is beginning to differentiate again, which is usually a healthier phase than the period when almost everything rose together.
I tend to agree that indiscriminate selling often creates openings for patient capital. When prices move more on fear than on fundamental deterioration, longer-term investors gain room to act. Of course the key word is patient. Trying to catch every bounce can be expensive.
Practical Steps For Navigating The Current Environment
First, revisit concentration. Many portfolios quietly drifted toward heavy technology weightings during the long upswing. Bringing those weights closer to long-term targets can reduce overnight stress without requiring a complete exit from the theme.
Second, separate the infrastructure pure plays from the broader ecosystem. Firms that sell tools, software, or services around artificial intelligence may face different dynamics than those pouring capital into physical data centers. The political and permitting risks sit more heavily on the latter group.
- Review current position sizes against your original plan
- Check whether recent price moves still leave valuations reasonable
- Consider whether higher bond yields change the relative attractiveness of growth stocks
- Look for companies with visible near-term demand rather than distant hopes
- Keep some dry powder for true dislocations if they appear
Those steps sound almost boring, yet they are the ones that tend to matter most when narratives shift. I have found that the investors who stay calmest during these periods are usually the ones who already knew their risk limits before the turbulence arrived.
The Role Of Selectivity Going Forward
Blanket enthusiasm is giving way to careful picking. That transition is normal and, in many ways, overdue. The companies that continue to post strong results while others struggle will likely command attention again once the initial wave of selling exhausts itself.
One thoughtful observer noted that when new capacity becomes harder to build, the value of existing capacity rises. That simple logic may support certain established players even if the overall pace of industry expansion slows. It is the kind of nuance that gets lost when markets move in a single direction for too long.
Perhaps the most interesting aspect is how quickly the conversation has moved from pure optimism to measured skepticism. That change itself can create opportunity for those willing to do the work of distinguishing solid businesses from hopeful stories.
Valuation Discipline In A High-Rate World
Higher interest rates change the discount rate applied to future cash flows. Growth that arrives later becomes less valuable in present terms. Artificial intelligence companies often trade on expectations of large profits years down the road. When rates climb, those distant numbers lose some of their magnetism.
I keep coming back to the idea that a compelling risk-free rate forces a tougher conversation. Why accept significant volatility for uncertain upside when a government bond offers a steady return? The answer is not the same for every investor, of course. Younger portfolios with long horizons may still prefer growth. Older or more conservative ones may rightly decide the trade-off has shifted.
In practice this means checking whether the expected return from a given stock still compensates for its risk after adjusting for the higher baseline rate. Some names will still clear that bar. Others may not. The process of sorting them is exactly what markets are doing right now, albeit noisily.
Signs That Selling May Have Become Overdone
Sharp single-day declines of the magnitude seen recently often contain an element of forced liquidation or pure panic. When specialized funds drop double digits in a session, some of the pressure is mechanical rather than fundamental. That does not mean prices cannot fall further, yet it does open the door for buyers who believe the longer-term case remains intact.
Several chief investment officers described the move as indiscriminate and therefore potentially interesting for those with a multi-year view. They emphasize looking through the noise to the underlying demand for computing power, which has not vanished overnight. The political and permitting hurdles are real, but they do not erase the technological progress already underway.
My own sense is that the market needed a pause. The previous climb had become almost too smooth. Corrections of this type, while painful, often reset expectations and clear out the most speculative positions. What remains can form a more durable foundation.
Building A More Resilient Approach To Growth Themes
One lesson that keeps repeating across market cycles is the danger of single-theme dominance. When a narrative becomes so powerful that nearly every portfolio leans the same way, the eventual reversal tends to be sharper. Diversifying across styles, geographies, and time horizons softens that blow.
That does not require abandoning artificial intelligence exposure. It simply means treating it as one important sleeve among several rather than the centerpiece of everything. Balanced portfolios still participate in the upside while sleeping better during the inevitable rough patches.
- Define a clear maximum weighting for any single theme
- Rebalance when that limit is breached rather than hoping for a soft landing
- Pair growth holdings with more stable income or value positions
- Monitor policy developments that could affect capital plans
- Stay flexible enough to increase exposure if valuations become truly compelling
These habits sound straightforward until emotions run high. Writing them down ahead of time makes them easier to follow when screens turn red.
What Longer-Term Investors Should Watch Closely
Demand metrics from major cloud providers remain one of the cleanest signals. As long as those businesses continue to grow at robust rates, the underlying need for capacity is real. The question is mainly about the speed and cost of meeting that need.
Energy availability and local permitting processes will likely stay in the headlines. Any concrete progress or setbacks on those fronts can move stocks quickly. Investors who track those developments rather than daily price swings will probably make clearer decisions.
Corporate commentary on capital plans also deserves attention. Management teams that remain confident about their spending schedules while others pull back may signal stronger competitive positions. Conversely, widespread delays could confirm the more cautious view currently circulating.
I find it useful to separate the noise of a single volatile session from the slower-moving fundamentals. Price action can reverse in a week. Changes in policy or energy constraints tend to linger longer.
Balancing Optimism With Realistic Expectations
Artificial intelligence remains a transformative technology. That broad statement still holds. What has changed is the assumption of frictionless, unlimited expansion. Markets are adjusting to a world where progress continues but faces more obstacles than many expected six months ago.
In that environment the winners are likely to be the companies that execute well under tighter constraints rather than those that simply promised the most aggressive growth. Execution, capital discipline, and existing scale matter more when the easy path narrows.
Some of the recent price action feels excessive to me, yet excesses often last longer than logic suggests. Waiting for clearer evidence of stabilization before adding risk can be a reasonable stance. Others with higher risk tolerance may choose to begin scaling in gradually. Both approaches can work if they match the investor’s actual temperament and time horizon.
Final Thoughts On Positioning For What Comes Next
The AI trade as a simple, one-way bet has probably run its course for now. What replaces it is a more nuanced, selective approach that weighs political risk, capital intensity, and relative valuation more carefully. That shift does not mean the technology itself has lost its importance. It means the investment case has matured and now requires more homework.
I keep returning to the idea that periods of doubt often plant the seeds of the next durable advance. When the easy money has been made and the remaining participants are forced to prove their worth, the survivors tend to be higher quality. Whether that process takes weeks or months is hard to say. What feels clearer is that the investors who treat the current environment as a chance to upgrade their holdings rather than a reason to abandon the theme entirely will likely come out ahead.
Stay focused on the companies that can still grow even if the overall buildout slows. Watch the policy signals without letting every headline dictate trades. And remember that markets move in phases. The phase of unquestioned enthusiasm has given way to one of healthy skepticism. Navigating that change with discipline is the real task in front of us right now.
The numbers will keep moving and the headlines will keep coming. Underneath it all the demand for greater computing power continues. How that demand gets met, at what cost, and by which companies will determine the next chapter. For investors willing to stay curious and selective, that chapter still holds opportunity.