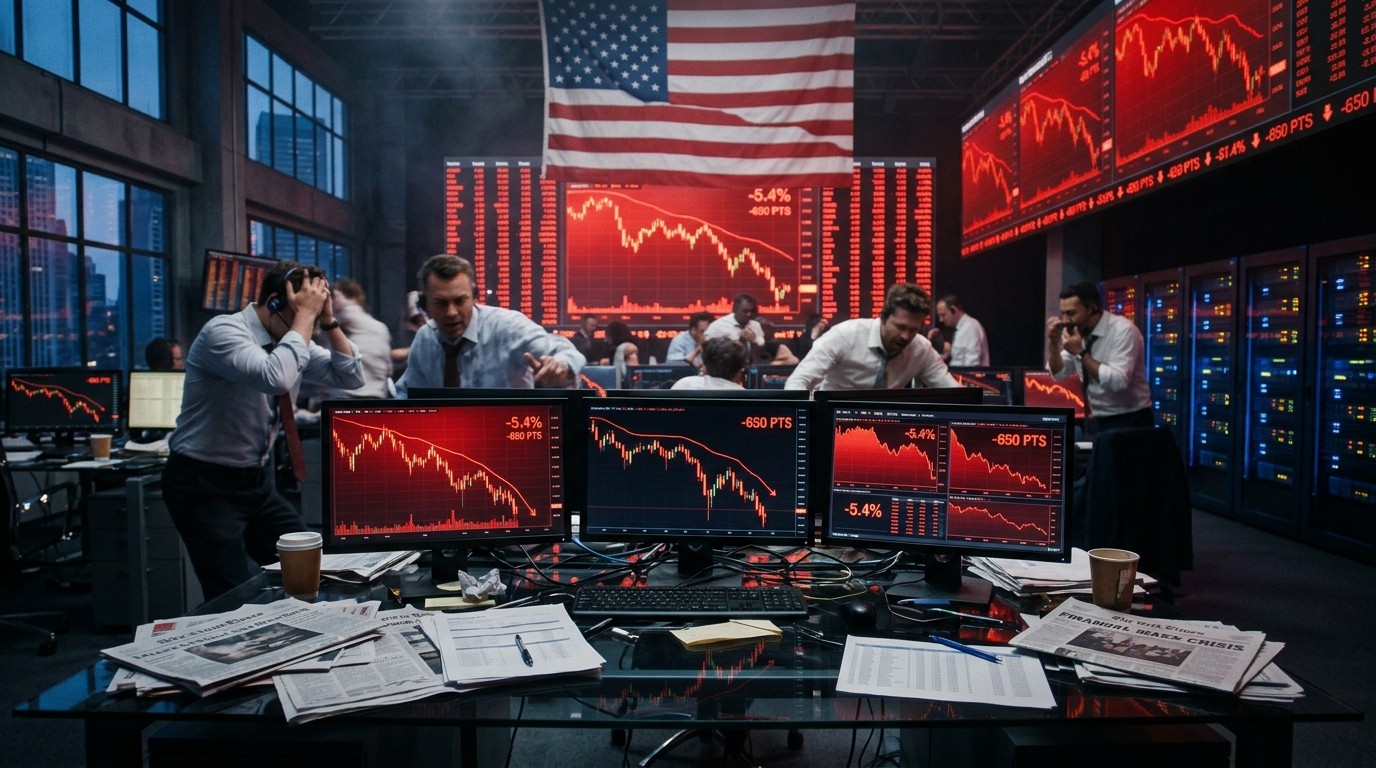

I still remember the feeling from just a couple of days ago. Indexes were climbing, headlines felt optimistic, and it seemed like the market had already decided the election outcome was somehow digestible. Then Thursday arrived and wiped most of that confidence away in a few brutal hours. Watching the S&P 500 drop roughly four percent and the Nasdaq tumble about four and a half percent felt less like a normal pullback and more like a sudden change of heart across the entire Street.
How The Postelection Bounce Unraveled So Quickly
The speed of the reversal caught a lot of people off guard. On Wednesday the major averages looked strong. Gains were broad enough at the index level that it was easy to miss the quiet rotation happening underneath. Money was already leaving pure artificial intelligence names and moving toward areas that felt safer. That rotation stayed mostly hidden until Thursday, when the selling became impossible to ignore.
What changed? Investors started connecting the election results more directly to future spending on data centers. The concern is straightforward. A shift in political control could slow the pace of new infrastructure projects that many AI-related companies need to keep growing. Once that idea took hold, the selling snowballed.
In my view the market had been pricing in a smoother path than reality allowed. Elections always bring uncertainty, yet the initial reaction treated the outcome as mostly positive. That assumption did not survive contact with the next trading session.
Tech Led The Charge Downward
Technology took the hardest hit. The Nasdaq’s decline pushed the index into correction territory, defined as a drop of ten percent from its recent peak. That peak had been set only about a month earlier, which shows how fast sentiment can swing.
Almost every major tech name participated in the move lower. The selling felt indiscriminate at first, yet a closer look revealed an important split. Companies that already own large existing data center footprints held up better than those still trying to build capacity from a weaker financial base.
I’ve found that markets often punish the most leveraged growth stories first when uncertainty rises. That pattern repeated itself here. Names dependent on continuous access to capital for expansion saw the steepest losses.
The Have And Have-Not Divide Inside AI
Not every AI-related company faces the same pressure. The difference between the big hyperscalers and the newer neocloud players has become impossible to overlook.
Hyperscalers already operate massive infrastructure. They generate strong free cash flow and can fund projects internally even if external financing becomes tighter. If regulations or political shifts force them to slow spending, that could actually improve their cash generation in the near term.
The newer specialized cloud providers sit in a tougher spot. Many need ongoing capital to expand capacity. When investors start worrying about tighter credit conditions or slower project approvals, those stocks feel the pain immediately.
One prominent neocloud name has already lost more than half its value since the Nasdaq’s recent high. That kind of drawdown forces portfolio managers to reassess position sizes quickly.
Our view from Wednesday’s rally about the large hyperscalers has not changed despite today’s selloff. They remain in a much stronger financial position than the newer players when it comes to funding and completing data center projects.
That assessment feels right to me. Scale and balance sheet strength matter more during periods of political and regulatory uncertainty.
Oil Prices Added Another Layer Of Pressure
Energy markets complicated the picture further. On Wednesday crude prices fell sharply on the idea that the election results might ease geopolitical tensions. Thursday brought a reversal. Traders began questioning whether the political shift would actually reduce Middle East risks or simply create a different set of uncertainties.
Higher oil prices on the same day tech was selling off created a double headwind. Rising energy costs can feed inflation concerns just as investors were already rethinking growth expectations.
Every single sector in the S&P 500 finished lower. That kind of breadth tells you the move was about more than one group of stocks. It reflected a broad reassessment of risk.
What Friday’s Jobs Report Means For Rates
The next major data point arrives before the opening bell on Friday. The October employment report will give the market fresh information about the labor market’s health.
Economists currently expect around sixty-five thousand new jobs. That number sits well above the surprisingly weak figure from the prior month. The unemployment rate is forecast to stay steady near four point two percent. Average hourly earnings are projected to rise three tenths of a percent, a touch warmer than the previous reading.
Why does this matter so much right now? The Federal Reserve is still balancing its dual mandate. Employment remains solid overall, yet inflation has not fully returned to the preferred range. A stronger-than-expected jobs number could push expectations for another rate increase higher. A weaker number might give the central bank more room to stay patient.
Just a day earlier the odds of a December hike had been near eighty-three percent. By Thursday afternoon those odds had dropped to around sixty-six percent. Bond yields fell as investors bought Treasuries, pulling the ten-year yield back below four point nine percent.
Everything remains fluid. One soft report could shift the entire rate path narrative again. One hot report could put the hike firmly back on the table.
Why The Initial Rally Looked Stronger Than It Was
Looking back at Wednesday’s gains, several factors created an illusion of broad strength. Lower oil prices helped sentiment. Some cyclical areas performed well. The index-level advances masked the fact that the most popular AI trades were already losing sponsorship.
That kind of quiet rotation often precedes larger moves. Once the selling starts in earnest, the previously hidden weakness becomes the dominant story.
In my experience, markets rarely move in straight lines after major political events. The first reaction is frequently wrong or incomplete. Thursday’s session provided the first real stress test of the new political landscape, and risk assets failed that test for the moment.
How Different Types Of Investors Are Responding
Active managers who had been overweight the most expensive growth names are feeling the heat. Some will use the weakness to trim positions. Others may wait for clearer signals from the jobs data before making big changes.
Longer-term investors focused on free cash flow generation appear more comfortable. The large technology platforms that already generate substantial cash still look relatively well positioned compared with capital-intensive newer entrants.
Perhaps the most interesting aspect is how quickly the narrative shifted from “political clarity is good” to “political change creates new risks for AI spending.” Markets can change their minds in a single session when the story stops feeling simple.
Key Factors Worth Watching Closely
Several variables will determine whether Thursday’s decline becomes a short-lived shakeout or the start of a deeper correction.
- The actual October payrolls number and any revisions to prior months
- Comments from Federal Reserve officials after the data
- Signs of further rotation out of high-valuation growth stocks
- Any concrete policy signals that affect data center permitting or financing
- Oil price direction and its influence on inflation expectations
Each of these can move markets independently. Together they create a complex environment that demands flexibility.
The Broader Market Context
Before the election the major indexes had been grinding higher on the back of AI enthusiasm and expectations of eventual rate cuts. That combination produced strong returns for much of the year. The recent high on the Nasdaq now looks like a temporary peak rather than a permanent launching pad.
Corrections of ten percent are normal and healthy over the course of a long bull market. The question is whether this one stays contained or expands into something larger. History suggests that most corrections find a floor once the immediate catalyst is fully digested. Yet every cycle is different.
I’ve watched enough postelection periods to know that the market’s first verdict is rarely its final one. Policy details matter more than election night scores. Until those details emerge, volatility is likely to remain elevated.
What The Selloff Reveals About Investor Psychology
Fear of missing out had been a powerful force in AI-related names. When that fear flips into fear of holding the wrong stocks, the reversal can be sharp. Position sizes that felt comfortable during the uptrend suddenly feel too large.
Liquidity also plays a role. When everyone tries to reduce exposure at the same time, prices gap lower more easily. That dynamic was visible across many growth names on Thursday.
At the same time, the fact that the broader market has not completely collapsed suggests some underlying resilience. Buyers still appear willing to step in for high-quality companies at more attractive valuations.
Practical Considerations For Portfolio Positioning
No one has a perfect crystal ball. Still, a few principles seem useful right now.
First, distinguish between companies that need continuous external capital and those that can fund their own growth. The latter group tends to weather uncertainty better.
Second, pay attention to free cash flow trends. Strong cash generation provides a cushion when financing conditions tighten.
Third, keep an eye on the bond market. The recent drop in yields shows that some investors are already positioning for a more cautious Fed. If yields continue lower, that could eventually support equity valuations again. If yields reverse higher, the pressure on growth stocks may intensify.
Fourth, size positions according to volatility. Names that can swing ten or fifteen percent in a single day require smaller allocations for most investors.
Looking Ahead To The Next Few Sessions
Friday’s employment data will set the tone for the remainder of the week and likely the start of next week. A soft report could fuel hopes that the Fed stays on hold longer. A strong report might revive rate-hike concerns and extend the pressure on tech.
Beyond the numbers themselves, the market will parse every detail of the report. Wage growth, labor force participation, and the household survey all carry information that can influence the outlook.
After that, attention will shift toward any policy signals that emerge from the new political balance. Markets prefer clarity. Prolonged uncertainty tends to keep risk premiums elevated.
A Balanced Perspective On The Current Moment
It is easy to become overly pessimistic after a sharp down day. It is equally easy to dismiss the selloff as noise. The truth usually sits somewhere in the middle.
The postelection rally was always going to face a reality check. Political change introduces new variables around regulation, spending priorities, and geopolitical posture. AI infrastructure spending sits at the intersection of several of those variables.
Companies with strong balance sheets and existing capacity appear better equipped to navigate the period ahead. Those still racing to build capacity with borrowed money face a steeper climb.
For investors the message is not to abandon growth entirely. It is to demand higher quality and clearer paths to cash flow. That discipline often proves valuable when the market’s mood turns less forgiving.
Thursday’s session delivered a reminder that sentiment can shift faster than fundamentals. The jobs report and the weeks that follow will show whether the selling was an overreaction or the beginning of a more cautious phase. Either way, staying flexible and focused on company-specific strengths looks like the most practical approach right now.
Markets rarely give clear answers overnight. They do, however, reward those who separate temporary noise from lasting changes in the investment landscape. The current environment offers plenty of both.
As the dust settles from this abrupt reversal, the real work begins. Sorting through the damage, identifying the companies still positioned to execute, and preparing for whatever the next data release brings will separate reactive traders from thoughtful investors. The postelection chapter is only getting started, and the market has already shown it will not move in a straight line.