

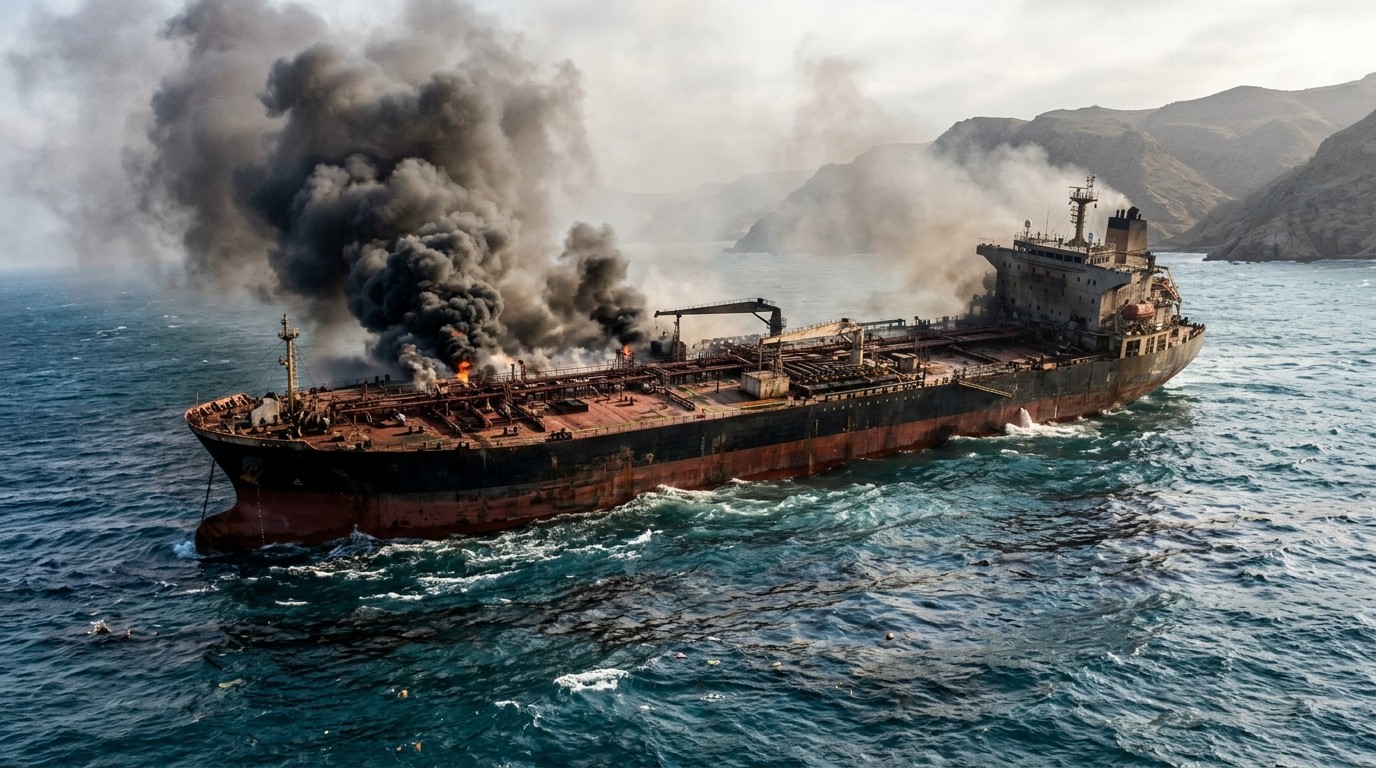
Iran Claims Four Oil Tankers Hit By Mines Near Strait Of Hormuz

Iran says four oil tankers were destroyed by mines near the Strait of Hormuz while two others were seized. Flows have already slipped from recent peaks and the security picture keeps getting worse. What happens next could reshape energy markets.
Financial market analysis from 05/11/2026. Market conditions may have changed since publication.
Have you noticed how quickly a single stretch of water can dominate global headlines again? Last week the market was still talking about recovering export volumes from the Middle East. This week the conversation has shifted hard toward risk. Iran’s Islamic Revolutionary Guard Corps stated that four oil tankers struck naval mines in an area south of the Strait of Hormuz that Tehran has marked as prohibited for navigation. The vessels are still on fire. Two additional ships were reportedly seized. The statement landed at a moment when crude flows had already begun to ease from their recent post-conflict peak, and the timing feels anything but accidental.
What Exactly Happened Near The Strait
According to the Revolutionary Guards, the four tankers hit mines in a zone Iran considers off-limits. The ships remain ablaze. Two other vessels were taken into custody. Details remain limited, which is typical in these situations. Names of the ships, flags, cargoes, and crew status have not been fully clarified in the initial reports. What is clear is the location: south of the Strait of Hormuz, one of the world’s most critical energy chokepoints.
I’ve followed tanker incidents in this region for years, and the pattern is familiar. First comes the official claim. Then comes a stretch of fog while commercial sources, satellite imagery, and tracking data try to catch up. Vessel operators often switch off automatic identification systems when transiting sensitive waters, which makes real-time confirmation harder. Trackers have already noted that they lean more heavily on satellite photos these days because the usual electronic trail can go dark.
The broader context matters. Attacks on commercial shipping in and around the Strait have picked up in recent weeks. Mines, explosions, and seizures are no longer isolated events. They form a rising trend that coincides with a measurable dip in seaborne oil movements from the Middle East.
Why The Numbers Already Look Softer
Middle East exports of crude, condensate, and fuels reached a post-war high in September. By October the total had slipped to roughly 17.1 million barrels per day from 18.9 million the month before. Separate tracking shows a drop of about one million barrels per day in crude and condensate alone. Flows through the Strait of Hormuz, the Red Sea, and the Gulf of Oman are estimated to have fallen to around 16.1 million barrels per day in October from 17.09 million in September.
Those figures are provisional. Analysts caution that the numbers can still be revised upward once more shuttle shipments and delayed reports surface. Still, the direction of travel is hard to ignore. Heightened risk is already showing up in the data.
October data shows Middle East seaborne oil exports have pulled back slightly from recent post-war highs on heightened risks in the Strait of Hormuz.
That assessment matches what many commercial observers are seeing on the water. When the security picture deteriorates, shipowners become more cautious. Some delay voyages. Others reroute. A few simply wait for clearer signals. The cumulative effect is lower throughput even if demand itself has not collapsed.
The Practical Reality Of Tracking Ships Right Now
Modern tanker tracking relies heavily on AIS signals. When vessels deliberately go dark, the picture becomes incomplete. Satellite imagery fills some of the gaps, but it is slower and more expensive. Analysts increasingly cross-check multiple sources before publishing firm numbers. That caution is healthy. It also means that early estimates of the October decline could shift once the full data set arrives.
In my view, the bigger story is not the precise daily volume. It is the rising friction cost of moving oil through this corridor. Every incident raises insurance premiums, lengthens voyage planning, and adds psychological weight to commercial decisions. Markets price that friction long before official statistics catch up.
A Closer Look At The Security Deterioration
The Revolutionary Guards’ statement did not arrive in a vacuum. The region has seen a series of attacks, mine placements, and vessel seizures in recent weeks. Each new event reinforces the sense that the maritime environment is less predictable than it was even a few months ago. Crews, owners, and charterers all adjust their risk calculations accordingly.
Some operators will continue to sail. Energy demand does not vanish overnight. Others will demand higher freight rates or additional security measures. A few may choose alternative routes when possible, although alternatives for Middle East crude are limited and often more expensive. The net result is tighter effective supply reaching certain destinations even if production itself remains steady.
Perhaps the most interesting aspect is how quickly the narrative can flip. Only weeks ago the conversation centered on the recovery of export volumes after earlier disruptions. Now the focus is back on physical risk to the vessels that carry those barrels. Markets have short memories, yet they react quickly when the risk materializes in concrete form.
What The Flow Data Suggests So Far
The October figures show a clear step down from September’s peak. Crude and condensate movements through the key waterways declined by roughly one million barrels per day on a provisional basis. Total Middle East seaborne oil exports, including fuels, fell by about 1.8 million barrels per day according to one widely cited tracker. Those are material numbers in a market that watches every hundred thousand barrels.
Trackers emphasize that the data remain subject to revision. Shuttle traffic and late-loading cargoes can push the final numbers higher. Even so, the initial signal is consistent across different monitoring services. Risk has risen and volumes have responded.
- September post-war peak in regional exports
- October decline of roughly 1.8 million bpd in total oil products
- About one million bpd drop in crude and condensate alone
- Provisional nature of the latest figures
- Growing reliance on satellite imagery for confirmation
These points are not abstract. They translate into higher voyage costs, longer waiting times, and greater uncertainty for refiners and traders who depend on steady Middle East supply.
How Markets Typically Respond To This Kind Of News
Energy markets rarely wait for perfect information. They price the risk premium first and refine the details later. When multiple tankers are reported hit by mines in a single statement, the immediate reaction is usually a firming of crude prices and a widening of certain freight differentials. Whether that reaction proves lasting depends on follow-through: additional incidents, successful attacks, or a rapid de-escalation.
In the current environment the baseline level of tension was already elevated. The latest claim adds another layer. Some market participants will interpret it as a temporary spike. Others will treat it as confirmation that the security situation has entered a new, more difficult phase. Both views can coexist for a while. Price discovery will sort them out.
I’ve found that the most useful approach is to watch three things simultaneously: official statements, commercial tracking data, and the behavior of freight rates and insurance costs. When all three move in the same direction, the signal is usually stronger than any single headline.
The Human And Operational Side Of The Story
Behind every tanker incident are crews who face real danger. Even when vessels are not sunk, fires, mines, and seizures create lasting stress for seafarers and their families. Shipping companies must weigh commercial obligations against duty of care. That calculation has become more complicated as the frequency of incidents rises.
Operational decisions also grow more complex. Routing through the Strait of Hormuz has always carried risk. Now the prohibited-zone designation and the reported mine strikes add a sharper edge. Masters and operators must decide how closely to approach the contested area, how long to keep AIS active, and what additional security protocols to activate. Those choices affect schedules, fuel consumption, and ultimately the cost of moving every barrel.
None of this is theoretical. It shows up in delayed arrivals, higher demurrage bills, and occasional cargoes that simply do not sail when planned. Over time the friction accumulates.
Looking At The Bigger Energy Picture
The Middle East remains the largest source of seaborne crude for many importing regions. Disruptions in the Strait of Hormuz therefore carry global weight. Even a modest sustained reduction in throughput can tighten balances, especially if other producers cannot or will not fill the gap quickly. Strategic petroleum reserves exist for a reason, yet they are finite and politically sensitive to draw down.
At the same time, the market has shown resilience before. Previous episodes of tension produced spikes that later faded when physical flows continued. The difference this time is the combination of a clear official claim of multiple tankers destroyed and an already visible pullback in October data. That combination is harder to dismiss as noise.
Perhaps the most telling indicator will be the behavior of loadings in the weeks ahead. If the October dip deepens in November, the story will shift from a one-month correction to a more structural concern. If volumes rebound quickly, the market will treat the latest incident as another chapter in a long-running security drama rather than a decisive turning point.
Why Provisional Data Still Matter
Analysts are careful to label the latest export figures as provisional. That caution is appropriate. Shuttle tankers, floating storage movements, and late-reported cargoes can alter the final tally. Yet provisional numbers still provide an early warning. They tell us that something shifted in October. The subsequent mine incident and vessel seizures reinforce the idea that the shift was not random.
Commercial trackers will refine the picture over the coming days and weeks. Satellite imagery will help confirm which vessels actually moved and which remained stationary. AIS gaps will be filled where possible. The eventual consensus numbers may be higher or lower than the first estimates. The direction of risk, however, already seems clear.
In my experience, markets tend to overreact to the first wave of incomplete information and then underreact once the fuller data arrive. The smart approach is to stay flexible, update assumptions as new facts emerge, and avoid anchoring too tightly to any single day’s report.
Possible Near-Term Scenarios
Several paths are open from here. One is further escalation: more mine strikes, additional seizures, or a broader campaign against commercial shipping. That path would likely push freight rates higher, widen risk premiums, and keep export volumes under pressure. Another path is a temporary pause. Official statements sometimes serve as signaling devices rather than the opening of a sustained campaign. In that case volumes could stabilize or even recover if operators regain confidence.
A third path sits in between. Sporadic incidents continue at a low level, enough to keep insurance costs elevated and voyage planning complicated, but not enough to cause a sharp sustained drop in throughput. That middle outcome has been common in past periods of regional tension. It produces a persistent but manageable risk premium rather than a full supply shock.
Which path materializes will depend on decisions taken far from the water. Commercial operators will adapt to whatever environment they face. The rest of the market will watch the tankers, the data, and the official rhetoric for clues.
The Role Of Satellite Imagery And Alternative Tracking
When AIS goes dark, other tools step in. High-resolution satellite photos can confirm whether a vessel is still moving, whether smoke is visible, or whether it has changed position relative to known landmarks. Optical and radar imagery each have strengths. Cloud cover and darkness limit optical systems. Radar can penetrate weather but offers less visual detail. Analysts combine both when possible.
The increased reliance on these methods is itself a sign of the times. In quieter periods, AIS alone is usually sufficient. When the security environment deteriorates, the electronic trail becomes incomplete by design. That forces greater investment in alternative verification. The result is slower but often more reliable information once it arrives.
For market participants the practical implication is simple. Early reports should be treated as provisional. Final conclusions about volumes and incidents should wait for multi-source confirmation. Patience is not always easy when prices are moving, yet it reduces the chance of reacting to incomplete pictures.
What This Means For Broader Energy Balances
A sustained reduction of one million barrels per day from Middle East seaborne crude is large enough to matter. It can tighten global balances, especially if demand remains firm and other producers are already running near capacity. Refiners in Asia and Europe that rely on Middle East grades would feel the impact first through higher delivered costs or the need to seek alternative supply.
Strategic stocks can buffer short disruptions. They are less effective against prolonged reductions. Governments are generally reluctant to release reserves except in clear emergencies. Private inventories provide another cushion, yet they too are finite. The longer any shortfall persists, the more the market must rebalance through higher prices or reduced consumption.
None of this is inevitable. Flows could rebound if the security situation stabilizes. Production from other regions could increase. Demand could soften for unrelated reasons. Still, the latest combination of official claims and softer October data raises the probability of tighter conditions in the near term.
Keeping Perspective Amid The Headlines
Energy markets have lived with Strait of Hormuz risk for decades. The waterway has never been fully closed for long, yet the threat of disruption has repeatedly influenced prices and planning. Each new episode feels urgent in the moment. Over a longer horizon most episodes fade into the background once physical flows resume.
The current situation contains both familiar and new elements. The familiar part is the geopolitical tension and the official statements that accompany it. The newer part is the clearer evidence of a volume pullback already underway before the latest mine claims. That sequencing matters. It suggests the market was already adjusting to higher risk before the most recent incident.
For observers the useful stance is measured attention rather than either complacency or alarm. Watch the tankers. Watch the data. Watch the freight and insurance markets. Those real-world indicators will reveal more than any single statement.
Practical Takeaways For Market Watchers
Several points stand out after reviewing the available information. First, four tankers are reported destroyed by mines and still ablaze, with two additional vessels seized. Second, Middle East oil exports have already eased from their September peak. Third, tracking has become more difficult because many vessels disable transponders in the area. Fourth, the security environment has deteriorated in recent weeks beyond the single latest incident.
- Treat early volume estimates as provisional and expect revisions.
- Monitor freight rates and insurance costs for real-time risk signals.
- Follow satellite-based tracking updates as AIS gaps persist.
- Distinguish between one-off incidents and a sustained campaign.
- Remember that physical flows ultimately matter more than statements.
These steps will not eliminate uncertainty. They will help keep analysis grounded in observable developments rather than pure narrative.
The Longer View On Chokepoint Risk
Every major energy chokepoint carries structural risk. The Strait of Hormuz is simply the most consequential for oil. Geography cannot be changed. Political and military realities around it can shift, sometimes quickly. Commercial operators adapt by adjusting routes, security protocols, and pricing. Governments adapt by maintaining strategic stocks and diplomatic channels. Markets adapt by pricing risk premiums that rise and fall with the perceived threat level.
The latest reports fit into that longer pattern. They also add a concrete data point: multiple tankers hit in a single claim, fires still burning, and an already visible dip in October flows. That combination elevates the story above routine background noise.
Whether the episode proves temporary or marks a more lasting change in the operating environment remains to be seen. The tankers still on fire, the vessels reported seized, and the softer export numbers already on the board give the market plenty to digest in the meantime.
For now the practical response is straightforward. Stay informed, stay flexible, and let the evolving data on actual movements guide the next set of conclusions. The Strait of Hormuz has surprised observers before. It may do so again. The only reliable constant is that risk in this corridor rarely stays quiet for long once it begins to surface.
The coming days and weeks will clarify how far the current tensions extend and how commercial shipping responds. Until then the combination of official claims, burning tankers, and softer flow data provides a clear reminder that energy security still depends on a narrow stretch of water that remains under pressure.
Investing should be more like watching paint dry or watching grass grow. If you want excitement, take $800 and go to Las Vegas.


Solana Price Falls Below $90: Oversold RSI Relief?

Wall Street Postelection Rally Collapse And What Comes Next
Related Articles

Bank Of England History Facts And Why It Still Matters Today
Most people think they know the Bank of England. Then they discover the gold buried under Threadneedle Street, the giant banknotes, and the quiet power that still shapes every mortgage and wage rise. The full story goes much deeper than most expect.

Five States Selected for $50 Billion Nuclear Innovation Campuses
Five states just won the right to host enormous nuclear campuses that could bring $50 billion in investment and thousands of high-paying jobs. But not every pro-nuclear state made the list – here's why the full fuel cycle matters more than ever.
How Amazon’s Prime Tricks Users: FTC Lawsuit Unveiled
Did Amazon trick you into Prime? The FTC says deceptive tactics lured millions. Discover the lawsuit's shocking claims and what it means for you...