
Have you ever left a few thousand dollars sitting in a checking account because moving it felt like a chore? I have. Most households have. That lazy cash is not lazy to banks. It is cheap fuel. Now imagine a personal software agent that never gets tired, never forgets a rate, and can hop your balance to a better yield before breakfast. That is the unease spreading through parts of finance this month, and it is not science fiction anymore.
Why Bank Stocks Suddenly Look Fragile Again
Bank shares have had a rough stretch. A widely followed bank exchange-traded fund dropped more than two percent last week and posted its third weekly loss in a row. That kind of streak has not shown up since early spring. Month to date the same basket is down close to six percent, which would rank among its weakest months in more than a year if the slide holds. A handful of large lenders and brokerage names have fallen even harder, some off eight or nine percent in September alone.
The first explanation is almost too familiar. Interest rates jumped as traders priced a tougher policy path after energy prices firmed. Higher yields can squeeze loan demand. They can also reprice funding. None of that is new. What is new is a second worry riding on top of the rate story: software that treats your cash like a living portfolio instead of a forgotten leftover.
In my experience, markets love a simple villain. Rates are simple. An agentic AI that quietly reallocates household cash is less simple, and that is why the idea is sticking. It sounds dramatic. It also maps onto something banks have relied on for decades: inertia.
The Cheap Deposit Habit Banks Still Count On
Traditional checking still pays almost nothing at many institutions. The national average yield on those balances has been cited around one tenth of one percent. That is not a rounding error in a household budget. It is a rounding error in a system that funds trillions in loans with sticky, low-cost money.
Fintech deposit products already advertise several percentage points more. One well known digital lender has been offering around four and a half percent. Other cash products sit in a three to five percent band depending on the week. The gap is not subtle. People tolerate it because switching takes time, paperwork, and a little trust. Habits win. Until they do not.
If every household used AI agents to optimize the return on their cash balances, banks could lose a large share of the cheap deposits they rely on to make loans, which would be a problem for the entire financial system.
– A chief economist at a major asset manager
That line is doing the rounds for a reason. It is not a prediction of teller lines and boarded-up branches. It is a funding story. Loans need deposits or something that behaves like deposits. If the cheapest layer walks, the cost of the next layer rises. Margins compress. Credit gets pickier. Growth slows. You do not need a classic panic for that chain to hurt.
What An Agentic Sweep Would Actually Do
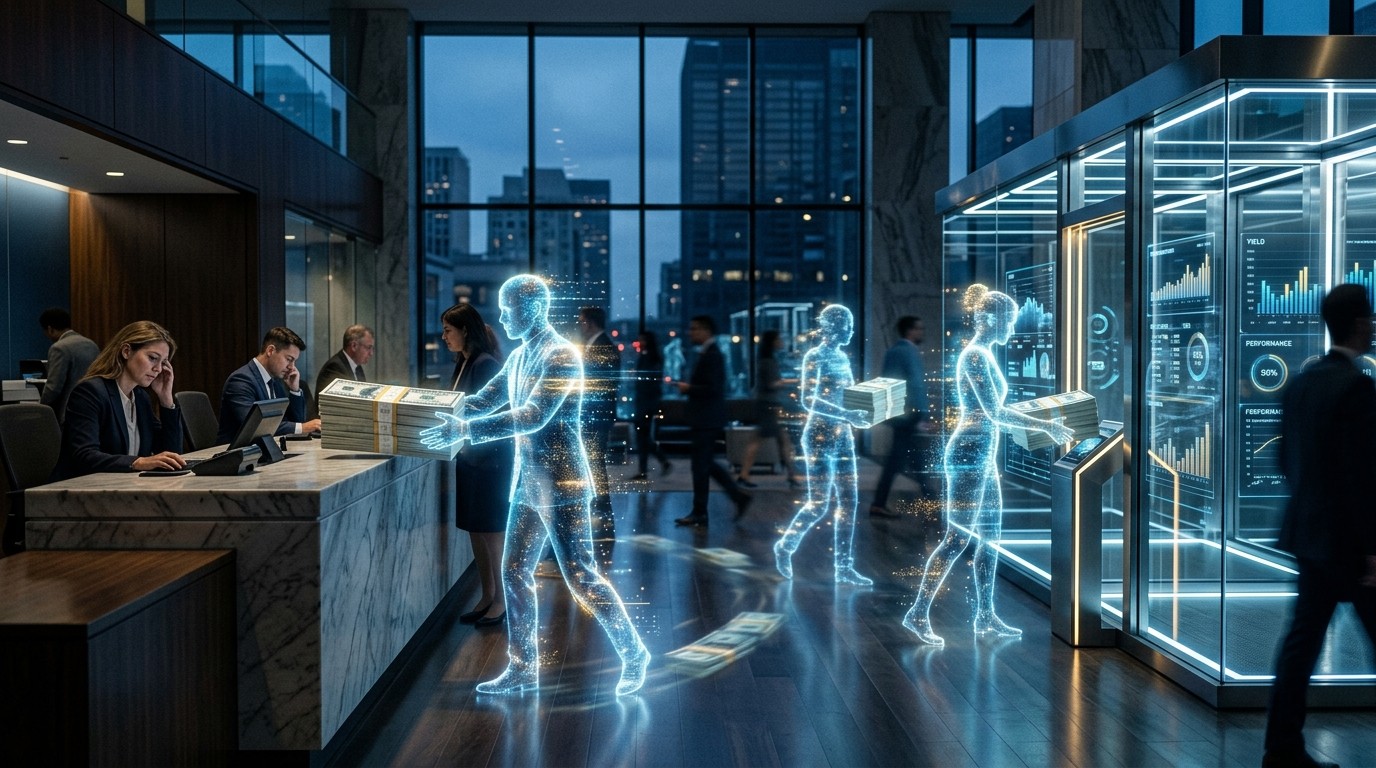
Think of an agent as a tireless assistant with permission to watch rates, rules, and your cash buffer. It does not need you to open five apps on a Sunday night. It can keep a spending float where you need it and park the rest where the yield is better, then pull funds back when a bill hits. That is the product vision behind several new assistants now being demoed.
The pitch is almost boring when you say it out loud. Keep enough in checking to avoid overdrafts. Sweep the surplus. Repeat. The boring version is exactly why it scales. People do not love banking chores. They love outcomes. An agent that captures three extra points on idle cash without drama will feel like free money.
- Households keep a small operational balance in everyday checking.
- Agents compare insured cash products and short-duration yield options.
- Surplus funds move automatically inside set risk and liquidity rules.
- Banks that underpay lose the slush layer first, then maybe more.
I keep coming back to one detail. The national checking average near 0.1 percent versus cash products in the mid single digits is not a rounding debate. It is a standing invitation. Agents do not feel loyalty. They feel spreads.
Rates Are Already Doing Part Of The Job
Treasury yields climbing to multiyear highs change the mood even before software enters the chat. Higher policy-sensitive rates can cool loan growth. They also make the opportunity cost of dead cash obvious. You do not need an agent to notice a five percent money market fund when your checking account still looks like a relic from another decade. You just need a push.
Bank stocks have been trading that tension. Large lenders in the same fund have lagged, and so have a few brokerage platforms that live closer to the cash-management conversation. When yields jump, the market starts asking who owns the cheap float and who has to pay up to keep it.
Perhaps the most interesting aspect is timing. This is not a crisis tape. It is a grinding tape. Three down weeks. A month that looks sloppy. That is usually when structural stories get a hearing because traders want a narrative that lasts longer than one data print.
Why This Is Not A Classic Bank Run
Language matters. A run implies fear, queues, and a race for the door. Nobody serious is saying that is happening now. There are no crowds. There is no freeze. Liquidity in the system is still ample by many standard gauges. The phrase circulating is closer to a slow leak with better software.
That distinction is not academic. Classic runs are about solvency panic. An agentic shift is about yield math and convenience. Customers may still love their bank app for payments. They may simply refuse to leave a fat cash pile earning dust. Those are different problems. One is existential in a weekend. The other is a multi-quarter margin squeeze.
There are no signs that a run on the banks is happening, or will happen, anytime soon. The risk is quieter: easier movement of cash toward higher-yielding accounts.
I find that quieter version more plausible, which is why it deserves attention. Loud risks get war-gamed. Quiet ones get shrugged off until the deposit mix has already changed.
The Funding Math Banks Cannot Ignore
Cheap deposits are not a side dish. They are how many balance sheets stay profitable when credit is competitive. If a meaningful share of noninterest or low-interest balances migrates, banks have choices, and none of them are free.
- Pay more on deposits and accept thinner net interest margins.
- Replace lost funding with wholesale money that can vanish faster.
- Slow loan growth and protect capital ratios instead of expanding.
- Push customers into products that lock funds longer, which can annoy them.
Each path has a market reaction attached. Higher deposit betas look defensive until earnings season. Wholesale funding looks fine until spreads gap. Slower lending looks prudent until growth investors walk away. There is no elegant off-ramp if the cheap layer thins out at scale.
| Cash Home | Typical Yield Picture | Stickiness |
| Everyday checking | Near 0.1% in many averages | High from habit, low from yield |
| Digital savings | Often mid single digits | Medium, rate sensitive |
| Brokerage cash sweep | Competitive, product dependent | Medium, easy to move |
| Short Treasuries and funds | Tracks market yields | Lower operational friction now |
Look at that grid long enough and the agent story writes itself. The first row is where banks still harvest comfort. The other rows are where software already lives.
Household Behavior Is The Real Wildcard
People are not perfectly rational, and that still protects banks. Plenty of customers will never grant an agent permission to touch payroll, rent, or the account they use for groceries. Trust is uneven. Older savers may prefer a branch face. Some households keep large buffers because they hate the feeling of a tight account, even if the extra cash earns almost nothing.
Then there is the other camp. Younger users already treat banking like a set of pipes. They will try a new cash product for half a point. Give them an agent that handles the comparison and the transfer, and inertia shrinks. I have found that once someone sees a monthly yield number that used to be invisible, they do not unsee it.
So the adoption curve may be lopsided. Not a stampede. A split. High-balance, digitally comfortable households move first. That cohort happens to be valuable. Banks can lose the profitable float without losing the customer relationship on paper. Ugly combination.
Fintech Already Built The On-Ramp
The plumbing exists. High-yield cash accounts, instant transfers, and clean mobile flows are no longer boutique experiments. What agents add is persistence. A human checks rates twice a year if you are lucky. An agent can check daily and act inside guardrails you set once.
That persistence changes the competitive clock. A bank can match a teaser rate for a marketing window. Matching a tireless optimizer is different. You either stay in the rate fight continuously or you concede the surplus cash. Continuous rate fights are expensive. Concession is also expensive. Pick your poison.
I do not think every digital brand becomes a winner by default. Some will overpay for deposits and discover that growth bought with yield is rented, not owned. Still, the direction of travel is clear. Cash is becoming a product again instead of a forgotten byproduct of a checking relationship.
What Investors Should Watch In The Next Few Quarters
Stock screens will keep obsessing over net interest income. Fair enough. Dig one layer deeper. Deposit mix, deposit beta, and the share of noninterest-bearing balances tell the agent story earlier than a headline loan number.
- Are noninterest-bearing deposits still shrinking after rate peaks?
- How fast are banks lifting advertised cash yields to defend balances?
- Is loan growth slowing because demand is soft or because funding got dear?
- Do brokerages and digital banks keep taking share of household cash?
Those questions sound dry. They are the difference between a temporary rate scare and a structural funding reset. I would rather be early and a bit paranoid on mix than late and shocked by a margin print.
Policy And Stability Angles People Skip
If agents make cash hyper-mobile inside the insured system, stability does not automatically collapse. Money can leave one bank and land in another insured account. That is rotation, not destruction. The system-wide problem appears if the rotation concentrates in a few fast-moving platforms or if banks reach for riskier assets to replace lost spread.
Regulators already live with rapid digital transfers. The new wrinkle is automation at household scale. Rules written for humans who click once a quarter look different when software clicks every night. Liquidity coverage, intra-day settlement, and operational resilience all get a little less theoretical.
None of that requires a doomsday speech. It does require banks and supervisors to treat deposit stickiness as a variable, not a birthright. That mental shift is overdue.
How Households Can Use The Shift Without Getting Cute
If you sit on idle cash, the lesson is not to hand every password to a black-box bot tomorrow. The lesson is to stop treating checking as a savings vehicle. Keep an operating buffer. Put the rest in something that pays a real yield and stays liquid enough for your life.
Set rules before you set automation. Maximum transfer size. Minimum checking floor. Only insured products if that is your comfort zone. Review the activity. Agents are tools. Tools still need an owner who glances at the dashboard.
Simple cash stack:
  1 to 2 months of bills in checking
  Surplus in high-yield insured cash
  Extra reserve in short government paper if you can tolerate a click or two
  No heroics with money you need next week
That stack is not clever. It is adult. Clever is how people blow up a good idea. Adult is how they keep the extra yield and still sleep.
What Banks Can Still Do Before The Window Closes
Defending cheap deposits with slogans will not work. Relationship value has to show up as speed, advice, credit access, or a cash rate that is not embarrassing. Some lenders will unbundle. Offer a sharp cash product and keep the rest of the franchise. Others will bundle harder and hope convenience outweighs yield. Both can work in pockets. Neither works if the cash product is an afterthought.
Technology spend should follow the threat. If agents are going to shop rates, banks need clean APIs, instant movement, and transparent yield pages. Friction used to be a feature. Friction is now a leak.
I am skeptical of the idea that every regional lender can out-yield the specialists. They can out-serve them in credit and local knowledge. That only matters if customers still notice those strengths after the cash has already left.
The Market Narrative Can Overshoot Either Way
It is easy to turn a thoughtful funding note into a horror poster. Resist that. It is also easy to laugh it off because nothing exploded this week. Resist that too. The honest middle is a gradual rise in deposit costs and a more competitive fight for household cash, accelerated by software that removes excuses.
Bank valuations already bake in a lot of rate sensitivity. Adding agent risk on top can justify a higher risk premium for names that still lean hardest on noninterest balances. Names with diversified fees or stronger cash products may shrug. Dispersion inside the sector is the trade, not a blanket short of every ticker with a vault logo.
Will the phrase agentic bank run age well? Maybe not as a literal forecast. As a shorthand for the death of deposit inertia, it might. Words stick when they name a feeling investors already had.
A Grounded Way To Think About The Next Year
Start with what is already true. Checking still underpays. Market yields are visible. Digital transfers are fast. Households got a multi-year education in shopping for cash during the last rate cycle. Agents compress the last mile of effort.
Then add what is not true yet. Mass permissioning of fully autonomous money movers is not universal. Many people still want a human veto. Banks still hold enormous operational balances tied to payroll and bill pay. Those anchors do not vanish because a demo looks slick.
Put those together and you get pressure, not collapse. Pressure on margins. Pressure on product design. Pressure on anyone who assumed cheap float was a permanent moat. That is enough to matter for earnings, hiring, and credit availability. It is also enough to matter for households that finally get paid something for cash they used to ignore.
If there is a personal takeaway I keep repeating to friends, it is this. Do not wait for a cinematic bank run headline to clean up your cash. The unglamorous version is already here. Rates moved. Apps improved. Agents are next. The people who treat surplus checking like an accident will keep donating yield to someone else’s net interest margin. The people who set a floor, sweep the rest, and stay liquid will look slightly boring and slightly richer. Boring still wins.
And if you work inside a bank, the same advice flips. Assume your most rate-aware customers will soon have help. Price the relationship as if inertia is fading. Because it is. Not all at once. Fast enough to show up in the mix. That is the specter worth planning around while the tape is only messy, not broken.