

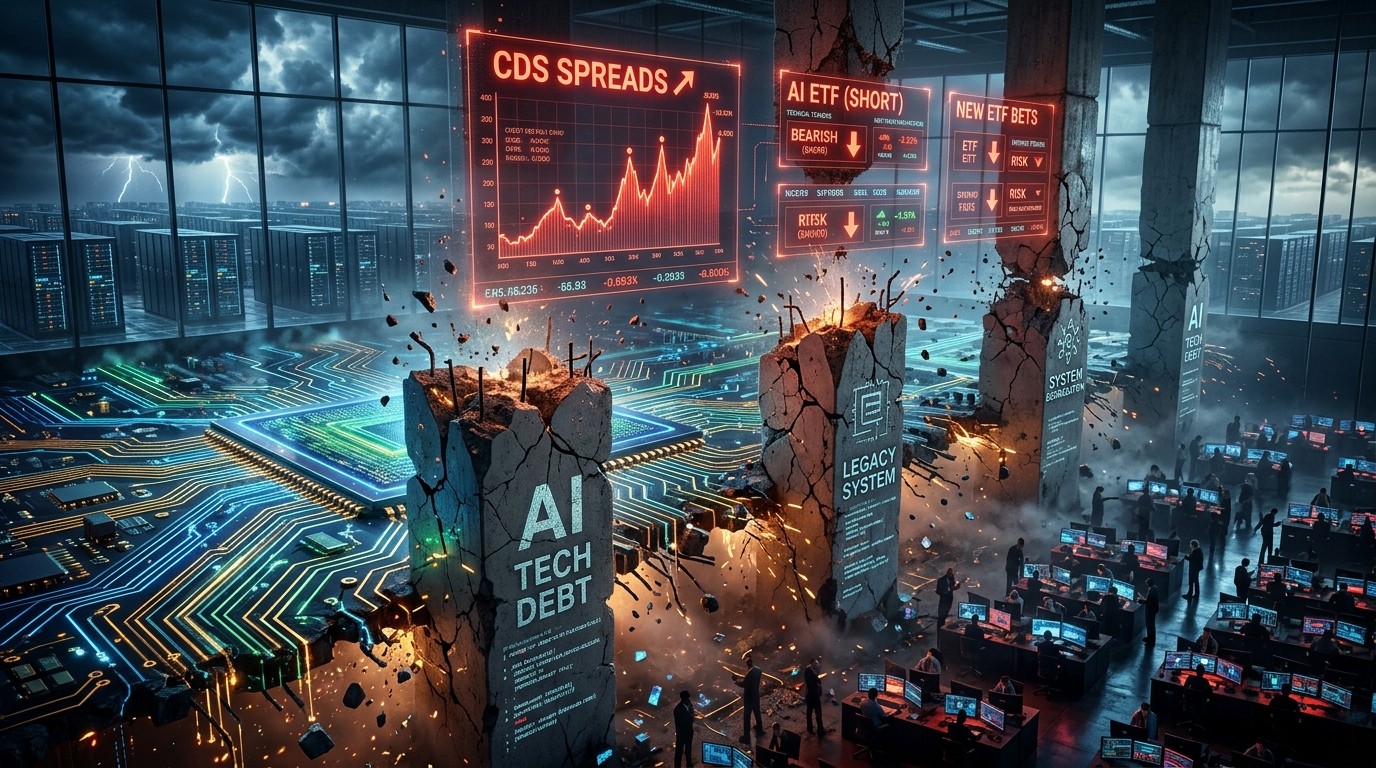
AI Debt CDS ETFs Target CoreWeave Oracle Risks

Investors can now bet against the AI buildout through brand-new CDS ETFs targeting CoreWeave and Oracle. Spreads are already flashing distress signals, and the products could change how smaller players hedge the entire trade. What happens next is...
Financial market analysis from 18/11/2026. Market conditions may have changed since publication.
I’ve been watching the AI trade long enough to know that the loudest conversations usually happen around stock prices. Yet the quieter, more telling signals often come from the credit markets. Right now those signals are flashing in a way that feels different. Credit default swap spreads on several names tied to the artificial intelligence buildout have widened sharply, and two ETF managers are preparing products that would let investors profit if those spreads keep moving higher.
Why AI Credit Risk Suddenly Matters More Than Ever
The past year has been defined by enormous capital commitments. Companies racing to build data centers and secure power have taken on significant debt. Some of the newer players, often called neocloud providers, carry balance sheets that look stretched even by growth-company standards. When free cash flow turns negative for the largest technology names at the same time, the market starts pricing higher odds that something could go wrong.
I’ve found that credit markets tend to notice trouble before equity investors fully price it in. Wider CDS spreads simply mean protection against default has become more expensive. In plain terms, the people who trade these contracts are demanding higher premiums because they see elevated risk. For CoreWeave the five-year spreads recently sat in the 1,100 to 1,200 range. Numbers above 1,000 usually get labeled as distressed territory. Oracle’s contracts have climbed from under 80 to levels north of 300 over the same stretch. Even the biggest technology names have seen spreads more than double as heavy AI spending pushed free cash flow into negative territory.
That backdrop explains why specialized funds focused on these exact contracts are now being prepared. The idea is straightforward. The funds would gain when spreads widen further and lose value if credit conditions improve. They are not designed to move inversely to the underlying stock prices, a point the filings make clear. They also carry the ongoing cost of the protection premiums themselves.
The Players Filing For These Specialized Portfolios
Two managers known for creative ETF structures have submitted filings. One focuses on single-name exposure to CoreWeave and Oracle alongside broader packages. The other takes a similar approach that includes a basket tied to the group of large technology companies most closely associated with the AI infrastructure wave. Both plan to use leverage, which means daily moves could be amplified in either direction.
In my experience, products like these rarely attract the average individual investor right away. The founder of one of the firms noted that the real audience is more likely to be smaller institutions and family offices. Those groups often want CDS exposure but lack the size or internal expertise to trade the contracts directly with major banks. An ETF wrapper removes some of the operational friction and delivers the exposure in a familiar vehicle.
Still, the managers are realistic about scale. One said the target is simply a path toward roughly twenty million dollars in assets, the approximate break-even point for many of these specialized strategies. Anything beyond that would be upside. That kind of modest ambition actually makes the filings more believable. They are not promising to reshape the entire ETF landscape overnight.
How Credit Default Swaps Actually Work In This Context
A quick refresher helps. A credit default swap is essentially an insurance contract. One party pays a regular premium. The other party agrees to cover losses if the referenced company fails to meet its debt obligations. When the market grows more worried, the premium, expressed as a spread in basis points, rises. When confidence returns, the spread tightens.
The proposed funds would hold positions that benefit from rising spreads. That means they pay the premiums and hope the cost of protection keeps climbing. The structure is closer to a long-volatility or long-credit-risk trade than a simple short of the stock or the bonds. Because of the leverage, a sharp move in the underlying spreads can produce outsized daily percentage changes, both positive and negative.
Perhaps the most interesting aspect is the timing. These filings arrive after a stretch in which AI-related debt concerns have already moved the needle. Bond yields on certain CoreWeave notes have approached levels that would have looked extreme only a short time ago. The combination of heavy capital spending and questions about future funding sources has created the exact environment these products aim to capture.
The Role Of Large Technology Balance Sheets
It is easy to focus only on the newer, more leveraged names. Yet the largest technology companies have also seen their credit spreads climb. Heavy investment in artificial intelligence infrastructure has turned free cash flow negative for several of them. Even though their overall balance sheets remain far stronger than those of pure-play neocloud operators, the market has still marked the risk higher.
One way to think about it is that the entire ecosystem is interconnected. Many of the smaller players depend on ongoing relationships with the major chip and cloud providers. When leadership changes or capital allocation priorities shift at the center of that network, the ripple effects can reach the outer companies quickly. Recent comments from large asset managers have highlighted exactly that dependency.
I’ve watched similar cycles in other capital-intensive sectors. When the central financing engine slows, the most aggressive growth stories feel the pressure first. That does not mean defaults are imminent. It does mean the cost of insurance against those outcomes can keep rising for a while, and that is the opportunity these ETFs are built to express.
Potential Benefits And Clear Limitations
For investors who already understand credit markets, the appeal is obvious. Access to single-name and basket CDS exposure without needing a prime brokerage relationship or the operational setup required to trade the contracts directly. The funds could serve as a targeted hedge against a broader portfolio of AI-related equities or as a pure directional bet on further deterioration in credit metrics.
At the same time, several practical limitations stand out. The ongoing cost of the premiums acts as a constant drag. If spreads simply stabilize or grind tighter, the funds can lose value even if the underlying companies continue to face questions. Leverage amplifies both the gains and the losses on a daily basis, which means holding periods need careful management. And the products are unlikely to track equity price movements in any reliable way, something the prospectuses emphasize.
ETF strategists I speak with regularly have mixed feelings. Some see limited demand beyond a narrow professional audience. Others note that retail interest often appears precisely when headlines about stress become loudest. Scary stories about capital expenditure and funding gaps can create exactly the kind of curiosity that draws smaller accounts into complex products. Whether that curiosity turns into lasting assets under management remains an open question.
What Wider Spreads Have Already Told Us
Looking at the numbers already on the board helps set expectations. CoreWeave’s longer-dated bonds have traded at yields that reflect genuine market concern. Spreads in the four-digit range do not appear overnight without real questions about leverage, cash burn, and refinancing paths. Oracle’s move from tight levels into the mid-hundreds shows that even established technology issuers are not immune when spending ramps aggressively.
The larger technology group has experienced its own version of the same story. Spreads that once sat near multi-year lows pushed to five-year highs earlier this month. That kind of simultaneous move across both the core names and the more leveraged satellites is rare. It suggests the market is reassessing the entire financing model behind the current AI investment cycle rather than focusing on any single weak link.
In practical terms, the proposed ETFs would give smaller players a way to express a view on those same dynamics. Whether the products ultimately attract meaningful capital will depend on how long the current stress persists and how clearly the managers communicate the risks and the mechanics.
Leverage And Daily Reset Dynamics
Anyone considering these funds needs to understand the leverage component. Daily reset leveraged products can behave in ways that surprise investors who hold them for longer than a few sessions. Compounding effects work in both directions. A series of up days followed by a sharp reversal can leave the fund value lower than a simple multiple of the underlying move would suggest.
That feature is not unique to these CDS strategies. It already exists in the many single-stock leveraged and inverse ETFs that trade actively. The difference here is that the underlying instrument is a credit spread rather than an equity price. Credit spreads can gap and stay elevated for extended periods, or they can collapse quickly if funding conditions improve. Either path creates a different risk profile from the more familiar equity products.
I’ve always preferred to treat leveraged credit exposure as a tactical tool rather than a core holding. The same logic should apply once these ETFs become available. Short holding periods, clear thesis, and strict risk limits make more sense than a set-it-and-forget-it approach.
Institutional Versus Retail Demand
The managers themselves seem to expect the bulk of interest from the institutional side of the market. Smaller hedge funds, family offices, and specialized credit desks often look for efficient ways to express relative-value or directional views without building full operational infrastructure. An ETF that delivers clean CDS exposure can fill that gap.
Retail participation is harder to predict. Complex credit products have historically struggled to attract lasting individual-investor assets unless the underlying story becomes a mainstream media narrative. The current AI spending debate already occupies plenty of headlines. If those headlines continue to focus on funding risks and balance-sheet strain, curiosity could spill over into these new vehicles. Whether that curiosity survives the first period of premium decay is another matter.
One experienced ETF observer put it bluntly: products like these often end up serving as short-term speculation tools rather than long-term portfolio solutions. That observation feels accurate. The more interesting question is whether the speculation itself can reach the modest asset levels the managers need to keep the funds viable.
Broader Implications For The ETF Landscape
These filings fit a longer trend. The ETF industry has steadily expanded into more complex risk exposures. Volatility, single-stock leverage, thematic baskets, and now targeted credit-spread strategies all reflect the same underlying demand for precise, liquid expressions of market views. Regulators have generally allowed the innovation as long as the risks are disclosed clearly.
If the CoreWeave and Oracle products receive approval and gather assets, it is reasonable to expect follow-on filings focused on other high-profile credit stories. The template is already clear: identify a sector where spreads have become volatile, package the exposure with leverage, and market it to investors who want a convenient way to participate.
Whether that evolution is healthy for the broader market is a separate conversation. Greater access to credit-risk tools can improve price discovery. It can also amplify short-term swings when speculative capital piles in and then exits. Both outcomes are possible, and both have appeared in earlier waves of ETF innovation.
Practical Considerations Before Any Launch
Approval is not automatic. The Securities and Exchange Commission will review the filings for disclosure quality, operational readiness, and investor-protection issues. Past experience with complex products suggests the process can take months and may involve additional questions about how the funds will source and roll the underlying CDS contracts.
Liquidity in the single-name CDS market itself also matters. CoreWeave and Oracle contracts trade with reasonable size, but the market is still thinner than the equity options market for the same names. The ETF managers will need reliable counterparties and clear procedures for managing rolls and potential disruptions.
Investors who eventually use the products should pay close attention to the total expense ratio, the expected tracking characteristics, and the tax treatment of any gains or losses. Credit derivatives can generate different tax outcomes from ordinary equity ETFs, another detail worth clarifying before any capital is committed.
A Different Kind Of Hedge For The AI Trade
Most investors who want to reduce exposure to the AI theme simply sell stocks or buy put options. The new CDS funds offer a different route. They focus on the credit side of the capital structure rather than the equity side. That distinction can matter when equity valuations remain elevated even as credit metrics deteriorate, or vice versa.
In periods when equity markets stay optimistic about long-term growth while credit markets grow cautious about near-term funding, a pure credit expression can capture a risk that equity hedges miss. Of course the reverse can also occur. The key is recognizing that the two markets sometimes tell different stories about the same companies.
I’ve always believed that the best risk-management tools expand the range of available expressions rather than replace existing ones. These ETFs, if launched, would add one more option to the toolkit. Whether they become widely used or remain niche products will depend on how the underlying credit story develops over the coming quarters.
Looking Ahead At The Funding Environment
The larger backdrop remains the enormous capital required to build out AI infrastructure. Data centers, power agreements, specialized chips, and networking equipment all demand funding. Some of that capital comes from free cash flow at the largest companies. Some comes from debt markets. Some comes from specialized financing arrangements that sit outside traditional public bonds.
Any shift in the willingness of key players to continue providing that capital can change the outlook quickly. Recent comments from major alternative asset managers have already highlighted the dependency of certain projects on ongoing support from the central technology providers. If that support becomes less automatic, the credit spreads of the more leveraged names could widen further.
That possibility is exactly what the new ETFs are designed to capture. They will not create the risk. They will simply package an existing market view into a more accessible form. For investors who already monitor CDS levels closely, the convenience could prove useful. For everyone else, the products serve as a reminder that the AI story has always contained a significant credit component that equity prices alone do not fully reflect.
The next few months will show whether the filings move forward and whether investor interest materializes. In the meantime the underlying spreads continue to trade, the capital expenditure plans remain ambitious, and the questions about long-term returns on that investment stay open. Credit markets have already begun to price a more cautious scenario. The proposed ETFs simply offer a structured way to participate in that pricing.
At the end of the day, every investment cycle eventually tests the balance sheets of the companies driving it. The current AI cycle is no exception. The appearance of specialized credit products is one more sign that the testing phase has begun in earnest. How severe that test becomes, and how investors choose to position around it, will shape returns across both equity and credit markets for some time to come.
Money is a terrible master but an excellent servant.

Related Articles

Why Are Fewer Women Using Birth Control Pills?
Why are women ditching birth control pills for fertility apps? Discover the surprising trends reshaping reproductive choices and what it means for relationships...
Iran’s Nuclear Talks: Transparency for Sanctions Relief
Iran's ready to open its nuclear program for inspection, but only if sanctions are lifted. Will the US agree, or is a bigger conflict brewing? Click to find out...
RFK Jr.’s Bold HHS Vision Sparks Debate
RFK Jr. shakes up Congress with bold HHS reforms, from fluoride bans to addiction crackdowns. Will his MAHA vision unite or divide? Click to find out!