
Have you ever stopped to wonder what happens when the world’s biggest buyer of specialized metals suddenly decides it will no longer accept material that touched certain countries? That quiet policy shift is already reshaping one of the most overlooked corners of the commodity markets, and Monday’s gathering of mining analysts in New York may mark the moment the rest of Wall Street starts paying closer attention.
Why Tungsten Suddenly Matters More Than Most Investors Realize
Tungsten is not a glamorous metal. It does not sparkle in jewelry or power electric vehicles the way lithium does. Yet its combination of extreme density and heat resistance makes it almost irreplaceable in armor-piercing rounds, missile components, aircraft engines, and a long list of other defense applications. When governments decide they need more of those systems, the demand for reliable tungsten does not wait for convenient market conditions.
For years the global supply chain has been dominated by a handful of producers, with the largest share concentrated in one region. That concentration worked fine until geopolitical tensions rose and Western defense planners began treating the metal as a strategic vulnerability. The result is a slow but deliberate effort to build alternative sources that can prove their material never passed through restricted hands.
I’ve followed several of these critical-material stories over the past couple of years, and tungsten stands out because the technical requirements are unusually strict. Simply processing the ore in a friendly country is not enough if the original concentrate came from a designated source. That detail changes the entire competitive landscape for any miner that can deliver fully compliant product.
The Approaching Procurement Deadline
Starting in early 2027, U.S. defense purchasing rules will expand beyond melting and manufacturing steps to cover mining, refining, and separation as well. Covered products that originate in certain countries will face sharp restrictions, even if they are later processed elsewhere. The practical effect is that many existing supply routes will become difficult or impossible to use for military contracts.
That timeline is not distant anymore. Companies that can show continuous, verifiable production of compliant concentrate stand to gain a structural advantage. Miners still in the exploration or permitting phase will find themselves racing against the same clock with far less flexibility.
In my view, the market has only partially priced this shift. Prices for ammonium paratungstate have pulled back from their recent peaks, yet the underlying tightness in finished Western material has not disappeared. Concentrate availability remains constrained, and that constraint is likely to intensify as the new rules approach.
Sangdong’s Quiet Progress Toward First Shipments
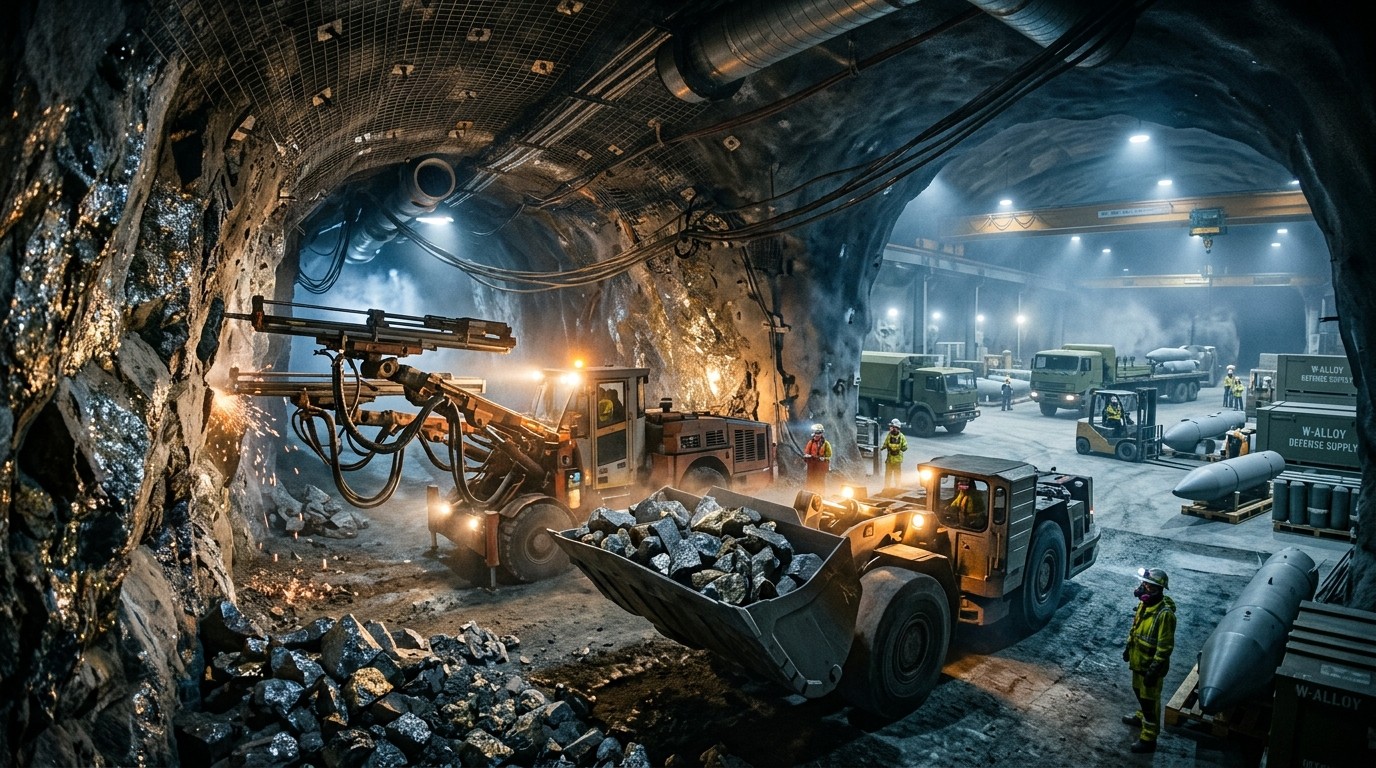
One operation in particular has drawn consistent attention from metals desks. The Sangdong project in South Korea has moved from construction into the early stages of production. Final certification of the processing plant arrived in mid-September, allowing concentrate output to begin. Grinding circuits are already running at full throughput while flotation is still being optimized.
Management has indicated that the first commercial shipments should leave in late October. That schedule is a few weeks later than some earlier forecasts, which has prompted modest adjustments to near-term revenue and earnings expectations. Still, the broader trajectory remains intact. Phase 1 is designed to process roughly 640,000 tons of ore per year, translating into meaningful concentrate volumes once the plant reaches steady state.
What strikes me as underappreciated is the optionality that comes with a working plant. Once the mill is stable, expanding capacity becomes a matter of engineering and capital rather than starting from zero. Phase 2 is already under discussion, with the goal of roughly doubling concentrate output by increasing throughput toward 1.2 million tons of ore annually.
Upstream availability of concentrate remains tight and should stay that way as the new defense restrictions take effect.
That assessment from one of the more closely followed special-situations analysts captures the core thesis. Even after the recent price moderation, the physical market for finished tungsten products in the West continues to operate near capacity under long-term contracts. Additional concentrate has limited places to go, which keeps the supply picture supportive for producers that can deliver.
Beyond Korea: Additional Sources Coming Online
Sangdong is the flagship, yet it is not the only piece of the portfolio. In Rwanda the company plans to acquire, upgrade, and export existing ore, pre-concentrate, and tailings material, with first exports targeted for November. In Spain a multi-year offtake covers the recycling of an existing tailings stockpile at Los Santos. Further out, the Montana project known as Gentung-Browns Lake offers longer-term U.S. domestic optionality, though development there is deliberately paced.
These secondary sources matter because they diversify both geography and product type. Recycled and secondary material can sometimes move faster than primary mine development, and in a market where every compliant ton counts, speed has real value.
Perhaps the most interesting aspect is how these projects fit together. A company that can combine Korean primary production, African secondary feed, European recycling, and a potential North American deposit begins to look less like a single-mine story and more like a platform for Western-aligned tungsten supply.
What Analysts Will Be Listening For on Monday
Investor Day presentations tend to follow a familiar pattern, yet the questions this time feel more pointed. Market participants want clearer guidance on several fronts.
- How sustainable are current tungsten prices, and what long-term incentive price does management believe is required to bring new supply?
- Are contract structures evolving to include more price floors or other protective mechanisms?
- How durable does the current defense demand cycle appear from the customer side?
- What is the realistic timeline for Sangdong to reach continuous 24-hour operation and nameplate capacity?
- How advanced is engineering work for Phase 2, and what capital and underground development milestones remain?
- Where does the molybdenum drilling program stand, and when might updated reserves be published?
- Is there tangible progress on permitting or potential government support for the Montana project?
These are not abstract academic questions. Answers will shape near-term models and longer-term valuation frameworks. A confident update on continuous milling, for example, would reduce the residual operational risk that still hangs over Phase 1. Clarity on Phase 2 capital needs would help investors gauge dilution risk and free-cash-flow timing.
I expect the conversation around pricing to be particularly revealing. Spot prices have eased, yet Western oxide and APT plants remain fully booked. That divergence between concentrate and finished product markets is unusual and worth exploring in detail.
Financial Flexibility and Capital Allocation
Balance-sheet strength often decides which projects actually get built. Current cash levels appear sufficient to fund the remaining Sangdong expansion steps, the planned oxide facility, and still leave room for share repurchases. Net cash after accounting for outstanding obligations remains meaningfully positive.
That flexibility is not trivial. Many junior and mid-tier miners face a constant tension between growth spending and balance-sheet preservation. Having the ability to advance multiple work streams without immediate equity raises changes the risk profile in a noticeable way.
Of course, capital allocation choices will still be scrutinized. Buybacks can support the share price in the short run, yet investors will want to see that growth projects remain the priority while the market window is open. Striking that balance is harder than it looks.
Valuation Context After the Broader Mining Pullback
Mining equities as a group have given back a substantial portion of the gains recorded earlier this year. The sell-off has compressed multiples across the sector, including for companies with clearer near-term catalysts. One closely followed analyst recently lowered a price target to reflect the lower peer multiples while still describing the shares as attractive on a forward EBITDA basis.
At roughly 5.7 times estimated 2027 EBITDA and 4.2 times 2028, the valuation leaves room for operational delivery to drive further re-rating. Those multiples assume successful ramp-up and continued tightness in the tungsten market. Execution risk remains, yet the asymmetric payoff if both conditions hold is hard to ignore.
I’ve found that markets often under-appreciate the difference between a development story and a production story. Once a mine is shipping product, the conversation shifts from “if” to “how much and how fast.” That shift can compress risk premiums more quickly than many models assume.
The Broader Rearmament Backdrop
Defense budgets across multiple Western countries are rising. Order books for missiles, interceptors, and advanced aircraft are expected to expand meaningfully from 2027 through 2030. Each of those platforms carries tungsten in some form, whether in penetrators, counterweights, or high-temperature components.
The demand side of the equation therefore looks structural rather than cyclical. Even if commercial industrial uses remain steady, the defense overlay creates a floor under consumption that did not exist a decade ago. Producers able to meet the new origin requirements sit in a privileged position relative to that demand.
One subtle point worth noting is the limited ability of existing Western processing plants to absorb extra concentrate. Long-term contracts already fill most available capacity. New primary supply therefore has a clearer path to market than it might in a more flexible industrial metal.
Near-Term Catalysts and What Could Go Wrong
Several events sit on the near-term calendar. First shipments from Sangdong, if they occur on the late-October schedule, will provide tangible proof of concept. Third-quarter results in mid-November will give the first real look at early production economics. Any update on Phase 2 engineering or molybdenum drilling could move the longer-term narrative.
Risks remain real. Ramp-up delays are common in new mining operations. Flotation optimization can take longer than planned. Tungsten prices could soften further if Chinese exports increase or if defense budgets face unexpected political pressure. Currency moves and cost inflation can also erode margins.
Still, the combination of an approaching regulatory deadline, limited alternative supply, and a company already in production creates a setup that is difficult to replicate elsewhere in the critical-materials space.
Putting the Pieces Together
The story is ultimately about bottlenecks. When a material is both essential and constrained by origin rules, the few producers that can satisfy those rules gain pricing power and volume visibility that ordinary industrial commodities rarely enjoy. Tungsten is entering that phase.
Monday’s Investor Day will not answer every question. Operational updates will still need to be verified by subsequent quarterly results. Yet the gathering itself signals that institutional interest is deepening at a moment when the physical market remains tight and the policy clock continues to tick.
For investors willing to look past the recent sector-wide pullback, the combination of near-term production growth, multi-project optionality, and structural demand from rearmament programs offers a compelling risk-reward profile. The details that emerge this week will help determine how quickly that profile is recognized more broadly.
In the end, critical materials stories succeed or fail on execution. A processing plant that runs consistently, shipments that leave on schedule, and expansions that stay within capital budgets will matter more than any single presentation. Those are the metrics worth watching after the slides are finished and the analysts return to their desks.
The tungsten market is not waiting for perfect clarity. Demand from defense programs is already visible, and the rules that will reshape acceptable supply sources are fixed on the calendar. Companies that can deliver compliant material in volume stand to benefit as the gap between restricted and unrestricted supply becomes more pronounced. That is the backdrop against which this week’s discussions take place, and it is why the conversation is likely to continue well beyond a single Investor Day.
Looking further ahead, the interplay between primary mine output, secondary recycling streams, and potential domestic projects in North America could create a more resilient Western supply network than exists today. Building that network will take time and capital, yet the policy incentives and customer urgency appear aligned. For a metal that has spent decades in relative obscurity, the next few years may prove unusually consequential.
Investors who have followed the broader critical-materials theme know that timing often decides outcomes. Being early can feel lonely; being late can be expensive. The current window, with production already underway and regulatory changes still months away, sits somewhere in between. How management navigates the remaining operational steps will determine whether that window is used effectively.
One final observation: markets have a habit of rediscovering forgotten metals when geopolitics intervenes. Tungsten’s density and heat resistance have always made it valuable. What has changed is the willingness of major buyers to pay a premium for certainty of origin. That premium is still forming, and the companies positioned to capture it are limited in number. Watching how the next chapter unfolds should prove instructive for anyone interested in the intersection of commodities, defense, and capital markets.