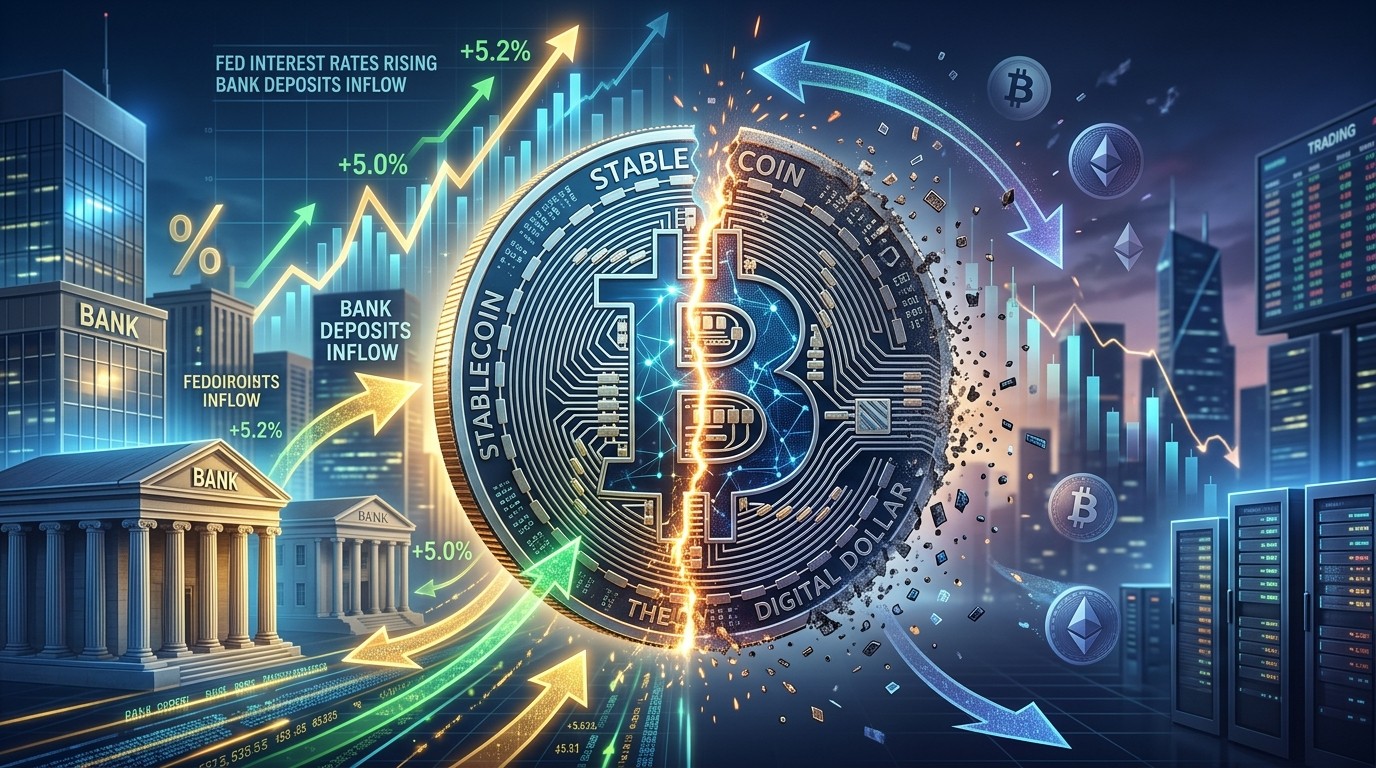

What if a tiny tweak in the interest you earn on a regular bank account could quietly reshape the entire stablecoin market? I found myself asking that exact question after digging into fresh research that landed recently. The numbers are surprisingly clear: when U.S. banks lift their deposit rates by just one basis point, overall stablecoin market capitalization growth tends to slow by roughly three percentage points over the following ten weeks. That may sound modest at first glance, yet it carries real weight in a sector that once seemed almost immune to traditional finance.
Why Bank Deposit Rates Matter More Than Most Crypto Fans Realize
Stablecoins were built to feel like digital cash. They promise price stability, fast transfers, and a bridge between crypto and everyday money. For years many holders treated them as a convenient parking spot that simply did not need to compete with bank accounts. Recent analysis flips that assumption on its head. It turns out people and institutions do notice when banks start paying a bit more on ordinary deposits. The opportunity cost becomes real, and some capital quietly shifts.
The working paper examined weekly U.S. data spanning January 2019 through June 2025. Researchers tracked changes in average bank deposit rates alongside movements in the market capitalization of the major reserve-backed stablecoins. After controlling for the federal funds rate, Treasury yields, dollar strength, Bitcoin price swings, and equity market volatility, a clear pattern emerged. Higher deposit rates consistently lined up with slower subsequent growth in stablecoin totals.
A one-basis-point increase—literally one-hundredth of a percentage point—was associated with about 2.8 percentage points less cumulative growth over the next ten weeks. In the sample period, the average ten-week expansion of the stablecoin market sat near 15 percent. Applying the baseline estimate brings that figure down closer to 12 percent. Growth continues, just at a noticeably slower pace. I think that distinction is important. We are talking about a slowdown, not an outright contraction.
The Instrumental-Variable Surprise
Baseline regressions already told a compelling story. The researchers went further with an instrumental-variable approach designed to isolate the causal channel more cleanly. Banks do not adjust customer deposit rates in lockstep with every move in the federal funds rate. The sensitivity rises once policy rates climb above roughly three percent. By exploiting that nonlinear response, the team obtained a larger estimated effect: roughly 9.1 percentage points less cumulative stablecoin growth over ten weeks for the same one-basis-point deposit rate rise.
That figure is more than three times the baseline result. It does not mean every tiny rate increase will always produce a nine-point hit. It does suggest that during periods of higher interest rates the substitution effect grows stronger. In my view this is one of the more interesting methodological choices in the paper. It acknowledges that the relationship is not constant across all monetary environments.
The larger estimate appears when focusing on rate changes that occur under elevated interest-rate conditions, highlighting how sensitive stablecoin demand becomes once banks start competing more aggressively for deposits.
USDC Feels the Pressure More Than USDT
Not every stablecoin reacts the same way. The research uncovered a meaningful difference between the two largest dollar-backed tokens. Circle’s USDC showed a markedly stronger response. A one-basis-point deposit rate increase corresponded to a 4.8-percentage-point reduction in its ten-week market-cap growth. Tether’s USDT registered only a 1.9-percentage-point slowdown under the same conditions. That makes the USDC reaction roughly two and a half times larger.
Why the gap? The authors point to user bases. USDC maintains tighter ties to U.S. institutional investors and domestic financial infrastructure. USDT serves a broader international audience whose banking options and dollar access often look quite different. When American banks raise deposit rates, the opportunity cost hits U.S.-oriented holders harder. International users may simply have fewer attractive local alternatives, so the substitution pressure stays weaker.
I find this distinction especially useful for anyone tracking the competitive landscape. It suggests that regulatory developments or banking product innovations inside the United States could influence the relative market shares of the major stablecoins more than many observers currently assume.
Certificates of Deposit and DeFi Lending Tell a Similar Story
The analysis did not stop at ordinary savings and checking rates. Researchers also examined certificates of deposit. The negative relationship between higher CD yields and subsequent stablecoin growth remained intact. Even when stablecoins were deployed into decentralized lending protocols—where they can earn yield—the same pattern appeared after controlling for the returns available on those platforms.
That second finding surprised me a little. Many people assume that once capital moves into DeFi the connection to traditional bank rates weakens. The data suggest otherwise. Bank deposit pricing still appears to influence the broader demand for stablecoins across multiple use cases. The substitution channel is wider than a simple retail savings decision.
- Higher ordinary deposit rates slow overall stablecoin market-cap growth
- The effect is stronger for USDC than for USDT
- Certificates of deposit produce parallel results
- Stablecoins supplied to DeFi lending platforms show similar sensitivity
What the Research Does Not Claim
Important caveats appear throughout the paper. The authors explicitly state that their findings do not prove stablecoins have reduced the total stock of bank deposits or constrained bank lending across the U.S. system. The work focuses on relative growth rates and substitution at the margin. It does not quantify net deposit flight or systemic impact.
They also note the relatively short history of the stablecoin sector. The sample covers one major cycle of elevated interest rates. Drawing strong conclusions about long-run banking behavior remains difficult. Additional robustness checks involving trading volumes and major crypto disruptions—such as the TerraUSD collapse, the FTX failure, and the wind-down of certain exchange-issued tokens—left the core negative relationship intact. A placebo test on non-stablecoin crypto assets produced no comparable pattern, which helps rule out a general crypto-market explanation.
These limitations matter. In policy conversations it is easy for findings to get stretched beyond what the data actually support. The research is careful on this point, and readers should be equally careful.
How This Fits Into the Broader Banking and Crypto Debate
The timing of the paper is interesting. Banks and crypto firms continue to negotiate the rules that will govern regulated stablecoins. Industry groups have expressed concern that certain reward structures could pull deposits out of the traditional system. The research approaches the same competitive dynamic from the opposite direction: higher rates paid by banks can slow the expansion of stablecoin balances.
Some banks have begun experimenting with dual-purpose tokens that function as deposits inside the banking network and as transferable digital assets outside it. Those projects aim to keep the deposit relationship while offering blockchain rails. Meanwhile, independent decentralized protocols continue to offer yield opportunities that sit outside the insured deposit system and carry different risk profiles. The paper does not evaluate any specific legislation or product, yet its findings sit squarely inside the conversation those products are trying to address.
In my experience watching financial innovation, the most durable arrangements usually emerge when both sides of the market understand the substitution elasticities. Knowing that deposit rates influence stablecoin demand gives both bankers and crypto product designers clearer information about the competitive landscape.
Putting the Numbers in Perspective
A basis point is a small number. One hundred of them make a full percentage point. Yet the estimated response of stablecoin growth is large relative to that tiny change. That amplification is what makes the result noteworthy. It implies that holders are attentive to relative returns even when the absolute difference remains modest.
During the sample period the average ten-week stablecoin growth rate hovered near 15 percent. A three-percentage-point reduction still leaves healthy expansion. The instrumental-variable estimate of nine points would slow growth more sharply, though that figure applies under specific rate environments. Either way, the direction of the effect is consistent.
| Metric | Baseline Estimate | Instrumental-Variable Estimate |
| One-basis-point deposit rate rise | ≈2.8 pp slower growth | ≈9.1 pp slower growth |
| USDC response | ≈4.8 pp slower | — |
| USDT response | ≈1.9 pp slower | — |
| Average ten-week market growth | ≈15 % | ≈15 % |
The table above summarizes the core quantitative findings. It is worth remembering that these are statistical associations estimated under specific modeling assumptions. They are not mechanical forecasts that will hold in every future rate cycle.
What Holders and Market Watchers Should Watch Next
Several practical implications follow. First, periods of rising bank deposit rates may coincide with slower stablecoin expansion, particularly for tokens with stronger U.S. institutional ties. Second, the relative performance of different stablecoins could shift as domestic versus international demand responds differently. Third, any future product that combines deposit-like yields with blockchain transferability will operate inside this competitive dynamic rather than outside it.
I have long believed that the most interesting financial innovations are those that force traditional and digital systems to compete on price and convenience. The research supplies concrete evidence that such competition is already occurring at the margin. Stablecoins are not floating free of interest-rate decisions. Bank pricing decisions are not irrelevant to digital dollar demand.
Looking ahead, the next monetary policy cycle will provide a natural test of these findings. If deposit rates move lower again, the model would predict a relative acceleration in stablecoin growth, all else equal. Watching whether that pattern reappears will help separate temporary effects from more durable structural relationships.
A Closer Look at the Research Design
The authors used weekly observations rather than monthly or quarterly data. That higher frequency helps capture shorter-term responses. They included a broad set of controls precisely because stablecoin demand can be influenced by risk appetite, dollar liquidity conditions, and broader crypto market sentiment. Isolating the deposit-rate channel required careful econometric work.
The instrumental-variable strategy rests on the observation that banks pass through policy rate changes more aggressively once rates are already elevated. That institutional detail supplies useful variation. It is not a perfect instrument—no real-world instrument ever is—but it strengthens the case that the relationship is more than simple correlation.
Robustness checks around major crypto stress events were particularly useful. The TerraUSD and FTX episodes created large temporary shifts in stablecoin usage and confidence. Finding that the deposit-rate relationship survived those shocks increases confidence that the core result is not an artifact of any single market crisis.
Broader Implications for Digital Money Design
One under-discussed aspect is how this research might influence future stablecoin design. If yield competition from banks can slow growth, issuers and platforms may feel pressure to explore compliant ways of sharing returns with holders. At the same time, regulators remain focused on ensuring that any such arrangements do not undermine deposit insurance or create new forms of run risk. The tension is real.
Banks, for their part, face a choice. They can continue to compete primarily on traditional deposit rates, or they can explore tokenized deposit products that combine the safety of the banking system with the transferability of blockchain assets. Early experiments along those lines already exist. The research suggests that the competitive pressure is not theoretical.
Perhaps the most interesting long-term question is whether the substitution elasticity will remain stable as the user base matures. Early stablecoin holders may have been more rate-sensitive. Later cohorts could treat the tokens more like pure payment instruments and less like short-term stores of value. Only additional data will tell.
Final Thoughts on Competition Between Two Forms of Money
Stablecoins and bank deposits both offer relatively stable nominal value and support payments. The key difference has always been the interest rate. Conventional deposits can pay a yield; the major payment stablecoins generally do not pass interest directly to holders. That difference creates an opportunity for substitution whenever the yield gap widens or narrows.
The new research quantifies that substitution more carefully than previous work. A small rise in deposit rates is associated with a measurable slowdown in stablecoin market growth. The effect is stronger for the stablecoin most closely tied to U.S. users. Parallel patterns appear in certificates of deposit and in DeFi lending contexts. The findings do not claim that stablecoins have drained the banking system, yet they demonstrate that the two forms of money compete at the margin.
For anyone following the evolution of digital dollars, that competitive reality is worth keeping front of mind. Interest-rate decisions made inside traditional banks can and do influence the growth trajectory of the largest stablecoins. The reverse is also true in the policy debate: the existence of attractive digital alternatives can influence how aggressively banks price deposits. Both sides of the market are watching each other more closely than they sometimes admit.
I expect the next few years of data will refine these estimates further. For now the message is straightforward. When banks raise what they pay on deposits, the stablecoin market tends to grow a little more slowly. Three percentage points over ten weeks may not sound dramatic, yet in a market that has often expanded at double-digit rates, every point matters. The digital and traditional forms of money are already competing for the same capital. Understanding that competition is essential for anyone trying to anticipate the next phase of financial innovation.