

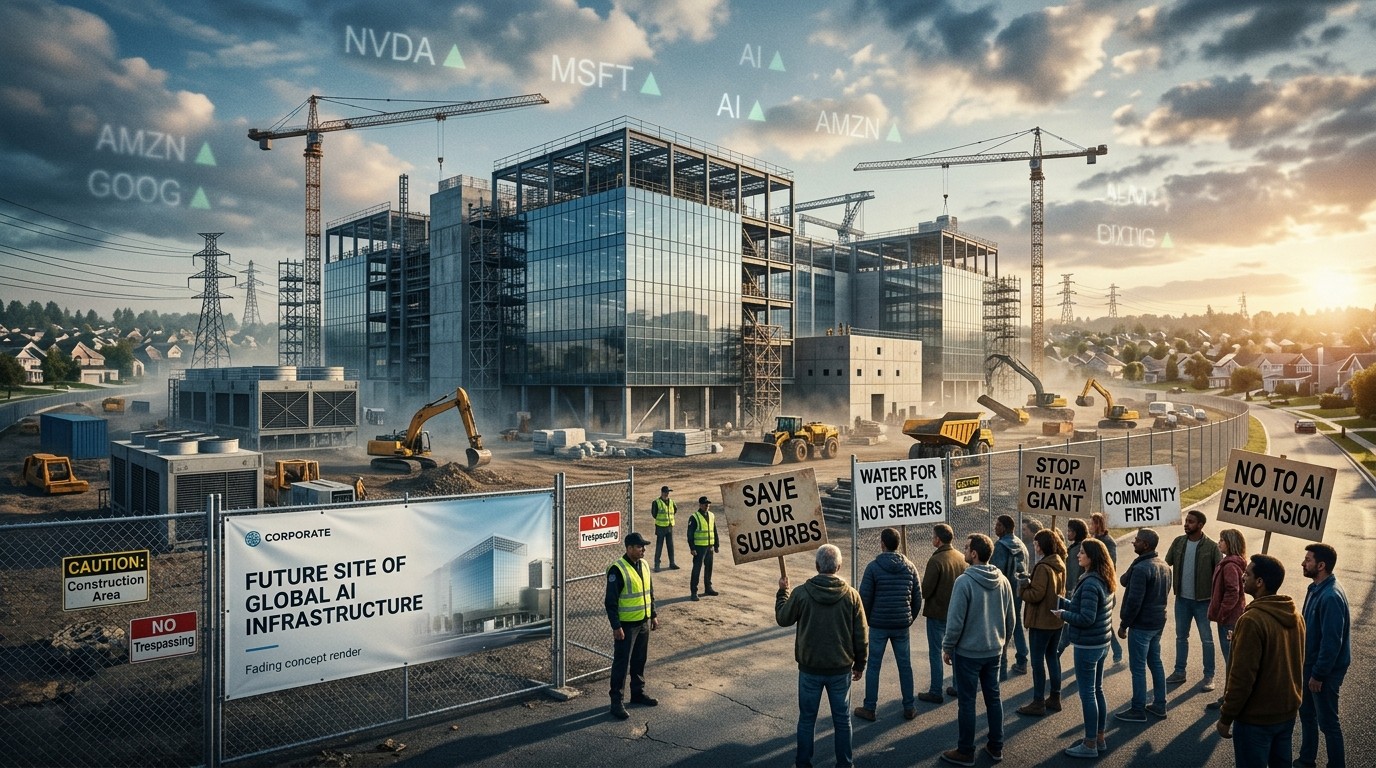

Have you noticed how quickly public sentiment can turn against something that once felt inevitable? One moment the conversation around artificial intelligence is all about breakthroughs and productivity gains. The next, ordinary people are showing up at town halls and ballot boxes to push back hard against the physical infrastructure that makes those systems possible. That shift is exactly the backdrop against which a major pure-play AI company is now preparing to list its shares.
Why the Timing of This IPO Feels Especially Exposed
The company in question has spent years positioning itself as more careful than its peers. It emphasizes safety research, constitutional approaches to model behavior, and an enterprise customer base rather than consumer chat interfaces. That strategy kept it somewhat out of the daily headlines. Going public changes the equation overnight. Quarterly reports, analyst questions, and constant media coverage will force every decision into the open at a moment when trust in the broader industry is already thin.
Valuation expectations have already come down. Early whispers of a two-trillion-dollar target have given way to a more modest range between one and one-and-a-half trillion. Even that figure still represents an enormous number for a company whose primary product is software that runs on someone else’s silicon and power. The reduction itself signals that underwriters are reading the room.
Market Mood and the Broader Tech Selloff
Equity markets have not been kind to AI-linked names lately. The Nasdaq just recorded its sharpest single-day drop in more than a year and a half, and the month of October ranked as its weakest since early 2025. Companies that supply the chips, the power, and the specialized cloud capacity have absorbed the heaviest losses. When the firms that sit one layer below the model developers are struggling, it becomes harder to argue that demand is infinite and frictionless.
Investors are suddenly asking harder questions about return on capital. Building and operating the next generation of training clusters requires commitments measured in hundreds of billions of dollars. One amended filing disclosed purchase and lease obligations totaling roughly 895 billion dollars, almost entirely for compute and infrastructure. That number is not a rounding error. It is a multi-year claim on future cash flows that must be defended to public shareholders who can vote with their feet every trading day.
What the Midterm Results Actually Revealed
Voters delivered an unusually consistent message on data-center projects. In forty of forty-one local ballot measures, communities rejected or restricted new facilities. Exit polling indicated that more than half of voters considered the issue either crucial or a major factor in their congressional choices. Candidates who promised tighter oversight of AI development performed well in several swing states that will now have Democratic governors.
People do not want a large facility nearby if its main purpose is to run models that ultimately enrich a handful of technology companies.
– Behavioral researcher
The pattern is striking because it cuts across regions that do not normally vote the same way. Local opposition has coalesced around three recurring concerns: electricity prices, water use, and the sense that the economic benefits stay elsewhere. A data center can employ a few dozen technicians while consuming the power of a small city. Residents who already feel squeezed by inflation notice when utility bills rise and when new industrial demand crowds out other development.
In my experience watching similar infrastructure fights, once a project becomes a symbol it is very hard to depoliticize. The physical building turns abstract worries about job displacement or algorithmic bias into something neighbors can point at. That is the environment this IPO is entering.
How the Company Has Tried to Stay Distinct
Unlike some rivals, the firm has deliberately stayed focused on business customers. Its flagship family of models is marketed primarily as a tool for developers, researchers, and enterprises that need reliable, steerable systems. That choice reduced consumer-facing controversies and kept the brand out of the daily culture-war arguments that surround chatbots. Leadership has also been relatively open about the possibility of serious downside risks, which earned goodwill among certain policy audiences.
Public listing removes some of that insulation. The prospectus itself acknowledges that organized opposition to data-center construction has grown more sophisticated and that the company’s higher profile could attract extra scrutiny to any project associated with it. Those sentences are standard risk-factor language, yet they read differently when local governments are already rejecting facilities at a high rate.
- Enterprise concentration limits consumer backlash but concentrates revenue risk.
- Safety narrative helps with regulators yet does not automatically translate into local permits.
- Heavy infrastructure commitments create multi-year fixed costs that public markets will scrutinize quarterly.
Rebuilding Trust Is Harder Once It Is Lost
A recent university survey found that 71 percent of respondents do not trust large technology companies at all to act in society’s interest when it comes to data-center development. That is not a soft “somewhat skeptical” number. It is a clear rejection of the premise that industry self-regulation or voluntary commitments will suffice. Once that baseline distrust is in place, every new announcement about capacity expansion can be read as further evidence that companies are moving ahead regardless of local sentiment.
The chief executive addressed the mood directly in a public post last summer, describing a broader crisis of trust in which people assume that companies, government, and the technology sector are constantly finding new ways to extract value at their expense. Acknowledging the problem is necessary, yet it does not automatically restore confidence. Quarterly earnings calls will now force the company to explain why its own spending plans still make sense in that climate.
Practical Consequences for Investors and Communities
For public-market investors the immediate questions are straightforward. How quickly can the company convert its massive compute commitments into durable revenue? What happens to margins if power prices stay elevated or if permitting delays stretch the timeline on new clusters? And how much of the current enterprise demand is locked in versus discretionary spending that could slow if economic conditions tighten?
Communities face a different set of trade-offs. Some regions have welcomed data centers for the tax revenue and construction jobs they bring. Others have concluded that the long-term costs outweigh those benefits once the construction phase ends. The near-unanimous rejection rate on recent ballots suggests the second view is currently winning in many places. That political reality will shape where and how quickly new capacity can be added, regardless of what any single company prefers.
| Concern | Community Perspective | Company Perspective |
| Electricity demand | Higher bills, grid strain | Necessary for competitive models |
| Water use | Local resource pressure | Cooling requirements for dense clusters |
| Employment | Few permanent jobs | High-skill technical roles plus indirect effects |
| Tax revenue | Helpful but not transformative | Supports infrastructure investment case |
Perhaps the most interesting tension is that the same models the company is selling to enterprises are also the technology that makes many of the feared job displacements possible. An enterprise customer might use the system to automate customer support or code generation. Those efficiency gains are real for the buyer. They are less comforting to workers in the communities hosting the servers. Bridging that gap with credible local benefits has proven difficult so far.
What a Public Listing Changes in Practice
Once shares trade, the company will file regular updates on revenue, margins, customer concentration, and capital expenditure. Analysts will model the path from current enterprise contracts to the infrastructure spend already committed. Any slowdown in new bookings or any increase in power costs will be visible immediately. That transparency is healthy in the long run, yet it also removes the ability to manage the narrative solely through selective announcements.
Some market observers argue that the spotlight is not inherently negative. Greater disclosure can attract users who previously preferred to wait for more information. It can also force clearer prioritization of the projects that actually generate returns. The counter-argument is that the current political environment is not a normal one for technology infrastructure. When local governments are rejecting facilities at a rate of forty out of forty-one, the usual playbook of promising economic development may not be sufficient.
Being public does not automatically mean a company deserves more criticism than a comparable private firm, but it does mean every operational choice is examined in real time.
I have watched other infrastructure-heavy technology businesses navigate similar transitions. The ones that succeeded usually found ways to make the local economics more tangible—whether through long-term power-purchase agreements that stabilize rates, water-recycling systems that reduce net consumption, or workforce programs that extend beyond the construction phase. Those measures do not eliminate opposition, but they can change the balance of local opinion enough to keep projects moving.
Looking Ahead: Scenarios That Matter
Three broad paths seem plausible over the next eighteen months. In the first, enterprise demand continues to grow fast enough to absorb the committed capacity and political friction remains localized rather than systemic. In that case the valuation range now being discussed could look conservative. In the second path, permitting delays and higher operating costs compress margins while customer growth slows; the stock would then trade more like a capital-intensive utility than a high-margin software company. The third path is a broader regulatory response at the federal level that imposes new constraints on training compute or on the energy intensity of inference. That outcome is harder to model but would affect every major lab.
None of these paths is certain. What is clear is that the company no longer controls the tempo entirely. Public markets, local governments, and utility regulators will all have a voice. The safety-focused positioning that served the firm well in private may still help with federal policymakers, yet it does not automatically solve a zoning fight in a county that has already voted against new facilities.
There is also the human element that rarely shows up in filings. Engineers and researchers inside the company have spent years arguing that careful development is both ethically necessary and commercially smart. Watching public opinion harden against the physical plants that run their work can be demoralizing. Retaining talent while the external narrative turns negative is an under-appreciated management challenge during an IPO window.
Final Thoughts on the Road Ahead
The decision to list now is understandable from a liquidity and governance standpoint. Early investors and employees have waited a long time. At the same time, the external environment has shifted faster than many expected. Midterm results showed that data-center opposition is no longer a fringe local issue; it is salient enough to influence congressional voting in multiple states. Combined with a softer tape for AI-adjacent equities, that creates a narrower path than the one that existed six or twelve months ago.
Whether the company can widen that path again will depend on execution that is both technically strong and politically attuned. Transparent communication about energy and water use, credible local benefit agreements, and continued evidence that enterprise customers are receiving real value will all matter. So will the simple fact that public shareholders can express dissatisfaction more quickly than private ones. In that sense the IPO is both an opportunity for greater legitimacy and a test of whether the current model of rapid infrastructure build-out can survive sustained public skepticism.
I keep coming back to a simple observation from the survey data: once trust is gone, it is extremely difficult to regain. The next several quarters will show whether this particular company can demonstrate, in concrete and local terms, that its growth is compatible with the concerns voters have already voiced. That demonstration, more than any single valuation number, will determine how the listing is remembered.
The story is still being written. Markets will price the known risks quickly. Communities will continue to vote on the facilities they can see. And the company will have to navigate both audiences at once, with far less ability to choose the timing of the conversation. That is the real test of going public in this moment.



