
Have you ever watched a company look this close to a finish line, only to trip on something that sounds small until the market prices it like a big problem? That is the feeling around Boeing right now. The largest stretch version of the 737 Max family was supposed to be moving from paperwork into deliveries. Instead, a software concern tied to an automated navigation function has put certification on pause, and the share price took the news badly. I have covered enough industrial names to know this pattern. Investors do not wait for a final safety ruling. They sell first and ask later.
The Delay That Turned A Late Rally Into Another Slump
The core issue is not mysterious, even if the engineering language can get dense. Airlines were told about a previously known glitch that could interrupt an automated navigation function during an aborted landing. Some carriers asked for deliveries with an older software load that avoids the new behavior. That request tells you a lot. Operators want airplanes. They also want predictable cockpit behavior. When those two needs collide, regulators slow down.
The company now has to produce a software patch. That sounds tidy. In aviation, tidy is rarely the same as fast. Certification of the 737 Max 10 is being held until officials decide whether the flagged concern is a safety-of-flight issue. The smaller Max 7 already received approval with the latest software. That version fixed one known vertical navigation problem and then, awkwardly, introduced a smaller bug. Progress with a catch. Markets hate a catch.
Shares fell more than six percent in late trading after the delay became public, the sharpest one-day drop in months. The stock is still down sharply on the year and has spent years moving sideways after the two Max accidents in 2018 and 2019. That history sits in every conversation, even when nobody names it out loud. You can feel it in the way traders treat every new software headline as if it might reopen an old wound.
The pilots remain in control of the airplane. They train for these scenarios. The issue that we are looking at right now is the workload component under these more obscure situations.
That is the official tone. Control stays with the crew. Training already covers go-around cases. The open question is workload in uncommon conditions. I find that distinction important. It is not a claim that the jet is unflyable. It is a claim that the agency wants more comfort before it stamps the biggest member of the family. Comfort is not a ticker symbol, but it moves tickers all the same.
What The Software Issue Actually Means For Flight Decks
Let me put this in plain language. Modern airliners use layered automation. Vertical navigation helps manage path, speed, and energy during approach. If that function drops out during a go-around, the crew has to pick up the task by hand. Pilots train for that. They do it in simulators until the motions feel automatic. The regulatory worry is not that a captain suddenly becomes helpless. The worry is extra workload at a busy moment, especially if the dropout is unexpected.
Some airlines prefer an older software version because they already know its quirks. That is not romance for yesterday’s code. It is operational conservatism. Fleets live on consistency. A new load that solves one problem and creates another forces training notes, dispatch discussions, and more simulator time. None of that is free. None of it is glamorous. All of it shows up in delivery schedules.
In my experience, the public hears “software glitch” and imagines a movie scene. Reality is dryer. A function can degrade, a mode can drop, a crew can fly the airplane, and a regulator can still say the paperwork is not finished. Those four facts can be true at once. Markets tend to flatten them into one sentence: delayed again.
- The glitch involves an automated navigation function during aborted landings.
- Some airlines requested older software to avoid the new behavior.
- A patch is required before the Max 10 can clear the last hurdle.
- Officials have not yet labeled the issue a safety-of-flight problem.
- The smaller Max 7 was certified with the latest software despite the new bug.
Why The Max 10 Matters More Than Another Variant Name
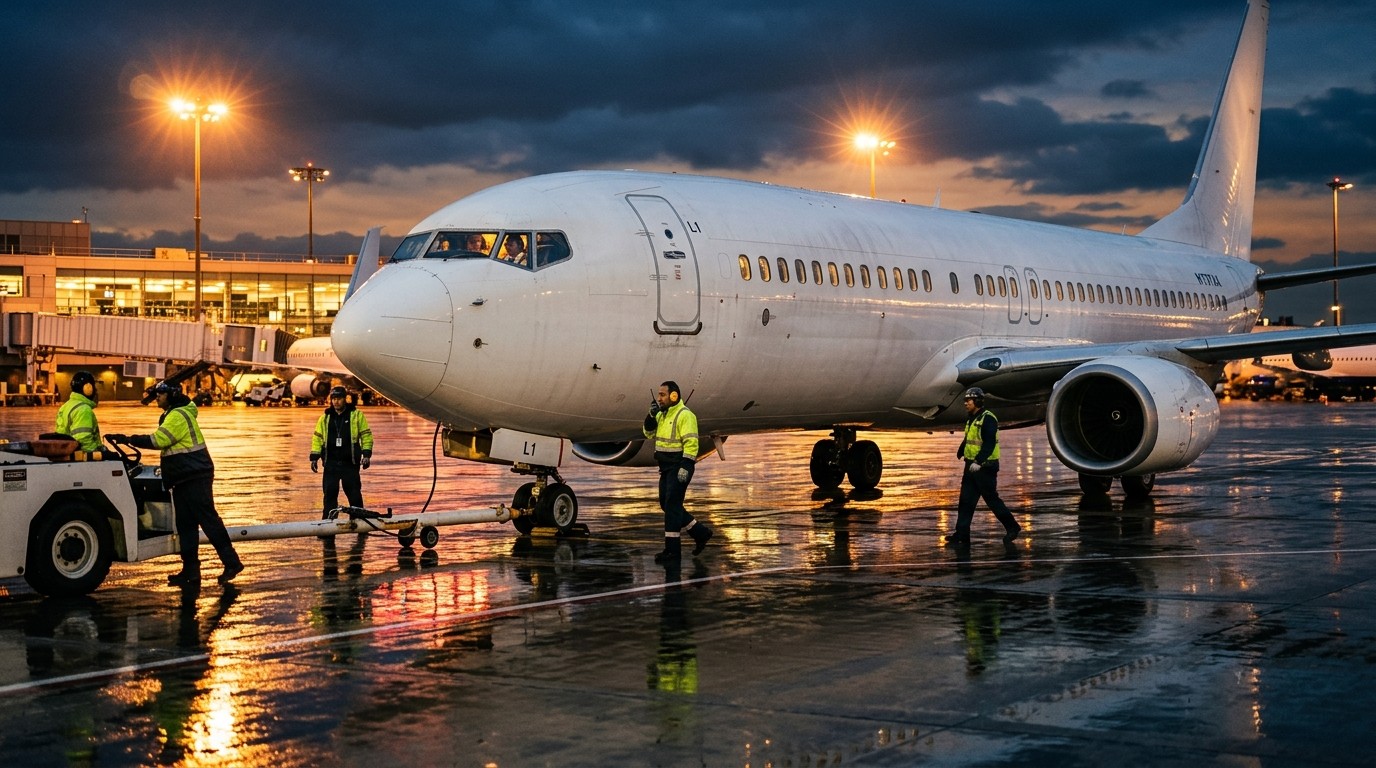
This is not a niche airplane. Orders for the Max 10 sit above 1,500. That is a serious slice of the narrowbody backlog. The jet is meant to carry more people and lower the cost per seat. Capacity runs up to about 230 passengers, versus roughly 220 on the Max 9 and 210 on the highest-capacity Max 8. Those numbers look small on a slide. On a route map they are money.
Airlines buy stretch jets when they want frequency without jumping to a widebody. Airports with slot limits love that math. So do leisure carriers that fill every row. If the Max 10 slips, substitution is messy. Some customers can take Max 9s. Some cannot. Cabin layouts, performance, and airport compatibility are not interchangeable Lego bricks. A delay in one variant ripples through delivery slots for others.
Perhaps the most interesting aspect is timing. Management had told investors the jet could be approved very soon after the Max 7 clearance earlier in the summer. “Very soon” is a dangerous phrase in this industry. It raises expectations. When the calendar slips, the stock does not ask for context. It marks the gap.
| Variant | Typical High Capacity | Investor Angle |
| Max 8 | About 210 seats | Workhorse of the family |
| Max 9 | About 220 seats | Bridge jet for growing routes |
| Max 10 | Up to about 230 seats | Highest seat-mile leverage in the line |
The Stock Market Did Not Wait For A Final Ruling
Equity markets are impatient by design. A six percent afternoon drop is not a philosophical debate about workload. It is capital leaving a name that already carries credibility discount. The shares were already down about 14 percent on the year when the delay hit. That is not a company in a quiet consolidation. That is a company still paying for years of operational noise.
Wall Street remains mostly constructive on paper. A large majority of tracked analysts sit at buy, a handful at hold, and none at sell in the latest tally I saw discussed around the move. The average twelve-month target still sits well above the post-drop price. I have found that gap can last a long time. Targets describe a destination. Trading describes the road. Boeing has been on a rough road.
Why the mismatch? Because the long-term case is easy to write. Global travel demand is resilient. Narrowbody replacement cycles are long. The Max family is still the company’s volume engine. The short-term case is harder. Certification timing, factory quality, supplier health, and cash conversion all have to line up. One more software hold does not wreck the long-term story. It does remind holders that the last mile keeps getting longer.
A Chief Executive Still Cleaning Up Old Fires
The current chief has been in the seat for two years. That is long enough to own the narrative and short enough that every new problem still looks like unfinished cleanup. Weekend chatter about yet another fire to put out is not fair in a vacuum. It is also not surprising. Boeing’s public story has been a sequence of operational recoveries. Investors grade the sequence, not the press release.
Getting the Max 10 into service would have been a visible win. It would have said the family is complete, the regulator relationship is functional, and the factory can convert backlog into cash. Instead, the company has to explain a patch, a hold, and a stock drop in the same news cycle. That is a hard week even if the engineering fix is straightforward.
I do not buy the idea that one software item defines the entire turnaround. I also do not buy the idea that markets will ignore it. Leadership in this name is judged on cadence. Cadence means fewer surprises. This was a surprise at the worst possible moment: after the company had already pointed to an imminent approval.
How Regulators Frame Workload Versus Hazard
There is a useful distinction here for anyone who does not live in certification manuals. A hazard is something that can take the airplane out of a safe state. A workload issue is something that makes the crew busier while they keep the airplane in a safe state. Officials said they have not concluded which bucket this belongs in. That sentence is doing a lot of work.
If the final view is workload only, a software change plus training notes may close the file. If the view leans closer to safety of flight, the timeline stretches. Either path still requires evidence. Simulator data. Crew reports. Failure-mode discussion. None of that happens in a day, even when everyone wants it to.
The Max 7 approval with the same software family complicates the optics. Why clear one jet and pause the other? Size, mission, and the way the airplane is used in service can change the assessment. A longer fuselage and a different performance envelope are not trivia. Regulators can accept a condition on one model and want more proof on another. Frustrating? Yes. Inconsistent on the surface? Also yes. Unusual in this industry? Not really.
We have not concluded whether this is a safety of flight issue or not. But we will be delaying the 10 until we are satisfied we do not have an issue here.
Airlines Are Not Abstract Customers In This Story
Carriers live with the consequences first. A delayed Max 10 is a delayed seat. That can mean keeping older jets in service, leasing stopgaps, or reshuffling routes. Fuel burn, maintenance reserves, and cabin product all shift when the new airplane does not arrive on the original month. Finance teams notice. Network planners notice. Passengers usually notice last, which is why the market reaction can look disconnected from the boarding gate.
Requests for older software are a tell. They say some operators would rather take a known configuration than wait for a polished one. That can create a split fleet problem later. Mixed software loads mean mixed procedures. Mixed procedures mean more training complexity. Nobody loves that. Everybody accepts it when the alternative is empty delivery slots.
I keep coming back to a simple point. Demand for the airplane is not the weak link. The order book is large because the mission is real. The weak link is the conversion of design intent into approved, repeatable hardware and software. That conversion has been the company’s multiyear test.
What Investors Should Separate From The Noise
If you hold the stock, or you are thinking about it, mix less drama into the analysis than the headline invites. Start with cash and cadence. Deliveries pay the bills. Certification unlocks deliveries of this variant. A patch that takes weeks is a different animal from a redesign that takes quarters. We do not know the duration yet. That uncertainty is exactly why the share price moved first.
- Watch whether officials describe the issue as workload or as safety of flight.
- Watch whether airlines keep taking other Max models while the 10 waits.
- Watch factory output on already certified variants, because that is current cash.
- Watch guidance language on the next earnings call for any change in timing tone.
- Watch whether the software fix is described as a narrow patch or a broader rewrite.
Those five items are more useful than arguing about a single session’s percentage drop. A six percent move can reverse. A slipped certification year does not reverse as easily. The job is to figure out which one this is.
The Long Shadow Of Earlier Max Crises
It would be dishonest to write about this jet family as if 2018 and 2019 never happened. Those accidents changed how every later software story is received. They also changed the regulatory posture. Extra scrutiny is not a conspiracy. It is the residue of public memory and institutional caution. That residue makes routine bugs feel existential in the market, even when the technical description is narrower.
I think that shadow explains part of the analyst-versus-tape split. Research notes can model replacement demand and margin recovery. Traders remember grounded fleets, congressional hearings, and years of lost trust. Both views can live in the same building. They just use different clocks.
Does that mean every software headline should be treated like a rerun of the worst years? No. That would be lazy. Does it mean management has to over-communicate and under-promise? Yes. That is the price of the brand as it exists today, not as it existed two decades ago.
Production, Cash, And The Cost Of Waiting
A parked approval does not automatically freeze the whole factory. Other Max models can still move if quality gates are met. The financial sting is more subtle. Inventory sits longer. Milestone payments slip. Mix becomes less rich if the highest-capacity jet is the one stuck in line. Over time, that mix issue matters to margin.
There is also a supplier angle. Structures, interiors, and systems vendors plan around a rate. When a variant pauses, some work packages pause with it. Restarting is not a light switch. People, tooling, and travel need to line up again. This is why “just a software thing” can still become an industrial thing.
I have found that investors sometimes treat aerospace delays as if they were app updates. They are not. An app update can ship on a Thursday night. An airplane change ships after labs, simulators, paperwork, and sign-off. The calendar is the product as much as the code is.
Delay math in plain terms:
  Approval hold = later first delivery
  Later first delivery = slower backlog conversion
  Slower conversion = more questions about cash timing
Competitive Context Without The Cheerleading
The narrowbody market is not waiting politely. Rival families keep taking orders. Customers dual-source when they can. If Boeing cannot put the Max 10 on the ramp, some growth flying still happens on other metal. That does not mean the program is finished. It means time has a competitor, and the competitor does not need a press conference.
Still, airlines do not rip up a 1,500-plus order position because one certification month slipped. Switching costs are huge. Training, spare pools, and commonality lock people in. The real risk is not mass cancellation tomorrow. The real risk is a slower ramp and a weaker mix while the file stays open.
If you want a blunt read: the franchise remains valuable, and the execution premium is gone until the company earns it back in dull, repetitive months of on-time output. Dull is underrated. Dull would be excellent here.
How A Patch Could Close The File
A credible path exists. Isolate the dropout. Restore predictable behavior in the go-around case. Show that crew workload stays inside accepted limits. Confirm that the fix does not reintroduce the earlier vertical navigation problem. Document it so a regulator can defend the stamp. That sequence is boring on purpose.
The danger is scope creep. One fix that touches adjacent modes can create new test points. New test points create new calendars. This is why language from the company in the coming weeks will matter. Narrow and specific is what holders want to hear. Broad and exploratory is what they do not.
Will that patch arrive before the next earnings print? I would not bet the rent. Could it? Maybe. Aviation schedules have a habit of looking obvious in hindsight and foggy in the moment. That fog is the discount you saw in the tape.
A Practical Framework For Reading The Next Headlines
Future stories will come in fragments. A comment from an official. A remark on a call. A delivery number that looks light. Resist the urge to treat each fragment as a new thesis. Use a simple filter instead.
- Is the language moving toward closure or toward more study?
- Are other Max deliveries still tracking the recovery plan?
- Is the order book stable, or are customers shifting slots?
- Is the stock reacting to facts or to the memory of older crises?
That last question is the trap. Memory is not worthless. Memory also is not a cash-flow model. Good analysis holds both without letting one eat the other.
My Read After The Dust Settled On The Session
I see a company that remains central to global fleets and still has to earn back the right to be treated as ordinary. Ordinary would mean a software item gets fixed without a six percent drawdown. We are not there yet. The Max 10 is still a commercially important airplane. The delay is still a commercially important stumble. Both sentences can stand.
If the issue stays in the workload column and the patch is tight, this episode becomes a footnote with a nasty chart. If the review expands, the footnote becomes another chapter in a book investors are tired of reading. That is the fork. It is not poetic. It is the job.
Time to get to work is the right closing note for management. Not because a columnist said so. Because the backlog is real, the jet is wanted, and the market has already sent the invoice for another late surprise. The next useful update will not be a slogan. It will be a date, a software description, and a regulator willing to say the file can move.
Until then, treat the drop as information, not as a morality play. The information is simple. Certification risk is still priced into this name. Anyone buying the dip is underwriting that risk with open eyes. Anyone selling it is saying the last mile remains too expensive. I respect both sides more than I respect certainty on a day like this.