

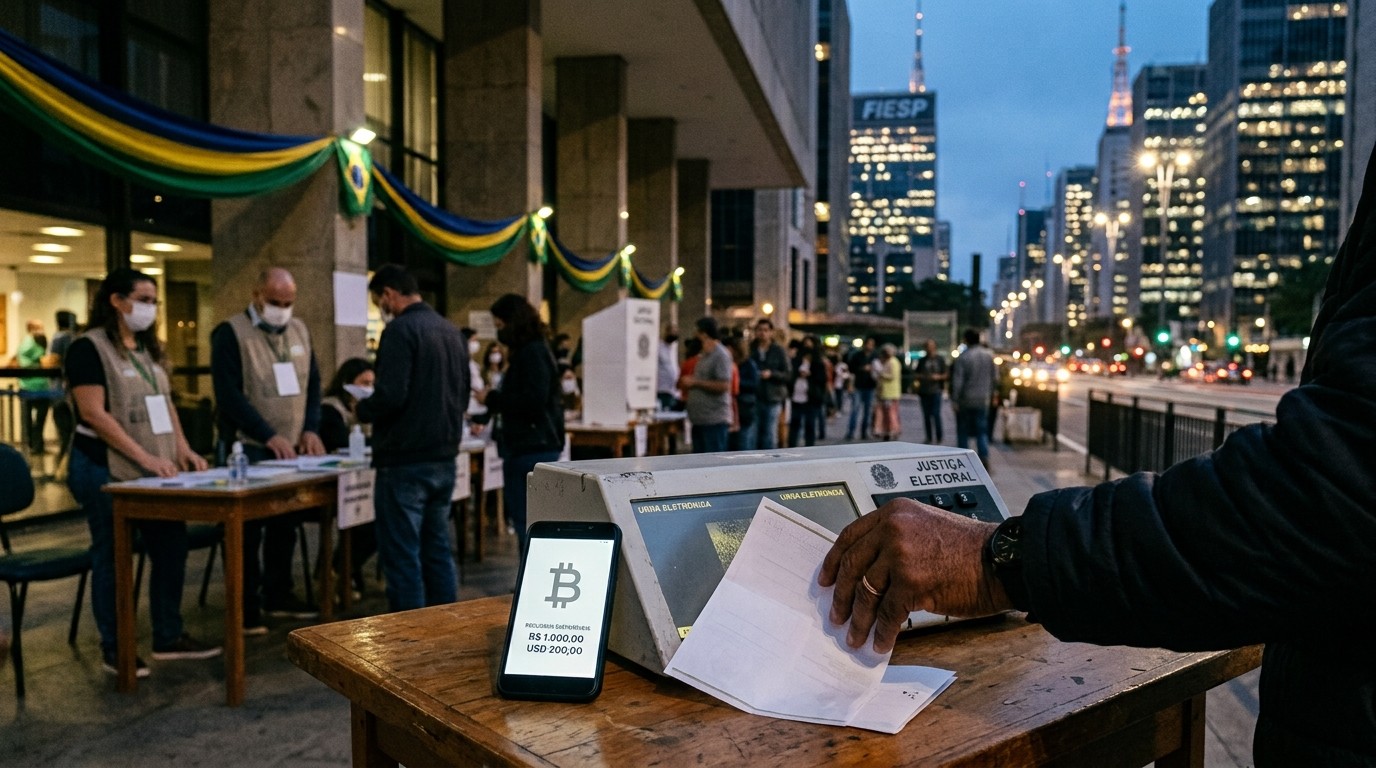

Crypto was never the loud issue of this campaign. Inflation, jobs, public safety and the old political feud took the airtime. Still, the next president inherits a market that research firms now rank first in the world for grassroots adoption, with activity estimated around $252.5 billion. That market spent the past year being pulled inside a formal licensing, reporting and foreign-exchange perimeter. Some of those duties already bite. Others land in November, and a thicker supervisory layer arrives on the first day of 2027. A change of president does not erase a central-bank resolution. It does change who appoints the people who interpret it.
A Close Vote Meets a Market Already Rewritten
The final pre-election survey, published on October 3, put President Luiz Inácio Lula da Silva at 45 percent of valid votes and Senator Flávio Bolsonaro at 42 percent. Interviewers spoke with 4,006 voters across 122 municipalities. The gap sits inside overlapping margins of error, which is a polite way of saying the first round is a toss-up dressed up as a lead. Another late survey had Lula nearer 47.8 percent and Bolsonaro at 42.1 percent. Different samples, same story: ahead, but not home.
A runoff test was even tighter. Lula at 47 percent, Bolsonaro at 46 percent. Statistically tied. I have watched enough Latin American campaigns to know that a two-point first-round edge can evaporate once the eliminated candidates’ voters pick a side, or it can harden if turnout favors the incumbent’s base in the big cities. Neither outcome is priced as certainty.
Prediction markets told a different story from the phone polls. Contracts in early October implied roughly a 62 percent chance of an eventual Bolsonaro win and about 37 percent for Lula. Those prices are not a survey of Brazilian voters. They are a clearing price among people willing to risk money on the outcome, many of them outside the country. Useful as a sentiment gauge. Dangerous as a forecast you would bet the firm on.
A poll asks people what they intend to do. A market asks people what they will pay to be right. In a race this close, both can be honest and still disagree.
What the First Round Actually Settles
Brazil’s electoral court starts releasing ballot-box results after voting ends at 5 p.m. Brasília time. The threshold is simple. A candidate needs more than half of valid votes, blank and null ballots excluded, to win outright. If that does not happen, the two highest finishers meet on October 25. Several final polls pointed toward that second round rather than a first-round knockout.
That calendar matters for compliance teams more than the speeches do. Existing cryptocurrency rules stay in force through the count, through any challenge, and through a handover if one comes. A new president does not flick a switch that cancels central-bank resolutions or federal revenue reporting. Repeal takes a process. So does a decision to leave the framework alone and enforce it harder.
Perhaps the most interesting aspect is how little the campaign has forced either side to own the details. Crypto policy is downstream of larger promises about taxes, banking and the size of the state. Those promises are real. The footnotes are not written yet.
Why the Polls and the Markets Disagree
Phone surveys and betting contracts answer different questions. A national poll weights age, region and past vote. A prediction contract weights whoever has capital and a view. International money has tended, in this cycle, to treat a Bolsonaro return as the higher-probability path even while domestic surveys kept Lula slightly ahead. I would not call one of them wrong yet. I would call the spread a warning that the runoff, if it happens, will be traded as hard as it is polled.
For crypto firms the disagreement is not academic. A Lula continuity case and a Bolsonaro reset case imply different enforcement temperatures, even if neither candidate has published a line-by-line virtual-asset bill. Capital that can move will try to front-run the interpretation. Capital that cannot, because it sits in local licenses, local bank accounts and local staff, has to plan for both.
The Rulebook Written During the Current Term
Under the present administration the central bank pulled virtual-asset companies inside its formal perimeter. One resolution set operating requirements for virtual-asset service providers: governance, customer protection, internal controls and anti-money-laundering procedures. Those duties took effect on February 2. A companion resolution built the authorization process. Firms that provide covered services are expected to seek approval rather than operate in a grey zone and hope the examiner looks the other way.
A separate foreign-exchange rule folded several crypto activities into Brazil’s FX framework. International transfers that use virtual assets, and transactions involving assets referenced to fiat currencies, no longer sit entirely outside the old exchange rulebook. That is a bigger shift than a licensing form. It changes which desk inside a bank is allowed to touch the flow, which reports get filed, and which customer checks are mandatory before the transfer leaves the building.
I have found that markets underestimate FX classification until a correspondent bank asks for it. Then the underestimate becomes a frozen payment. Brazil’s version of that lesson arrived before the campaign ads did.
- Operating standards for governance, controls and customer protection are already in force.
- Authorization is the path for firms that want to keep offering covered services.
- Cross-border and fiat-referenced activity can fall under foreign-exchange treatment.
- Reporting to the financial-intelligence unit now covers large movements into and out of self-custody.
- From November, regulated institutions face limits on dealing with firms that lack authorization.
Self-Custody Reporting Is Not a Ban
Regulators tightened the system again days before the vote. A resolution published on September 23, effective October 1, tells covered financial institutions to file specific reports with the financial-intelligence unit when virtual assets worth at least $10,000 move to or from self-custody wallets. Read that twice. It creates a reporting obligation. It does not outlaw self-custody. It does not set a $10,000 ceiling on what a person may hold or send.
The measure sits inside the existing anti-money-laundering frame. It is separate from taxation. That distinction gets lost in social feeds, where every reporting rule is described as a ban and every threshold is described as a cap. Neither description matches the text. A bank or a payment firm that sees a qualifying transfer has to tell the authorities. The user is not, on the face of this rule, forbidden from using a wallet they control.
Still, reporting changes behavior. Once a transfer above the threshold generates a file, some customers will split payments, some will stay under the line, and some institutions will simply decline the awkward ones. I have seen that pattern in other jurisdictions. The statute says “report.” The operations manual quietly says “avoid.” The gap between those two sentences is where users feel the rule.
A reporting duty is not a prohibition. It is a spotlight. People rearrange their habits under a spotlight even when the door stays open.
A compliance officer who has watched three rule cycles
The November Wall for Unlicensed Firms
Another resolution moves the deadline that treasury teams are actually circling. Starting November 6, institutions regulated by the central bank generally cannot facilitate virtual-asset market operations with service providers that are not authorized to operate in Brazil. Exceptions exist inside the rule. They are exceptions, not a loophole large enough to park a business model in.
That date does not care who is leading the polls on October 4. It arrives whether the race ends in the first round or drifts into a runoff. Banks, payment institutions and brokers that still route flow to unlicensed venues have a few weeks, not a political season, to reroute it. Industry estimates circulating in September suggested only a small share of crypto companies then active in Brazil were expected to pursue full authorization. If that estimate is even roughly right, November is a sorting event.
The compliance bill is already thinning the field. At least one regional platform concluded that licensing capital requirements were too heavy for its local book and said it would close remaining Brazilian accounts in mid-October. I do not treat one exit as a trend. I do treat it as evidence that the fixed cost of staying is no longer theoretical. Smaller firms with thin local revenue will do the same math. Some will partner. Some will leave. A few will apply and wait.
| Date | What changes | Who feels it first |
| February 2, 2026 | Operating requirements for virtual-asset providers take effect | Exchanges and custody firms |
| October 1, 2026 | Large self-custody movements must be reported | Banks and payment firms |
| November 6, 2026 | Regulated firms generally cannot facilitate business with unauthorized providers | Brokers, banks, local platforms |
| January 1, 2027 | Richer supervisory data and a precautionary hold on some large transfers | Custodians and cross-border desks |
What the Challenger’s Program Does Not Say
A Bolsonaro victory would add uncertainty precisely because the filed program does not set out a dedicated cryptocurrency policy. The electoral court’s searchable version of his government plan covers tax cuts, fiscal reform, privatization, banking, the digital economy and a proposed regulatory rollback. The index has no specific entry for cryptocurrency, stablecoins or virtual assets.
His economic text calls for lower taxes in some areas and a review of regulations, including what it describes as a revogaço regulatório, a broad repeal effort. Applying that slogan to the central bank’s crypto framework would be a guess. The filed program does not say the virtual-asset resolutions would be repealed, amended or kept. Silence is not a promise in either direction.
That absence is the contrast with the incumbent. A Lula victory leaves in office the administration that introduced the current rules. It does not guarantee those rules stay frozen. Second terms edit first-term experiments, especially when a tax consultation was shelved for electoral reasons and will have to be picked up or buried. Continuity is the base case, not a contract.
In my experience, investors over-read party brands on crypto. The operational question is narrower. Who staffs the central bank? Who writes the implementing circulars? Who decides that a firm’s authorization file is complete? Those choices sit one layer below the campaign poster, and they move prices.
Two Paths, Neither of Them a Blank Page
Think of the post-election map as two corridors that share a hallway. In the continuity corridor, licensing stays mandatory, the November restriction on unauthorized counterparties is enforced, and the delayed tax consultation returns once the political cost of a new levy looks manageable. Stablecoin flows, which dominate declared volume, would be the obvious target of any revived tax design. Reporting under the federal revenue framework would keep running either way.
In the rollback corridor, the new team reviews resolutions and asks which duties are essential to anti-money-laundering and foreign-exchange control, and which are cost without a clear public purpose. A full repeal is the least likely version of that review, because unwinding FX classification and intelligence reporting in a market this large would spook banks even if it pleased traders. A narrower edit, slower authorization, or a lighter capital bar is easier to imagine. Easier is not the same as promised.
- Continuity keeps the licensing perimeter and likely revives the tax conversation after the vote.
- A review government might slow new duties without deleting the ones already tied to financial intelligence.
- Either president inherits the November counterparty rule and the 2027 data requirements unless they actively change them.
- Court challenges and industry lobbying will shape the footnotes more than rally lines will.
The Tax Pause That Did Not Pause Reporting
Tax policy is the lane where the election most clearly delayed a decision. Earlier this year the finance ministry planned to postpone a public consultation on crypto taxation, avoiding a politically costly proposal before the presidential vote. The consultation was expected to look at the tax treatment of crypto flows, including transactions that involve stablecoins. No final tax born of that consultation was enacted before the pause. The file is unfinished, not closed.
Reporting did not take the same holiday. The federal revenue service introduced a disclosure system, often called DeCripto, under a normative instruction. Transactions carried out from July 2026 fall under the new reporting design. The framework lines Brazil up with the international crypto-asset reporting standard used by tax authorities that want annual, standardized visibility rather than occasional audits. If you moved assets after that start date, the disclosure logic is already pointed at the flow.
People mix these two tracks. One is a possible tax on certain transfers or gains, still in consultation limbo. The other is a duty to tell the revenue service what happened. You can owe a report without owing a new tax, and you can face a future tax built on data the report already collected. That sequencing is deliberate. Authorities prefer the map before they set the toll.
Stablecoins Carry Most of the Declared Volume
Stablecoins are the part of the market the tax file cannot ignore. The federal revenue service said in July that stablecoins represented roughly 80 percent of declared crypto transaction volume, up from only 3.5 percent in 2019. That is not a niche. That is the pipe. Brazilians use dollar-linked tokens to hold value, to settle between platforms, and to move purchasing power when the local price of a foreign currency jumps.
The central bank has separately tightened supervision of stablecoin-linked transfers and of crypto activity tied to foreign exchange. Providers must identify owners of self-custody wallets in covered FX transactions and keep processes for checking where virtual assets come from and where they go. Identification plus origin checks is the unglamorous core of the new regime. It is also the piece that makes a $10,000 report useful to an analyst instead of a pile of anonymous hashes.
Would a future tax fall on the stablecoin leg, on the conversion into reais, or on the gain when a token is spent? The shelved consultation was supposed to argue that out in public. It did not. Whoever wins in October, or in a runoff, will be asked the question again by the finance ministry, by banks that do not want to be the unpaid tax collector, and by users who already treat a dollar token as a savings account.
Declared crypto volume, roughly:
  2019 stablecoin share: 3.5 percent
  Recent stablecoin share: about 80 percent
  Estimated national crypto economy: $252.5 billion
Why Brazil Sits at the Top of the Adoption Rankings
The vote is happening in the country a major blockchain analytics firm now places first on its 2026 global crypto adoption index, ahead of the United States, Nigeria and Japan. Brazil did not win every category. It placed second in cross-border flows, third in service flows, third in the domestic peer-to-peer economy and fourth in on-chain balances. The combined score, under a revised methodology, produced the top overall rank.
Those figures are estimates built partly on on-chain data and partly on web traffic to services. They are not an official census of every transaction inside Brazil. Treat the $252.5 billion as a scale marker, not a line item in the national accounts. Even with that caution, the ranking explains the regulatory rush. You do not build a licensing wall around a hobby. You build it around a payment habit.
Grassroots use is the detail I keep coming back to. This is not only funds and trading desks. Peer-to-peer activity and service flows rank near the top, which usually means ordinary people opening apps, not just institutions wiring size. A rule that raises the cost of a small platform therefore lands on retail access, not only on a trading floor in São Paulo or Rio.
Adoption Without a Single Winning Category
There is a useful humility in finishing first without leading any one lane. Cross-border strength reflects remittances, trade settlement and the stablecoin habit. Service-flow strength reflects exchanges and brokers that Brazilians actually open. Peer-to-peer strength reflects transfers that skip a centralized order book. On-chain balances show that value stays, at least for a while, rather than only passing through.
A government that wants to supervise all four lanes needs more than one tool. Licensing covers the service providers. Foreign-exchange rules cover the border. Intelligence reports cover large self-custody hops. Revenue disclosures cover the tax map. The 2027 data set, which asks for customer balances, custody positions, proof of reserves and assets committed to staking, tries to see the stock as well as the flow. Stacked together, that is a full perimeter. It is also a lot of forms.
Does the ranking survive the perimeter? Maybe. Countries have stayed heavy users after licensing waves, especially when the alternative is a volatile local price or an expensive bank wire. Countries have also seen activity shift to foreign apps and informal channels when local licenses become a club with a high cover charge. Brazil is large enough to do both at once: a regulated core, and a fringe that the November rule is designed to starve of bank access.
The Calendar That Does Not Wait for a Winner
Here is the sequence I would pin above a desk. Ballots on October 4. Results the same evening, with the usual caveats about challenges. A runoff on October 25 if required. On November 6, the counterparty restriction for unauthorized virtual-asset firms. On January 1, 2027, expanded supervisory data covering balances, custody, reserves and staking, plus an anti-fraud measure that imposes a 24-hour precautionary retention on certain virtual-asset transfers above $10,000 to overseas entities or self-custody wallets while the provider runs extra risk checks.
That 24-hour hold is easy to misread. It is not a confiscation window. It is a pause so the institution can look harder before the value leaves a perimeter it can still see. For a user waiting on a transfer, a day is a day. For a desk moving size, a day is a funding and market-risk problem. Build it into settlement assumptions now, not on New Year’s Eve.
None of these dates are campaign promises. They are published resolutions and instructions. Changing them requires a new legal act, not a victory speech. That is the sentence I wish more market commentary would lead with.
What Holders Should Actually Watch
If you keep assets on a local platform, the practical question is whether that platform will be authorized, partnered with someone who is, or gone. Account-closure notices in October are not abstract. Download records, confirm withdrawal routes, and do not assume a foreign login replaces a local bank payout. I have watched users discover, too late, that the app still opens and the withdrawal rail does not.
If you use self-custody, the October reporting rule does not take the keys. It does mean that a qualifying hop through a covered institution can generate a file. Keeping clean records of source of funds is no longer a nice-to-have for anyone who moves size. The same is true of the foreign-exchange identification duties when a transfer is part of a covered cross-border deal.
If you are a company paying contractors in stablecoins, talk to counsel about the revenue-reporting start date and about whether your Brazilian entity is the one expected to disclose. The international reporting standard is built for intermediaries, but local instructions decide who files. Guessing is an expensive hobby.
- Confirm whether your platform intends to seek authorization or exit.
- Treat $10,000 self-custody movements through covered firms as reportable, not banned.
- Assume November will narrow bank access for unauthorized venues.
- Plan for a possible return of the stablecoin tax consultation after the election.
- Build a one-day delay into large outbound transfers from 2027.
What Firms Should Budget For
Authorization is a capital and people problem before it is a legal problem. Governance, internal controls, customer-protection procedures and anti-money-laundering systems are not PDF exercises. They need staff who can explain a wallet screening hit to an examiner without improvising. Firms that looked at the capital bar and left were making a cost decision. Firms that stay should budget for the exam, not only the application fee.
Banks have a different problem. From November they are not supposed to facilitate market operations with unauthorized providers, subject to the rule’s exceptions. That pushes relationship managers to inventory every crypto-touching client. Some of those clients will be payment companies. Some will be importers settling an invoice in a dollar token. The second group is where classification fights start, because a commercial payment and a speculative trade can look identical on a blockchain and very different in a contract.
Proof of reserves and staking disclosures in 2027 will force custodians to show their work. Platforms that have been loose with client asset segregation will find the data request less forgiving than a marketing page. I would rather see a boring reserve report than a clever one. Examiners tend to agree.
Foreign Desks and the Cross-Border Angle
Brazil’s place near the top of cross-border flows is why foreign exchanges cannot treat this as a domestic curiosity. If a Brazilian user reaches a foreign app through a local bank, the bank’s November duty still exists. If a foreign firm wants onshore accounts, authorization becomes the ticket. If neither happens, volume can migrate to channels the central bank sees less clearly, which is exactly the outcome the FX and reporting rules are written to limit.
There is a competitive angle too. A strict onshore regime can push activity to neighbors or to offshore books. It can also make Brazil the place where institutions are willing to custody size, because the rules are knowable. Both effects can show up in the same quarter. The adoption index will not tell you which one won until the next edition, and by then the licensing cohort will already have been sorted.
Dollar stablecoins are the instrument to watch in that cross-border lane. They are most of the declared volume, they reference a fiat currency, and they are therefore the transfers most likely to be pulled into FX treatment. A campaign that never said the word stablecoin can still decide, through appointments, how hard that pull is.
Scenarios After the Ballots Are Counted
Scenario one: Lula wins outright or in a runoff, and the regulatory machinery continues with minor edits. The tax consultation returns in 2027 language rather than 2026 language. Authorization timelines slip for applicants who filed in good faith, because agencies always slip, but the November counterparty rule is not suspended. Stablecoin users see more forms and, later, a possible levy on specific flows. Market structure consolidates around licensed names.
Scenario two: Bolsonaro wins, and the revogaço is applied selectively. Capital requirements are reviewed. A public statement promises innovation and lighter touch. The financial-intelligence reports and the FX identification duties mostly survive, because no new treasury wants to explain a blind spot in a market of this size. The tax consultation is delayed again, or redesigned around a lower rate. Uncertainty lasts longer than the victory lap, which is its own cost.
Scenario three: a messy count, a narrow runoff, and three months in which nobody senior will sign a controversial circular. That scenario is underrated. Civil servants implement what is already published. They do not invent a crypto truce. Firms that needed a waiver discover that an election is not a waiver.
I lean toward scenario one or two depending on the runoff, and I keep scenario three on the board because close elections produce cautious ministries. None of the three cancels the rules already in force on the morning of October 4.
Politics, Prices and the Habit Underneath
Will the result move bitcoin or the large-cap tokens? Briefly, maybe, if a winner’s speech is read as deregulation or as a crackdown. The more durable price is the spread between using a licensed local rail and using a workaround. That spread is a policy variable. It widens when banks drop unauthorized venues. It narrows if a new government slows exams or cuts the capital bar.
Underneath the spread is a habit. Brazilians did not climb the adoption table because a candidate told them to. They did it through inflation memory, a sophisticated instant-payment culture, a huge domestic market and a stablecoin that behaves like a dollar account you can send at odd hours. Regulation is arriving because the habit is already there. Reversing the habit would take more than a resolution. Ignoring it is no longer an option for either campaign, even if both managed to ignore it in the index of their programs.
That last point still surprises me. The world’s leading adoption market, by one widely cited index, held a presidential election in which neither leading program made virtual assets a named plank. The rules advanced anyway, on central-bank paper and revenue instructions, in the months when candidates were busy elsewhere. Technocratic drift is a real author of market structure. Elections decide whether the drift continues, speeds up, or gets a red pen.
How to Read the Night Without Overreading It
When the first ballot-box numbers appear, ignore the early interior municipalities if you are trying to call a crypto-policy winner. Brazil’s count has a geography. Coastal metros and smaller inland towns do not report on the same curve. A first-round result above 50 percent of valid votes would be the surprise. A second-round booking would match what the final surveys, taken together, were pointing at.
If the night ends in a runoff, treat October 25 as the policy date and November 6 as the market-structure date. They are not the same. A candidate can still be campaigning when banks start cutting unauthorized counterparties. Compliance calendars do not move to accommodate debate schedules. I would rather a firm miss a headline than miss that distinction.
And if you are only a holder, not an operator, the night is simpler. Your keys still work. Your local app might not, if it has already scheduled an exit. Your next large transfer through a bank may generate a report. Your stablecoins remain the bulk of what the revenue service says it sees. The election changes the odds of the next edit. It does not rewind the edit that already landed.
A Practical Checklist for the Next Ninety Days
Ninety days from this vote covers a possible runoff, the November counterparty rule and the first stretch of life under a president-elect who may not yet be inaugurated. Inauguration timing and transition teams will fill the newspapers. The checklist below is the part that affects a wallet.
- Map every venue you use to a status: applying for authorization, already inside a regulated group, or planning to leave.
- Separate self-custody balances from balances that must pass through a reporting institution to reach a bank.
- Note the $10,000 figure as a reporting trigger for covered firms, not as a legal maximum.
- Ask your accountant whether July 2026 onward activity belongs in the new disclosure system.
- Do not model a tax rate that has not been enacted. Model the possibility that a consultation restarts.
- If you settle cross-border invoices in tokens, confirm the FX classification with the bank, not with a forum.
- Put January 2027 in the project plan for reserve data and for the precautionary hold on large outbound transfers.
None of those steps requires you to guess the winner. That is the point. The expensive mistakes in rule transitions come from waiting for political clarity that the legal text does not need. Brazil has already published the sequence. The election decides the editors, not the existence of the draft.
The Open Questions Worth Keeping
A few questions are still genuinely open, and pretending otherwise is how commentary goes stale. Will the authorization bar be enforced as written, or will transitional relief appear for firms that filed and are waiting? Will the stablecoin tax consultation return as a narrow reporting-plus-withholding design, or as something broader? Will the regulatory-repeal language in the challenger’s program ever be aimed at virtual-asset resolutions by name? Will proof-of-reserves data in 2027 be public, supervisory, or both?
I do not have clean answers this afternoon, and neither does the campaign literature. What I do have is a market that ranks at the top of global adoption estimates, a pair of candidates separated by a few points, and a stack of duties that activate on dates already printed. That combination is enough to justify paying attention after the victory speeches fade.
Brazil’s crypto story for the next year will be written less in rally clips than in authorization files, intelligence reports and a tax consultation that was postponed rather than resolved. October 4 starts the political half of that story. It does not reset the half already in force. If the night ends without a winner above 50 percent, circle October 25, then circle November 6 anyway. The market will not wait for the second ballot to start sorting who still has a bank.
]]>


