
Have you noticed how often copper shows up in conversations that used to be about oil, gold, or tech stocks? I have. A few years ago the metal felt like background noise. Now it sits at the center of power grids, data centers, defense programs, and a messy breakup between trading blocs that once pretended the world was one big warehouse. London prices hovering near record territory are not a curiosity. They are a warning that the last easy tons may already be spoken for.
Why This Copper Squeeze Feels Different
Every commodity cycle has a story. This one is not only about mines that take a decade to build. It is about governments quietly parking metal where the rest of the market cannot reach it. In my experience, that changes the tone of a rally. Speculation can fade. Physical scarcity does not shrug.
Visible inventories have fallen to levels that metals desks call unprecedented. That word gets overused. Here it fits. When two of the largest economies treat copper as a strategic buffer instead of a freely traded input, the leftover pool shrinks fast. Analysts tracking the physical market now talk about a possible move toward roughly fifty percent higher prices by the second quarter of 2027, with a level near $22,050 a ton floated as a working target rather than a fantasy headline.
Get long and buckle up.
That line from a veteran commodities strategist still circulates because it captures the mood. Tight refined products, scarce rare earths, stressed industrial metals, and even certain crops all rhyme. The theme is simple: own the bottlenecks before the bottlenecks own you.
Stockpiles Are No Longer Just A Safety Net
China’s strategic holdings are estimated around 2.05 million tons. That is not a rounding error. It is roughly 43 percent of global above-ground inventories that analysts can see. Add tariff-driven American stockpiling that could lock up another 1.3 million tons in warehouses by year-end, and you get a startling share of the world’s visible copper sitting behind policy doors.
Put those two flows together and you land near 71 percent of global inventories encumbered by official or quasi-official demand. I keep rereading that figure because it is the kind of number that turns a cyclical shortage into a structural squeeze. The metal still exists. Traders just cannot get at most of it.
Perhaps the most interesting aspect is how quickly “available” becomes a political word. A warehouse receipt is not the same as a ton you can bid for tomorrow morning in a third country that is not running a stockpile program.
The De-Globalization Endgame In Plain Language
Decades of thin investment in new mines already left the market brittle. De-globalization poured glue into the cracks. Export controls, tariffs, friend-shoring, and resource nationalism do not need to ban copper to choke the free float. They only need to redirect it.
At the current pace of official accumulation, freely available inventories could approach zero by the end of 2028. That date is not a prophecy. It is a breaking point the market will try to avoid through higher prices or demand destruction. Markets hate both. They usually pick the first until consumers scream.
The combination of de-globalization and decades of underinvestment in supply has created vulnerabilities such that stockpiling can encumber most of what the world thought was spare metal.
I’ve found that people still treat copper as if it were a spreadsheet metal. Tonnes in, tonnes out, price finds balance. That model assumes a single global pool. That pool is being partitioned.
From Data Centers To A Liquidity Crisis
The popular story last year was artificial intelligence and power-hungry server halls. That demand is real. Cables, busbars, transformers, and cooling systems eat copper. So do electric vehicles, grid upgrades, and the rearmament wave that defense ministries no longer whisper about.
Yet the plot twist is liquidity. When free-floating inventories collapse, the market stops being a story about extra gigawatts and starts being a story about who still has metal to sell. Access becomes the scarce good. Price is the rationing tool.
- Grid buildouts need more conductor than planners budgeted five years ago.
- Data centers concentrate demand in a few regions that already compete for the same refined units.
- Defense and industrial policy treat copper as a security input, not a disposable commodity.
- Mine project pipelines remain slow, capital-heavy, and politically messy.
None of those bullets is new on its own. Together they explain why a bidding war for remaining accessible metal can run until someone blinks. Demand destruction is the ugly off-ramp. Higher prices are the smoother one, until they are not.
Resource Nationalism Changes Who Gets The Last Ton
China has already shown how quickly critical materials can be placed on a shorter leash. Rare earths grab the headlines. Other industrial inputs follow the same logic. Western governments talk about resilient supply chains and then discover that resilience costs more copper, not less.
When export licenses, tariffs, and warehouse incentives pull metal into national buffers, third markets become residual buyers. Residual buyers pay up. That is not ideology. That is how physical markets work when the float disappears.
In my view, this is why “own the bottlenecks” is more than a slogan. The bottleneck is no longer only the mine. It is the combination of mine, smelter, warehouse rules, and the passport of the buyer.
What The Numbers Actually Imply
Let’s keep the arithmetic honest. If official programs already command a majority of visible stock, the remaining sliver has to clear every surprise. A strike. A delayed concentrate shipment. A hotter summer that cooks transformers. A faster data-center schedule. Any of those can look modest on a global balance sheet and still explode in the free market.
| Factor | What It Does | Market Effect |
| Strategic stockpiles | Removes metal from free float | Higher scarcity premium |
| Tariff-driven warehousing | Parks tons inside one jurisdiction | Regional price gaps |
| Slow mine supply | Limits the refill rate | Longer squeeze |
| Electrification demand | Raises baseline consumption | Less room for error |
A table cannot capture panic. Charts of vanishing inventories do a better job. One widely shared graphic last week made even cautious metals desks sit up. Empty shelves are a language everyone understands.
Currency Debasement And The Scarcity Bid
Physical tightness is only half the cocktail. Easy money and eroded purchasing power push investors toward things that cannot be printed. Copper is not gold. It still gets pulled into the same conversation when people worry that paper claims multiply faster than real assets.
Policy intervention adds another twist. Industrial strategy, tariff design, and reserve building are not market-neutral. They create bid where none existed and they hide supply that used to be available. That is how you get a supercycle thesis that survives a soft patch in one end-market.
I’ve sat through enough commodity winters to stay skeptical of every “this time is different” speech. The difference here is not poetry. It is the share of inventory that no longer answers to price alone.
How A Fifty Percent Rally Could Actually Happen
Price targets sound neat. Paths are messy. A move toward the low twenty-thousands per ton does not require a cartoon shortage. It requires a sequence.
- Free inventories keep shrinking as official buying continues.
- Merchant stocks fail to refill because concentrates and scrap stay tight.
- Premiums for prompt delivery jump in regions outside the stockpile umbrellas.
- Fabricators scramble, then delay projects, then pay up anyway.
- Financial buyers pile in once the physical story is undeniable.
Step five is the one that makes journalists write “melt-up.” It is also the one that burns latecomers. The smarter read is earlier: the physical market is already sending the signal.
Demand Destruction Is Not A Soft Landing
Analysts keep repeating that the market must prevent a zero free-float outcome through demand destruction or higher prices. People hear “demand destruction” and imagine a tidy slowdown. It is not tidy. It means cancelled cable runs, postponed substations, thinner gauges that fail sooner, and factories that lose contracts because they cannot lock metal.
Higher prices are the civilized version of the same rationing. They tell the least urgent buyer to wait. The trouble starts when the urgent buyers are governments, utilities, and defense programs that do not wait.
That is why a bidding war for remaining accessible metal can look irrational from a textbook curve and still be perfectly rational from a planner’s desk.
What Investors Keep Getting Wrong
First mistake: treating exchange inventories as the whole story. Visible stocks are a flashlight, not the warehouse. Off-warrant metal, strategic reserves, and in-transit units muddy the picture. When the flashlight beam gets smaller, you do not assume the room got bigger.
Second mistake: assuming new mines will save the decade on schedule. Permitting, community opposition, water, power, and capex inflation have a habit of slipping calendars. Even good projects arrive late.
Third mistake: believing substitution is easy. Aluminum and other workarounds help at the margin. They do not replace copper in every high-conductivity, high-reliability job. Engineers already know this. Spreadsheets sometimes pretend otherwise.
The Bottleneck Portfolio Mentality
Wall Street loves a clean theme. “Own the bottlenecks” is clean enough to travel. It also happens to match the physical facts. If refined petroleum products, certain agricultural goods, rare earths, and copper all tighten at once, the common thread is constrained throughput, not a single demand fad.
That does not mean every miner is a gift. Cost curves, jurisdiction risk, and balance sheets still matter. It does mean the old habit of waiting for a fat inventory cushion before taking the metal seriously is getting expensive.
Scarcity stack in one glance:
  Official stockpiles absorb float
  Tariffs redirect tons
  Mines refill too slowly
  Electrification lifts the floor
  Price does the rationing
Is that too neat? A little. Markets are sloppy. Still, if you need a pocket card for why copper stopped being boring, that stack is honest enough.
Regional Splits Will Get Louder
A global price on a screen hides local pain. When metal is locked in one customs territory, another region pays a premium that looks absurd until you need cathode next month. Expect more talk of location spreads, warehouse incentives, and odd flows that only make sense if you follow the policy, not the textbook arbitrage.
I’ve found that those spreads are often the earliest tell. Before the big number on the futures board explodes, the unglamorous premiums start to misbehave.
Defense, Grids, And The Quiet Competition
Rearmament is not a footnote. Ships, aircraft, munitions lines, and hardened infrastructure all pull copper. So do the grids that keep those systems alive. When two large economies treat the same metal as a strategic reserve, smaller buyers become price takers with worse timing.
This is the part of the story that feels less like a trading desk and more like industrial policy with a ticker symbol. You do not have to like that shift to respect it.
Risks That Could Cool The Rally
A serious article should not sell a one-way ticket. A deep global slump can smash even a tight metal. A sudden release from strategic stocks can flood a window. A technology leap that uses less copper per unit of power would help, though those leaps usually arrive slower than slides claim.
Recycling can also surprise to the upside if prices stay high long enough to pull scrap out of buildings and junkyards. High prices are a magnet. They are also a signal that the easy tons are gone.
- A sharp recession would cut construction and auto demand.
- Policy reversals could free some warehoused metal.
- Faster substitution in low-spec uses could shave a slice of consumption.
- Better mine execution could add supply later in the decade.
None of those risks erase the current inventory math. They just keep honest people from treating a forecast as a promise.
How To Think About Timing Without Playing Hero
Trying to catch the exact week inventories hit a psychological low is a sport, not a plan. The more useful question is whether the free float is still shrinking while structural demand stays firm. If both remain true, dips are arguments, not obituaries.
Position sizing matters more than bravado. Copper can whip traders who treat a physical squeeze like a meme. Margin and patience are different skills.
For long-horizon investors, the cleaner frame is bottleneck exposure across miners, smelters with real feed, and related infrastructure names that live or die by metal availability. For short-horizon traders, respect the possibility that official buying does not care about your technical level.
A Human Read On A Very Physical Market
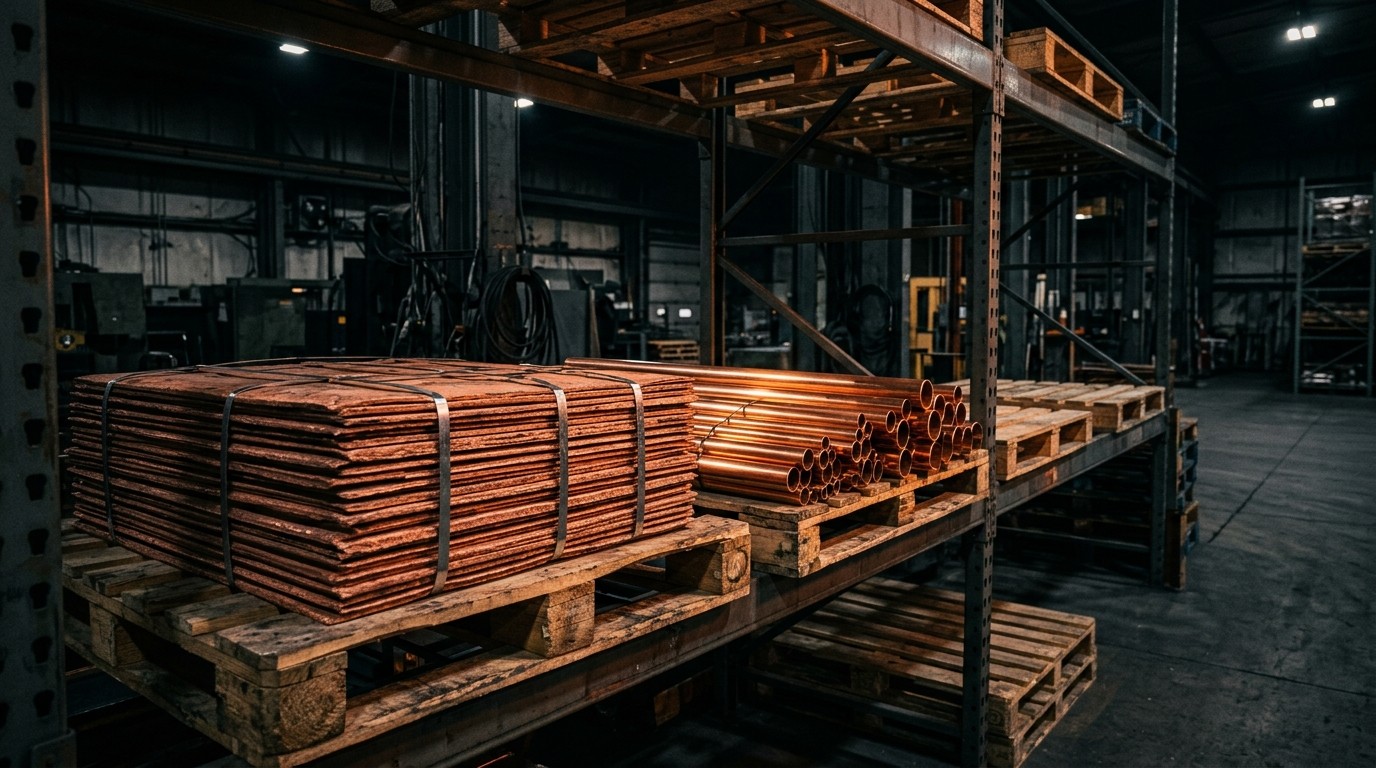
I keep coming back to a simple image. A warehouse that used to feel half full now has reserved tape across most of the pallets. The remaining aisle is where the entire merchant world has to shop. Of course the price in that aisle gets rude.
Is seventy-one percent of visible inventory really going to sit behind policy walls by year-end? Estimates move. Methods differ. Directionally, the squeeze is not a rumor. London prices near records at the start of the week were the market’s way of clearing its throat.
When access to metal becomes the constraint, the last freely traded tons set the price for everyone else.
That sentence is the whole thesis in one breath. De-globalization did not invent copper demand. It invented new fences around the supply that used to slosh across borders with less drama.
What To Watch Next Without Getting Lost
Watch exchange stocks, yes. Also watch cancelled warrants, regional premiums, scrap discounts, treatment charges, and any hint that official buying is accelerating rather than pausing. Watch mine guidance that quietly slips a year. Watch grid interconnection queues that refuse to shrink.
If those tapes stay tight while speeches about energy transition and security stay loud, the copper squeeze is not a headline. It is the operating system of the next few years.
Will prices print that ambitious 2027 target on schedule? Maybe not to the dollar. Markets love to humiliate precision. The broader claim is harder to mock: freely available copper is becoming a luxury good inside an industrial world that still talks as if it were a bulk commodity.
The Uncomfortable Conclusion
Scarcity with a political accent lasts longer than scarcity with a weather accent. A drought ends. A stockpile program can run for years. Underinvestment takes even longer to reverse. Put those clocks together and you understand why serious desks are talking about the most acute copper scarcity on record rather than a garden-variety restocking bounce.
If you only remember one thing, remember this. The story has already shifted from “AI needs more wire” to “who still has wire to sell.” That shift is the de-globalization endgame in the metals market, and it is not finished.
Own the bottlenecks if that matches your risk tolerance. Or at least stop assuming the warehouse will always refill before the bid arrives. The aisle is getting narrower. Prices have started to notice. The rest of the market is still catching up.