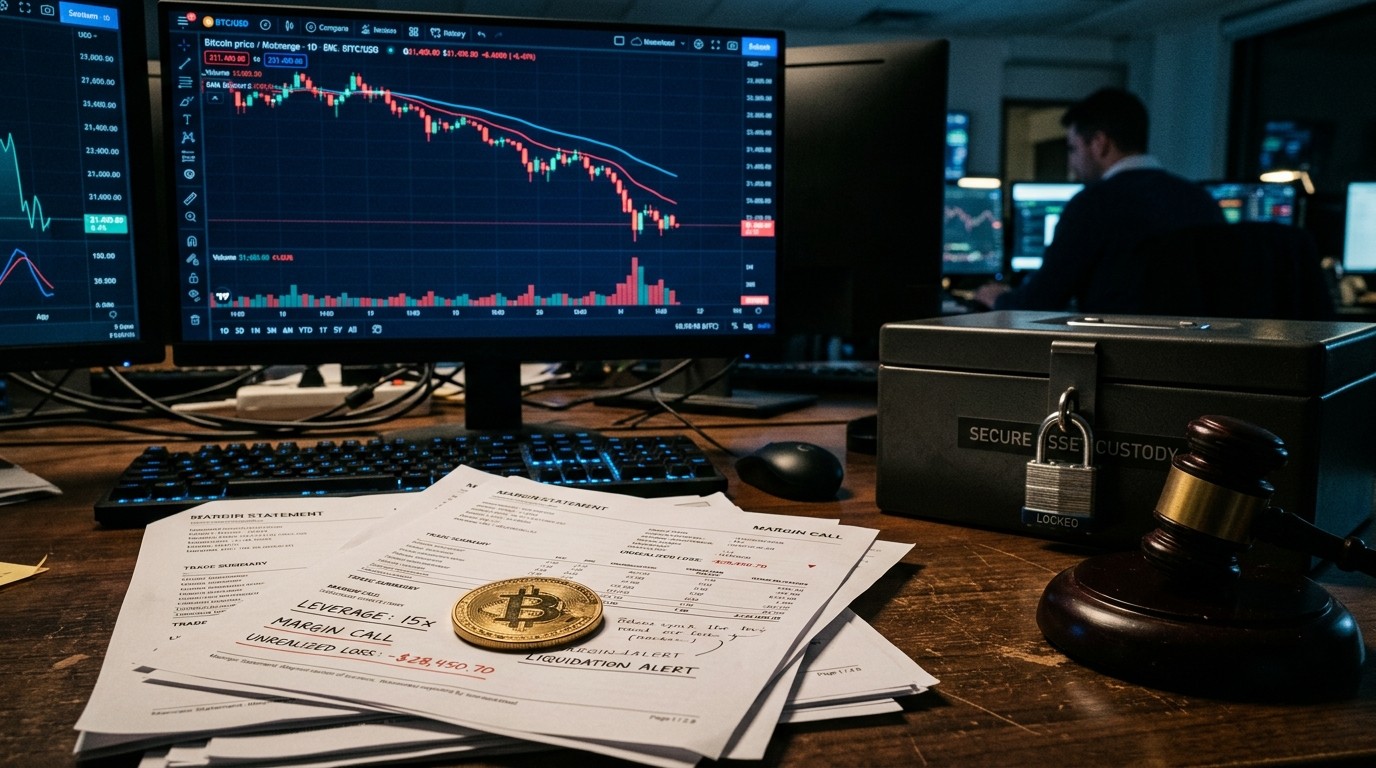

Here is the awkward part nobody likes saying out loud. You can post a token against a futures book and feel clever about not selling it. Then the token slips, the contract slips too, and the account is suddenly short on recognized value. I have watched people treat that moment like a software glitch. It is not. It is arithmetic meeting custody rules.
Why Token Margin Feels Simple Until It Is Not
Using crypto as derivatives collateral is no longer a fringe thought experiment. Intermediaries can, under tightly written staff conditions, count certain customer digital assets when they test whether an account is undermargined and when they run specified segregation math. That permission did not appear last week as a free-for-all. It sits inside older no-action language, older customer-protection rules, and a clearinghouse’s own risk appetite.
A recent staff FAQ refresh talked about tokenized versions of investments already allowed for customer funds, plus blockchain records. Useful. Narrow. It does not rewrite the margin test. If a headline made it sound like every coin now travels as cash, the headline overreached.
In my experience, the confusion starts with one number. People hear “twenty percent” and treat it like a helmet. A helmet does not stop the road from moving. A haircut only discounts the price you already have. When that price falls, the discount applies again to the new, smaller number.
Three Books, Not One Haircut
The same bitcoin can touch three different calculations. Mix them and you get a fake answer.
- The customer account at the futures intermediary, where qualifying tokens may count toward margin after a policy haircut.
- The clearing organization, which sets its own initial-margin discounts and must revisit them on a regular cycle.
- The firm’s proprietary inventory, where capital charges on the house book are a separate problem.
Those three percentages can line up by coincidence. They still belong to different balance sheets. I’ve found that traders who only memorize one figure later argue with a margin clerk who is reading a different schedule. That argument never ends well.
The customer still owns the token. The recognized value is what the rule set is willing to count today.
A Plain Illustration, Not a Prediction
Take a customer who posts bitcoin marked at $100,000. Assume the relevant intermediary calculation applies a 20% haircut. Recognized value starts at $80,000. Now let the spot price fall 15% to $85,000 and keep the same 20% haircut. Recognized value becomes $68,000. No coin left the wallet. Twelve thousand dollars of counted collateral just evaporated.
Hold the futures requirement at $75,000 for a second. Before the drop, the account had a $5,000 cushion. After the drop, it is $7,000 short. That gap moved by $12,000 even before the futures position itself lost money. If the contract also bleeds $10,000, the pressure stacks. The cash call still depends on other balances, settlement timing, portfolio treatment, and house rules. The point of the example is to isolate one moving part.
Run it the other way. Token price flat, futures book ugly: you can still get a deficit. Token ugly, futures book fat: the combined account might stay above water. You cannot infer a margin call from a chart alone. Account equity, product exposure, and the firm’s house buffer all matter.
Twenty Percent Is a Floor, Not Armor
A 20% charge is not insurance against a 20% slide. Start with $100,000. After the haircut you get $80,000 of credit. If spot then drops 25% to $75,000, the same haircut leaves $60,000. Recognized credit fell $20,000. The ratio hits the new price every time.
The floor can also rise. If risk policy wants 30%, a $100,000 holding counts as $70,000 on day one. After that same 15% price drop to $85,000, it counts as $59,500. Change the discount and the market at the same moment and the two hits compound. Whether a firm actually widens its haircut in a messy week is a policy question. The staff letter does not answer it for you.
Payment stablecoins get a different treatment. Fair market value plus the firm’s risk haircut. A token trading at 98 cents does not keep a full dollar of regulatory credit because an issuer talks about par redemption. Access to that redemption, market price, and the haircut all sit in the same sentence. It would be sloppy to borrow a 2% proprietary capital charge and slap it on a customer’s stablecoin margin. That 2% lives on the house book.
The Same-Asset Exception Is Narrow On Purpose
There is a tighter path when a customer posts a non-stablecoin digital asset against a contract that is both based on and denominated in that same asset. For the permitted offset against the deficit in that specific contract, the clearing organization’s haircut may govern alone. That does not turn the coin into universal collateral for every other product in the account. Mixed books still face the ordinary stack of requirements outside the exception.
Perhaps the most interesting aspect is how often people skip that last sentence. They hear “same asset” and assume the whole portfolio now travels at a friendlier discount. It does not.
What Clearinghouses Actually Decide
A derivatives clearing organization may accept crypto, including qualifying payment stablecoins, as initial margin if the asset meets the test for minimal credit, market, and liquidity risk. The clearinghouse sets haircuts that contemplate stressed markets and reviews them at least monthly. There is no single official bitcoin discount published for every venue.
A house can demand a fatter cut, cap concentration, restrict a coin, or refuse it. The intermediary’s treatment of a customer deposit and the clearinghouse’s treatment of collateral posted up the chain are different links. You can see a token sitting in an FCM account while the clearinghouse is paid in something else entirely.
The easy mistake is dragging a proprietary capital charge into the clearinghouse haircut conversation. One figure is a net-capital deduction on the firm’s own coins. The other is a risk discount on initial margin the clearinghouse is willing to hold. Question numbers in staff FAQs keep those lanes separate for a reason.
| Calculation | Whose asset | Who sets the cut |
| Customer margin at the FCM | Customer token | Staff conditions plus firm policy |
| Initial margin at the DCO | Collateral accepted by the house | Clearinghouse risk rules |
| Proprietary capital charge | Firm inventory | Capital treatment on the house book |
Tokenized Funds Are Not Automatic Margin
A fund share represented on a chain can carry the legal and economic rights of a conventional eligible share. Speed of transfer is only one slice of margin quality. Redemption terms, who can receive the shares, settlement limits, and the ownership record still matter. Equivalence of rights beats a pretty confirmation screen.
A large pool of government paper underneath a token does not prove a clearinghouse has blessed that token as initial margin. Program rules decide. I would rather read those rules than a marketing deck about settlement speed.
When The Price Falls, Three Parties Feel It
The customer feels it first. Maintain required margin or face a call, a forced cut, or liquidation under the account agreement. The intermediary must watch its exposure and keep customer property segregated. The clearinghouse watches members and the assets it accepts. Linked duties. Not identical duties.
Federal law still bars an FCM from using one customer’s property to carry another customer’s book. Staff conditions explain why a firm may need to drop its own money into segregation when customer accounts are short, including deficits. A fast collateral move is not just a push notification for one trader. It changes a protected pool.
Time makes the chain messier. Daily segregation reports close as of the end of a business day. Token prices do not. A firm can call more often under its own risk policy. A blockchain timestamp does not, by itself, fix the legal value a clearing organization will accept if the relevant market goes thin.
Segregation protects customer property. It does not freeze the market price of that property.
House Margin Can Sit Above The Venue Minimum
Customer agreements often add a buffer on top of a clearinghouse schedule. Looking only at a public product margin table can understate what your intermediary will demand. The reverse is also true. A clearinghouse that recognizes a token does not force every firm to offer that token to clients.
Early no-action use was tighter. For an initial stretch, firms relying on the position were limited to payment stablecoins, bitcoin, and ether as customer margin, with notices for serious operational or cyber trouble and weekly reporting by asset and account class. After that window, other qualifying assets can enter if continuing conditions are met and, in some cases, if revised risk policies are filed first. Not every intermediary flipped a switch on the same calendar day.
A separate staff path covers customer crypto sent to foreign brokers in certain foreign futures setups. Location and reuse rights can change in that structure. Do not fold it into a domestic clearinghouse story without reading the actual letter and the account paperwork.
The Case For Crypto Collateral Still Has Edges
There is a real operational case. A trader who already holds the asset may avoid selling just to raise cash margin. Tokenized fund shares can keep a claim on an eligible investment while moving faster inside approved pipes. Officials tested that use case with reporting and monitoring. That is not the same as saying market risk left the building.
Faster settlement does not cancel valuation risk. A token can confirm quickly and still gap lower. Ownership claims can still take time to verify when markets get ugly. Liquidity in a calm tape is not liquidity in a stressed tape. Clearing rules still ask about credit, market, and liquidity risk. Staff conditions still ask for valuation policies and deductions.
- Hold a customer token as margin under specified conditions.
- Hold a firm token as inventory and take the capital hit that comes with it.
- Invest customer cash in a tokenized wrapper of an already permitted investment.
Those three acts look similar on a screen. They are not interchangeable. The latest FAQ comments lean toward the third item and toward recordkeeping. The older letter and the older FAQ set speak to the first two. Merge the three and you invent a permission that staff did not write.
What You Should Actually Check
Public releases do not tell you how many firms filed notices, how many coins sit as collateral today, or the latest haircut on a named clearing program. The $100,000 walk-through is math, not a liquidation forecast. A live account needs its own records, product schedule, collateral mix, and contract language.
- Read the published FAQ text on tokenized permitted investments and blockchain records rather than a social summary.
- Check each firm’s accepted coins, valuation policy, and house haircuts.
- Read the clearinghouse eligible-asset list and its own discount per token.
- Look for public notices of reliance on the staff letter without assuming every intermediary participates.
- Compare token price and required margin at the same timestamp.
Did staff first allow bitcoin as derivatives collateral on one September afternoon? No. That update covered tokenized customer-fund investments and records. The earlier letter already described no-action conditions for certain customer crypto used as margin.
Is the bitcoin haircut always 20%? No. At least 20% shows up in certain non-stablecoin FCM calculations, with a same-asset exception. Clearinghouses pick their own initial-margin cuts.
Can a futures firm take customer cash and buy stablecoins as a Regulation 1.25 investment just because it can accept a qualifying stablecoin as margin? Staff has drawn that line before. Accepting a customer token and investing customer cash are different transactions.
Can the firm drop its own bitcoin into customer segregation as residual interest? Guidance that permits proprietary payment stablecoins for that purpose does not extend the same courtesy to proprietary bitcoin or ether. Customer-owned qualifying bitcoin is a different fact pattern.
Who Fills The Hole
The customer must keep the account at required margin under the terms that were signed. The intermediary must meet segregation and clearing duties and cannot raid another customer’s surplus to paper over that deficit. The firm’s own deposit into the segregated pool and the customer’s later wire can land on different clocks. Hope is not a settlement method.
I’ve found that people underestimate how quickly two marks can arrive together: a mark on the coin and a mark on the trade. One shrinks the security. The other raises the need. That is the whole story in one sentence, and it is why a falling token is more than a portfolio anecdote when it is sitting in a margin account.
This is educational analysis, not a recommendation to pledge, hold, or trade any asset. Figures move with each disclosure. Do the account-level work before you treat a staff letter like a product brochure.
A Longer Walk Through The Mechanics
Let me linger on the mechanics, because this is where most write-ups get thin. Margin is not a vibe. It is a comparison between what the account is required to hold and what the intermediary is allowed to count. The wallet balance is an input. It is not the output.
Fair market value comes first. Then the haircut. Then any concentration or eligibility filter. Then a comparison against initial and variation needs. Then house add-ons. Skip a step and the number on your phone looks kinder than the number on the firm’s blotter.
Variation is the quiet troublemaker. Collateral can look fine at the open and fail by the afternoon if the futures book is paying out losses while the token is also sliding. Intraday calls exist for a reason. Daily regulatory snapshots do not freeze the market in between.
Liquidity risk is the other quiet troublemaker. A coin that prints tight spreads on a calm Tuesday can gap when everyone wants the same exit. Haircuts try to pre-pay some of that pain. They cannot pre-pay all of it if the stress is larger than the model assumed last month.
Credit risk still hides inside “on-chain” packaging. Who is the custodian. Who has the keys. What happens if a transfer is delayed, disputed, or constrained by a compliance hold. A confirmed block is not the same thing as unencumbered, immediately usable value under a clearing rulebook.
Why Residual Interest Sounds Abstract Until It Is Not
Residual interest is the firm’s own money sitting in the customer segregated pool so the protected total is not short. When a customer is undermargined, that obligation can appear before the customer has wired a dollar. The later cure does not rewrite the earlier duty.
That is why staff language about counting qualifying crypto in those calculations matters. It changes how large the firm’s plug might need to be. It does not let the firm borrow a neighbor’s surplus. Customer A’s extra bitcoin is not a piggy bank for Customer B’s futures loss.
People sometimes ask whether proprietary bitcoin can play the same residual-interest role as a qualifying payment stablecoin. The published distinction is not subtle. Stablecoins under the stated conditions, yes in that residual-interest lane. Bitcoin and ether as the firm’s own property, no. Keep those lanes painted.
Policy Context Without The Mythology
Agency leaders talk about round-the-clock markets and tokenized collateral because the market is already trying to operate that way. Interest is not a repeal of ordinary margin tests. A clearinghouse still has to decide whether an asset’s credit, market, and liquidity profile belongs in its program.
Staff FAQs are not a substitute for a Commission rule rewrite. A no-action position says staff will not recommend enforcement if a firm stays inside the stated box. It does not erase segregation law. It does not force a clearinghouse to like every coin. It does not turn a blog post into an account agreement.
Chronology helps. Tokenized-collateral comments, digital-asset margin conditions, and later FAQ additions on wrappers and records arrived in layers. Each layer answers a different question. Stacking them into one “crypto is now cash” slogan is how people get surprised by a call.
Practical Habits That Age Better Than Slogans
If you actually use tokens as margin, build a habit of pairing two numbers at the same clock time: recognized collateral after haircut, and required margin after the latest mark. Do it before the move, not after. After is when everyone becomes a poet.
Keep a second habit. Read the house schedule, not only the venue schedule. The extra buffer is often where the pain lives. A public minimum is a floor for the clearing relationship. Your account may live on a higher floor.
Third habit. Separate the asset you like from the asset the program accepts. Affection is not eligibility. A beautiful tokenized wrapper on an ineligible underlying is still an ineligible underlying wearing nicer clothes.
Recognized value = market value × (1 − haircut)
Shortfall appears when recognized value + other eligible credit < required margin
Two marks can hit together: token mark and contract mark
None of that is romantic. Margin rarely is. The romantic version is the screenshot of a green wallet next to an open futures book. The adult version is the haircut table and the segregation report.
Limits You Should Leave On The Page
This piece does not estimate liquidation volume. It does not rank venues. It does not claim a single industry haircut. It does not treat a staff letter as a personal invitation to lever a coin. Those claims would be louder. They would also be worse.
What it does claim is smaller and, I think, more useful. Customer ownership and recognized value are not the same thing. Intermediary math and clearinghouse math are not the same thing. House inventory charges are a third thing. A falling price hits the first book immediately and can force action on the other two.
If you take one sentence with you, take this one. A discount applied to yesterday’s price will not protect you from today’s price. The ratio follows the market. The call follows the ratio. The rest is paperwork, timing, and whether anyone else in the chain still wants that token when you need it most.