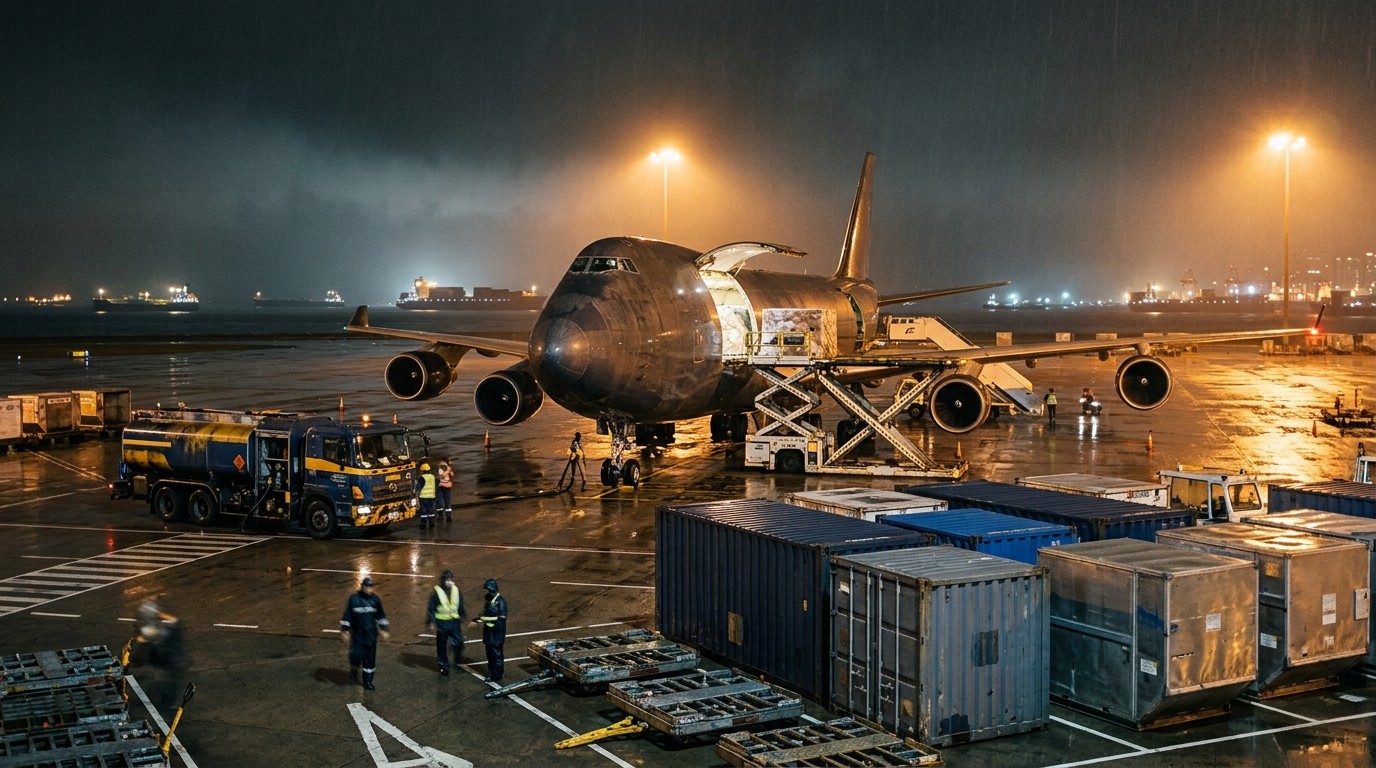

I keep thinking about a conversation that started with a simple question about aviation fuel and ended somewhere much darker. Sitting next to a cargo pilot on a long-haul hop, I asked what higher kerosene prices were doing to the express networks. He did not give me a tidy number. He talked about closed skies, extra hours in the air, thinner payloads, and customers who still expect the box to arrive tomorrow. That is the quiet story behind the latest freight shock. The world’s big integrators like to sell themselves as living gauges of global demand. Right now they are also measuring what it costs to keep a worldwide air web running when two of the three main east-west corridors are effectively broken.
Why Express Networks Suddenly Look Fragile
The short version is ugly. Energy disruption in the Gulf collided with airspace already locked by the war in Ukraine and by sanctions. The result is not a neat spike that fades in a week. It is a structural tax on speed. FedEx and UPS have so far survived by sliding that tax onto shippers. The cost does not vanish. It travels down the chain and shows up in the inflation numbers policymakers are trying to wrestle back into a box.
I’ve found that people still treat parcel rates as a rounding error. They are, until they are not. When jet fuel jumps, diesel follows, schedules slip, and every extra minute in the air burns money. Then the surcharge table gets rewritten. Then a retailer shrugs and lifts the delivered price by a few cents. Multiply that by millions of shipments and you have a political problem wearing a logistics uniform.
The Fuel Shock That Hit First
The trigger was the energy crisis around the Strait of Hormuz. Energy agencies have called the near-total squeeze on that chokepoint one of the largest supply disruptions the oil market has ever absorbed. Brent raced toward the high teens above one hundred dollars in late March, slumped toward seventy by early July, then climbed back over one hundred after fresh attacks on shipping and infrastructure. By early September it was again near one hundred nine before easing toward ninety-nine on talk of negotiations. Even after that pullback, crude is still up on the order of sixty percent for the year. That is not a blip. That is a new floor with a very jumpy ceiling.
Jet fuel moved even harder than crude because refining margins widened. Industry weekly readings put the global average near one hundred ninety-five dollars a barrel after a single-week jump of more than seven percent. U.S. Gulf Coast kerosene-type jet fuel has averaged well above four dollars a gallon in September. Ground networks are not insulated either. The national diesel average has printed record territory around six dollars and thirty-one cents a gallon. If you run trucks to feed airplanes, you get hit twice.
For the largest cargo airline by fleet count, this lands straight on the cost line. In the quarter ended May 31, the fuel bill jumped sixty-six percent, from eight hundred sixty-four million dollars to one point four three billion. That is the kind of move that used to be reserved for crisis footnotes. Now it is just another line in the 10-Q.
Fuel is no longer a background cost. It is the weather system the whole network has to fly through.
Closed Skies Over Russia And The Gulf
Fuel would have been painful on its own. Airspace made it worse. After 2022, Russian skies were already closed to most U.S. and European carriers. Europe-Asia flights added hours and burned more kerosene. Carriers that still enjoy Russian overflight kept a lasting edge: Chinese, Turkish, Indian, and Gulf operators could sell faster, cheaper east-west lift. That advantage did not fade. It calcified.
Then the Gulf tightened as well. In late February, a cluster of Middle Eastern states closed or restricted airspace. Traffic got shoved through the Caucasus corridor between the Black Sea and the Caspian, a strip that narrows to about one hundred miles. Capacity estimates suggested sixteen to eighteen percent of global air cargo lift vanished with almost no warning. Early rate prints from South Asia into North America and Europe jumped around fifty percent. That is not a seasonal wrinkle. That is a sudden hole in the map.
By mid-July, Gulf carriers had clawed back most of their schedules by swinging south over Saudi Arabia and Egypt. The penalty was thirty to sixty extra minutes on Europe-Asia services. Longer flights mean more fuel, lower payloads, more crew hours, and worse aircraft utilization. Forwarders reported that looping around the usual Gulf hubs cut reliability and lifted operating costs. Freight to and from the region itself sagged. Middle East and Africa exports were down about twenty-four percent year on year. Speed, it turns out, is a geography product.
- Russian overflight remains closed to many Western carriers, stretching Europe-Asia legs.
- Gulf restrictions funneled traffic into a thin Caucasus corridor.
- Reroutes add time, fuel burn, and crew cost even after schedules recover.
- Regional export volumes from the Middle East and Africa dropped sharply.
How The Integrators Absorbed The Blow
Here the plot gets less simple than the headlines. Surcharges have protected the big integrators far better than passenger airlines or asset-light truckers. A senior commercial executive said in March that the fuel surcharge was doing its job and would keep the company profitable. I believe that, up to a point. The mechanism works until customers start shopping for slower, cheaper options.
The revenue tape supports the first half of that claim. In the March-May quarter, one major integrator’s revenue rose thirteen percent to twenty-five billion dollars, with war-related fuel surcharges adding about five percentage points. U.S. ground fuel surcharge levels sat near twenty-six percent in mid-August. The other giant lifted full-year 2026 guidance toward ninety-one point two billion dollars in revenue and about seven dollars and twenty-two cents in adjusted earnings per share. On paper, that looks like resilience. Under the hood, it looks like pass-through.
The bruise shows up in margins. One firm beat estimates last quarter even as operating income fell nearly twenty-two percent year over year. The math is blunt. The surcharge resets on a lag. When fuel spikes, revenue and costs rise by similar dollar amounts, which shrinks the margin percentage even if cash profit holds up. Shares have slipped over the last month and the last quarter, though they remain sharply higher over twelve months. Markets can live with a surcharge machine. They get twitchy when volumes might crack.
The broader freight complex flashed a warning this month. A large truckload name said third-quarter earnings would drop five to ten percent from the prior quarter, pointing to at least ten million dollars in extra fuel costs and twenty-five million in driver recruiting and bonus expense. Package names sold off with the truckers. That is how contagion looks in this sector: diesel first, then sentiment.
Who Actually Pays The Bill
On the evidence so far, shippers are eating most of it. Finance chiefs have called the net profit hit from surcharges modest. Operating teams insist those fees are not a material driver of adjusted operating income. Critics still ask why the percentages climbed so fast. For comparison, the postal service imposed its first surcharge in late April at eight percent on most packages. Independent checks have not proved an industry-wide gouge, but they have found cases where some transport firms collect more in surcharges than they spend on fuel. That gap will attract lawyers if this drags on.
From shippers, the cost slides into shelf prices. That is where a carrier problem becomes everybody’s problem. I’ve watched this movie in smaller versions after hurricanes and pipeline outages. The first week is a logistics story. The sixth week is an inflation story.
A surcharge that looks technical on a rate card becomes a price tag the moment a retailer refuses to swallow it.
What The Inflation Numbers Are Already Saying
Official interim outlooks now project G20 headline inflation rising to about four point one percent in 2026 before easing toward three point six percent in 2027. Advanced-economy core inflation is seen cooling from two point seven percent to two point five percent. That split matters. This is still mainly an energy shock lifting the headline, not yet a broad wage-price spiral. Analysts credit government support, input substitution, non-Gulf supply, and reserve drawdowns with limiting the damage. Fair enough. Limits are not the same thing as immunity.
In the United States, August consumer prices ran about three point four percent year over year, while core sat near two point four percent, the softest since early 2021. Gasoline alone accounted for more than a third of the monthly increase. Policymakers still refused to shrug. Rates moved to three point seven five to four percent in mid-September, the first hike since 2023, with officials pointing to the energy shock and hinting at least one more move this year. That is the political translation of a tanker map.
| Pressure Point | What Moved | Why It Matters |
| Crude benchmark | Sharp 2026 swings, still far above last year | Sets the tone for jet and diesel |
| Jet fuel | Outpaced crude as crack spreads widened | Direct hit to air networks |
| Diesel | Record retail averages | Feeds ground networks and food logistics |
| Airspace | Russia closed, Gulf constrained | Longer routes, lower utilization |
| Surcharges | High double-digit add-ons | Protects carriers, pressures shippers |
How Freight Costs Reach The Checkout
Express surcharges are real, but they are a secondary channel. Shipping is usually a thin slice of a finished good’s retail price, so parcel fees add friction at the margin rather than driving the whole index. The same jet fuel shows up much more clearly in passenger airfares, which have jumped more than twenty-three percent since August 2025. That is energy wearing a ticket stub.
Food is the more dangerous pipe. Diesel, packaging, and fertilizer matter more than overnight envelopes. A lot of fertilizer still moves through Gulf waters, which keeps global food prices on a short leash. One inflation watcher who usually treats food and energy as mean-reverting now sounds less sure, because energy is leaking into trucking and packaging. That is the sentence central bankers hate.
The spillover into core inflation is the fear. Economists warn that fresh rises in oil, gasoline, and diesel can migrate into other prices and into expectations. So far median measures look relatively tame, and part of the rise in services inflation is airfares, which is really energy in disguise. The pain is not evenly spread. Energy- and food-importing emerging economies are far more exposed than the United States. In the Philippines, diesel has printed above one hundred forty pesos a liter, roughly ten dollars and seventy-five cents a gallon. Weak currencies and heavier food-and-fuel weights in local indexes amplify the shock. That is how a strait becomes a kitchen-table event.
Duration Is The Whole Game
Scenario work published earlier this year frames the stakes with uncomfortable clarity. If Gulf supply recovers from the third quarter of 2026, the shock fades in 2027. If disruption lasts into late 2027, growth gets weaker and inflation stays hotter, adding roughly four tenths of a point in 2026 and about one point three points in 2027. Baseline forecasts still assume energy prices ease next year. They also list prolonged Middle East export disruptions and a strong El Niño as key downside risks. With Brent still near ninety-nine dollars and a major Saudi east-west pipeline shut since September 11, that baseline looks optimistic. Perhaps the most interesting aspect is how quickly official language shifted from temporary disruption to duration risk.
A long disruption would also change the carriers’ position. Their pass-through model works only while customers accept it. The longer surcharges sit above twenty-five percent, the more small and mid-size shippers will drop from express to ground, from air to ocean, or simply ship less. Company outlooks have assumed no further geopolitical hits and have admitted that soaring fuel costs could weigh on results if customers pull back. The Russia-overflight disadvantage does not disappear when oil falls. And the gap between surcharge revenue and actual fuel spend could become a political and legal target. That last point is easy to ignore in week six. It is harder to ignore in month eighteen.
What A Structurally Costlier Network Looks Like
Wars and sanctions have made a global express network more expensive in three stubborn ways: longer routes, fewer usable hubs, and fuel that stays high while swinging without manners. So far the giants have converted most of that cost into surcharge revenue. Their pain shows up as margin compression rather than losses. Downstream, the same dollars add to the energy-led inflation that has already pushed the central bank back into hiking.
In my experience, logistics firms can live with expensive fuel if volumes hold. They cannot live with expensive fuel plus a quiet customer strike. That is why peak season commentary will matter more than another week of crude prints. If jet fuel lingers near one hundred ninety dollars a barrel through the heavy shipping window, the question stops being whether the integrators can pass costs on. It becomes whether their customers, and the consumers behind them, can keep absorbing them.
- Watch September consumer prices due in mid-October for the next energy imprint.
- Listen for volume language, not just surcharge recovery, on the next express earnings call.
- Track whether shippers trade down from air to ocean as peak season arrives.
- Follow diesel and fertilizer as closely as jet fuel if you care about food prices.
- Treat airspace access as a lasting competitive factor, not a temporary detour.
The Customer Math Nobody Wants To Do
Imagine a mid-size electronics seller that used to budget a predictable express line. A twenty-six percent ground fuel add-on plus longer transit on the international legs does not just raise landed cost. It wrecks promotion calendars. Holiday inventory that used to fly now looks expensive enough to wait on the water. That wait creates stockouts, then panic restocks, then another burst of air demand at even worse rates. The loop is familiar to anyone who lived through the last freight boom. The difference this time is that the constraint is political geography, not a shortage of boxes.
Smaller shippers feel it first because they lack contract leverage. They cannot threaten to pull a national account. They can only downgrade service or raise prices and hope the shopper does not notice. Some will notice. Some will not. The ones who notice start the substitution chain that eventually shows up as weaker express tonnage. That is the lag the market is trying to price.
I’ve found that investors still want a clean binary: either the surcharge works or volumes collapse. Reality is messier. You can get both at once. Revenue holds because fees are high. Operating margin slips because costs rose by almost the same dollars. Shares wobble because the next quarter depends on whether peak season still looks like peak season. None of that is mysterious. It is just uncomfortable.
Why Ground Networks Are Not A Clean Escape Hatch
There is a tempting story that shippers will simply dump air and live on trucks and ships. Some will. Many already have. But ground is not a sanctuary when diesel is printing records and driver pay is climbing to keep seats filled. Ocean is not a sanctuary when schedules are unreliable and insurance on certain sea lanes is a negotiation, not a line item. The express product exists because somebody needs certainty. Take the certainty away and the product still exists. It just costs more and arrives later, which is the worst of both worlds.
That is why I keep coming back to utilization. An airplane that flies longer routes with a lighter payload is a more expensive factory. Crews time out. Maintenance intervals compress in calendar terms even if flight-hour math looks similar. Hubs that used to sit in the sweet spot of the network suddenly sit on the wrong side of a closed FIR. You can redraw a map in a planning meeting. You cannot redraw it overnight in the real world without burning cash.
Emerging Markets Carry A Heavier Load
Rich-world indexes can hide a lot of pain in services and shelter. Importing economies cannot. When fuel and food take a larger share of the household basket, a Gulf disruption is not an abstract supply-chain essay. It is a monthly budget event. Currency weakness then multiplies the local price of dollar-priced energy. Policymakers in those markets face an uglier mix: imported inflation, weaker growth, and less room to cushion households.
That unevenness will shape trade flows too. Buyers in stressed markets delay restocking. Exporters in those same markets lose lift as regional cargo demand slumps. The air network then looks even more lopsided, with capacity chasing the corridors that still pay. If you only watch U.S. parcel volumes, you will miss that rotation.
What To Watch Before Peak Season Hardens The Story
The next markers are ordinary and therefore easy to underestimate. The mid-October consumer price print will show whether gasoline is still doing the heavy lifting. Express commentary on fiscal first-quarter 2027 results will show whether surcharge recovery is still covering the fuel line and whether volumes are holding. Neither print will settle the duration question. Together they will tell you if the pass-through machine is still socially acceptable.
If talks ease the tanker risk, jet fuel can fall faster than the political narrative. If another strike on infrastructure hits, the Caucasus corridor becomes a parking lot with wings. There is not much room between those outcomes. That is why this story feels unfinished even after thousands of words of rate tables and outlook language.
So where does that leave a reader who does not run a cargo airline? It leaves you with a simple, slightly rude truth. The express giants are not broken. They are expensive in a new way. Their customers are not broken either. They are shopping for cheaper speed. Inflation is not running away in the core just yet. It is being fed by energy in enough places that policymakers already chose to hike. Duration decides whether this stays a freight footnote or becomes the next stubborn layer in the price level. I do not like how much of that answer still sits in a stretch of water most shoppers could not find on a map. That, unfortunately, is the point.