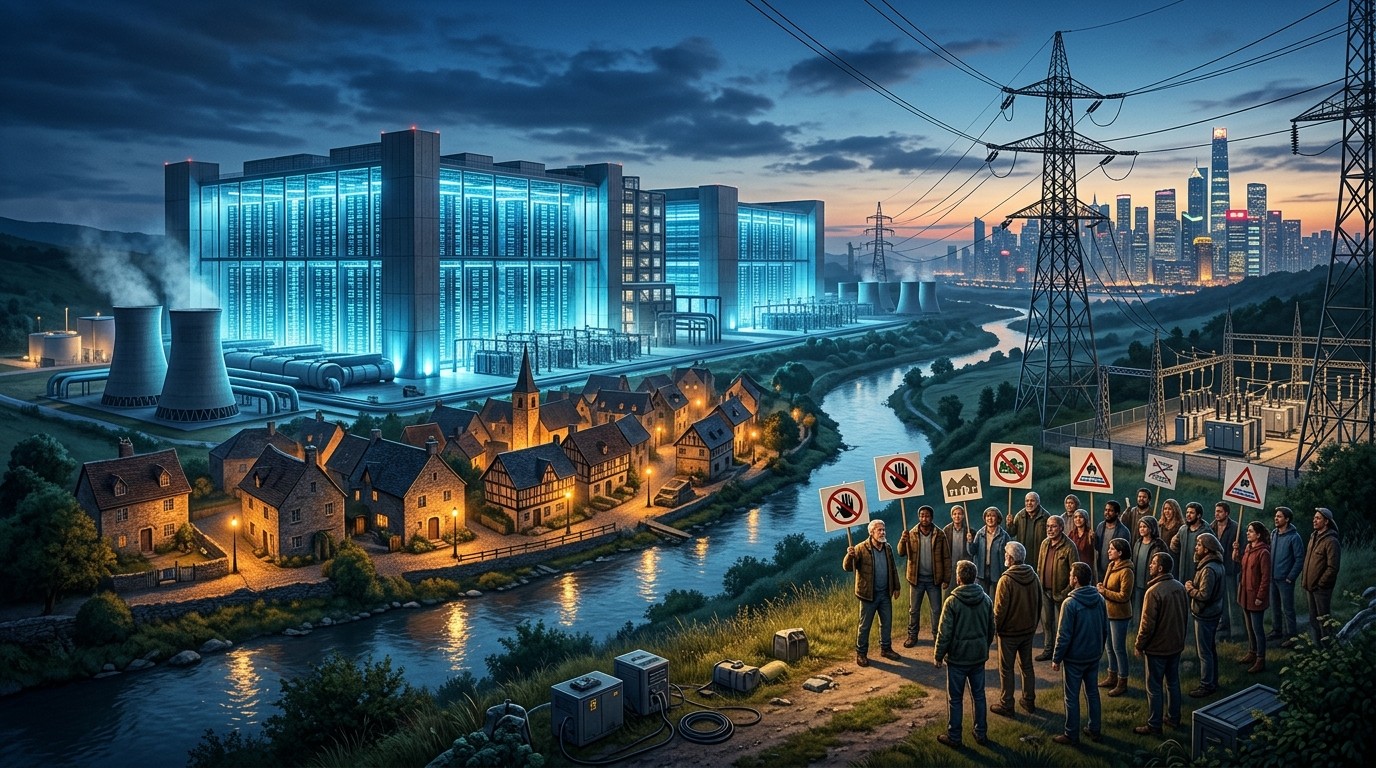

I kept a scrap of a planning notice on my desk for weeks, the kind of dull municipal paper most of us bin without reading. A neighbour had circled one line in pen: a proposed server hall, roughly the footprint of a retail park, asking for a grid connection big enough to power a small town. No brand name. No ribbon-cutting language. Just megawatts, cooling, and a date for a hearing that already looked oversubscribed. That scrap is why the current fight feels less like a tech story and more like a land story. The data center backlash that started as a local American quarrel is now turning up in European town halls and Asian city districts, and investors who still treat permits as a formality are about to learn how expensive a delayed megawatt can be.
Perhaps the most interesting aspect is how ordinary the objections sound. People are not debating model weights. They are asking who pays for the extra substation, whether the river can spare the cooling water, and why a warehouse that employs a handful of technicians should jump the queue ahead of homes and factories. Those questions travel well. They do not need a shared language.
Why The American Fight Is Now A Preview, Not An Exception
For a while it was easy to file the noise under American zoning theatre. A county board says no. A utility shrugs. A developer redraws the map and tries the next county. That pattern still happens. What has changed is the audience. Communities in denser countries watched the same buildout arrive with fewer empty fields and higher power prices, and they copied the script.
Industry monitors tracking European projects have counted more than seventy schemes rejected or restricted in a single early-year window, a pace that already outran the whole of the prior year. Separate research puts the value of European investments touched by delays and cancellations near $42 billion, against roughly $77 billion on the American side. Those are not rounding errors. They are a second balance sheet sitting beside the capital-expenditure slides.
I have found that the numbers land differently once you stop treating them as a scoreboard. A delayed campus is not a clean miss. It is sunk site work, lawyers, interconnection studies, and a story you then have to retell to the next planning committee. An energy-transition scholar put the risk in blunt terms: this kind of pushback can be the straw that breaks the camel’s back. Not because artificial intelligence demand vanished. Because the physical layer underneath it is suddenly political.
The gains of AI are very diffused. The costs of the buildings that train and serve it are not.
Energy-transition researcher, paraphrased from public remarks
That diffusion is the heart of the local complaint. A chatbot used in another country does not lower a household bill in the county that hosts the racks. A training run does not hire the mechanic who lives next door. Residents see a large, quiet building, a spike in applications for power, and a promise of jobs that rarely matches the scale of the land take. In my experience, once that gap is visible, technical briefings stop calming the room.
What People Are Actually Objecting To
Strip away the slogans and the objections cluster around four practical things. Power. Water. Land. And a fuzzy claim about economic value per megawatt that nobody has agreed how to measure.
- Electricity is the loudest item. Hyperscale halls can request connections measured in hundreds of megawatts, sometimes more, and grids built for homes and factories were not designed for that queue.
- Water sits just behind it. Evaporative cooling, backup systems, and the sheer heat leaving the racks make residents ask what happens in a dry summer.
- Land is the visible insult. A campus can look, as one observer put it, like a giant ghost warehouse: sealed, low-staff, and oddly indifferent to the street it faces.
- Jobs are the promise that keeps failing the smell test. Permanent headcount is often modest next to construction peaks, and there is still no shared method for valuing a site per megawatt.
Add electricity prices to that list and you get the political fuel. Households already annoyed by bills do not enjoy hearing that a new class of customer may reshape the local load. Whether the data center truly raises retail rates is a live argument, full of tariffs, subsidies, and who pays for network upgrades. The argument does not need to be settled for it to swing a vote.
A Useful Way To Read The Scale
Think of a single large campus as a new industrial estate that never opens a shopfront. It draws power like a factory, employs like a depot, and occupies land like a logistics park. The mismatch is what makes neighbours suspicious. Factories at least have shift changes you can see.
| Local worry | What residents hear | What developers answer | Where the gap remains |
| Power draw | Our grid will be captured | We fund upgrades and buy clean supply | Queue position and who pays first |
| Water | Summers are already tight | Closed-loop and recycled systems | Drought years and discharge rules |
| Jobs | A handful of technicians | Construction plus indirect roles | No standard value per megawatt |
| Prices | Bills will rise | Large users can lower unit network cost | Tariff design and political trust |
| Land | Sealed boxes, little street life | Security requires a closed site | Design, setbacks, community benefit |
That table is not a verdict. It is a map of the argument. Projects that treat only the developer column as real tend to meet the resident column later, in court.
Europe Feels The Squeeze First Because It Has Less Spare Room
Europe is not short of ambition. Governments want domestic compute, cloud capacity, and a seat in the artificial intelligence race. The geography argues back. Countries are denser. Spare industrial land is scarcer. Wholesale power is often pricier than in markets that still burn cheap gas or sit on vast wind resources with room to spare. And a large share of the operators proposing the biggest halls are American firms, which gives local campaigns an easy frame: someone else’s profits, our substations.
An academic who studies the energy shift put it plainly enough. Denser population plus foreign operators can make the backlash land harder. I think that is right, with one caveat. Density alone does not create a revolt. Density plus a visible queue-jump does.
Scotland paused planning approvals for new hyperscale halls after campaigners urged ministers not to repeat what they called the cautionary tale of Ireland. Ireland’s data center load grew so heavy that new connections were effectively frozen. Whether every detail of that tale travels cleanly across the Irish Sea is beside the point. The phrase stuck. Once a government hears “do not become the next moratorium,” officials reach for the pause button faster than they reach for a ribbon.
The Nordic Bet Meets A Queue
For years the Nordics looked like the polite answer to every siting problem. Cool air. Plenty of land. A power mix heavy on renewables. Investors wrote the pitch almost from memory. Then the applications arrived in a surge, and the grid, which is a physical object and not a slogan, started to look finite.
Denmark responded with an emergency law that can push data centers toward the back of the line for grid applications. That is a quiet sentence with a loud balance-sheet effect. A project whose entire advantage was cheap, timely power loses the advantage the moment it is told to wait. Spain, in the same season, floated rules that would require centers to source about 80 percent of their electricity from renewables. Sensible on a climate slide. Awkward if your interconnection date and your renewable contract do not land in the same year.
Britain has its own stalled files. Local objections there often braid water, bills, and the sheer acreage of a proposal into one hearing. I sat through enough infrastructure meetings, in another life covering ports and warehouses, to recognise the rhythm. The first session is technical. The third is about trust. By the fifth, someone asks who the building is really for.
- A developer files for land and a grid study, often before the politics are mapped.
- Neighbours organise around water, noise, backup generators, or bills.
- A council delays, conditions, or refuses.
- The fight moves to a regulator, a court, or a national parliament.
- Capital already spent on the path to a permit becomes a sunk cost if the permit never arrives.
European monitors say the pushback has snowballed from town halls into courts, regulators, and parliaments. That ladder matters. A parish objection is slow. A national rule is structural. Investors who price only the first rung misread the second.
Ireland As The Story Other Countries Tell Themselves
Ireland did not set out to become a parable. It set out to host digital infrastructure, and it succeeded, until the power system tapped the glass. A moratorium on new connections is the kind of policy other campaigners can point at without needing a white paper. “Look what happened there” is a complete sentence in a planning meeting.
Is the comparison always fair? Not really. Grids differ. So do climates, tax regimes, and how much of the national load already sits inside server halls. Fairness is not what travels. The cautionary tale travels. Scotland’s pause is evidence that the tale already has passengers.
A community’s ability to derail a ten-billion-dollar plan is quite powerful.
Restructuring adviser speaking on project risk
That line should be taped inside every investment memo that still treats siting as a Gantt-chart item. Ten billion is not a metaphor. It is the order of magnitude some campuses now imply once land, power gear, buildings, and fit-out are added up. A residents’ association does not need to match that capital. It needs a procedural hook and enough patience to use it.
Asia Is Not A Free Pass Either
South Korea sits in an awkward, lucrative spot. It is home to the memory giants that feed the artificial intelligence supply chain, and its national government has named AI data centers as one of three flagship investment themes, alongside semiconductors and physical AI. That is the warm half of the policy weather. The cold half is local.
In the Geumcheon district of southwestern Seoul, residents have asked authorities to revoke a building permit and stop a center going up near their homes. Officials later outlined a consent rule: a majority of people living within 200 metres of a proposed site would need to agree, alongside a three-stage review meant to mediate disputes. Residents had already been gathering outside the local government office on weekday mornings. By mid-August the demonstrations had run for 172 days, according to local reporting. One hundred and seventy-two weekday mornings is not a flash mob. It is a habit.
Further south, in Gwacheon, a council member proposed an ordinance aimed at people living beside halls that run around the clock, including the fire risk tied to backup batteries. That detail is easy to skip and unwise to skip. Lithium-ion backup systems are ordinary engineering. They are also ordinary fear once a neighbour learns the building never sleeps.
A managing director who advises on these projects described the mood outside the United States as a kind of hot and cold at country level. National strategies pull projects in. Local rules push them back. The push and pull is the investment problem, not a footnote to it. America’s business-friendly setting has historically made pushback easier to outlast. Europe and parts of Asia do not offer the same default.
The Battery, The Night Shift, And The Neighbour
Round-the-clock operation sounds like a virtue in a prospectus. Uptime. Redundancy. A building that does not take holidays. On a residential street it sounds like generators, security lights, truck movements, and a chemical risk nobody asked to live beside. The Gwacheon proposal is a reminder that opposition is getting specific. Campaigners are no longer only saying “not here.” They are naming failure modes: thermal runaway in backup batteries, night-time noise, the absence of a buffer zone.
Specific objections are harder to wave away with a jobs leaflet. They demand engineering answers, setbacks, and sometimes a different plot of land. Each of those answers costs money and months.
Should Investors Actually Worry?
Demand is not the weak point. The buildout tied to artificial intelligence still shows little sign of cooling, even as communities heat up. Chip orders, cloud commitments, and national strategies all point the same direction. The weak point is permission, power, and the time between a press release and a live megawatt.
Most capital expenditure lands after permits are in hand. That sentence comforts people who have not priced the path to the permit. Operators spend heavily to reach that line: options on land, studies, legal teams, early equipment deposits, local relations. Pull out before a shovel hits soil and a slice of that money is already gone. A restructuring adviser was frank about it. There is loss if the permits never come, even when the concrete never does.
I would rather underwrite that loss than pretend siting risk is a communications problem. Communications can lower the temperature. They cannot invent a spare circuit or a willing neighbourhood.
A rough way to think about early-stage exposure:
  Land options and studies     — spent before a vote
  Grid applications            — queued, not guaranteed
  Community agreements         — slow, sometimes required
  Equipment deposits           — painful to unwind
  Permit denial                — turns the above into a write-down
None of those lines belong in a footnote labelled “execution.” They are the execution.
Operators Say The Black Box Is Gone
For a long time this industry hid in plain sight. A chief executive of a data center operator described the old posture almost fondly. They were an unknown layer of the economy, a black box, a building with stuff inside that nobody understood. Now they are one of the fundamental layers driving the economy, and everybody knows where the buildings are. There is, as he put it, no hiding behind this.
That visibility cuts both ways. It justifies higher multiples when the demand story is clean. It also means every new hall is a public object. A growth executive at a large colocation firm, speaking about European markets, said communities wanting to understand what is being built nearby is understandable. She did not see the mood as a structural cap on growth, but she did say the policy environment is genuinely tightening in some markets. Both sentences can be true. Growth can continue while the cost of growth rises.
We used to be a black box. Now everybody knows where the buildings are, so there is no hiding.
Data center operator, on the end of anonymity
I keep coming back to that shift. Anonymity was a subsidy. It is gone. The sector will have to buy legitimacy the slow way: design, local benefit, credible power plans, and fewer surprises at the hearing.
Who Foots The Energy Bill Is The Argument Under The Argument
Ask ten specialists who pays for the extra wires and you will get a seminar. Large users can, in theory, spread fixed network costs and fund upgrades that smaller customers could not. They can also lock in capacity that households then experience as scarcity, or as higher bills if tariffs are drawn badly. The honest version is that the answer depends on the rulebook, and the rulebook is being rewritten while the projects are in flight.
Spain’s renewable-sourcing idea and Denmark’s queue law are different tools aimed at the same anxiety. One tries to green the load. The other tries to stop the load from crowding out everyone else. Britain and Scotland are experimenting with delay. South Korea is experimenting with neighbour consent. None of these is a final architecture. All of them change the clock.
Perhaps investors should stop asking whether backlash “kills” the theme and start asking which jurisdictions still have a clock they can underwrite. A project with a credible interconnection date, a water plan that survives a dry year, and a political sponsor who has already taken the local heat is a different asset from a slide that says “Europe AI demand.”
Jobs, Ghost Warehouses, And The Value Nobody Can Quote
There is still no settled way to project a center’s economic value per megawatt. That absence is doing quiet damage. Developers talk about construction wages, tax base, and indirect cloud jobs somewhere downstream. Residents count the permanent badges on the security gate. Both counts can be accurate and still fail to meet. Without a shared yardstick, every hearing becomes a clash of anecdotes.
The ghost-warehouse image sticks because it is visual. Sealed facades. Few windows. A car park that never fills the way a hospital car park fills. You can explain security protocols until the lights go out and the image remains. Better architecture helps at the margin. Community funds help at the margin. Neither replaces a straight answer on headcount.
- Construction employment is real and temporary.
- Permanent technical roles are real and small relative to power draw.
- Indirect jobs in software and services are real and mostly elsewhere.
- Tax receipts depend on abatements that campaigns increasingly attack.
If I were writing the local benefit case, I would lead with the grid upgrades the town keeps after the project, not with a headcount that will not survive a leaflet. People can verify a substation. They cannot verify a multiplier.
Water Is The Issue That Escalates Fastest
Power arguments can hide inside tariffs. Water arguments cannot. A river is either lower or it is not. Farmers, anglers, and households share a vocabulary here that does not require an engineering degree. Centers that switch to air cooling or closed loops reduce the flashpoint, but they do not delete it, especially where backup systems and humidification still draw supply, or where the power that replaces water-intensive cooling simply moves the environmental bill onto the grid.
In dry regions the question is existential for the project. In wet regions it is still symbolic. Symbolism wins hearings more often than hydrology does. A developer who arrives with a one-page water balance and a named drought plan will still face sceptics. A developer who arrives without one will face a campaign.
Regulation Is Catching The Mood, Not Leading It
Look at the sequence and the politics are obvious. Applications surge. Neighbours organise. Then a ministry discovers an emergency law, a renewable quota, a consent radius, a planning pause. The rule follows the rally, which means the next rule is hard to forecast from last year’s statute book.
That lag is why country-level “hot and cold” is such a useful phrase. A national AI strategy can be hot in June and cold by the time a district council meets in November. Korea’s dual track, national acceleration beside Seoul-area resistance, is the cleanest current example. It will not be the last.
For portfolio construction, the practical translation is boring and useful. Do not underwrite a region. Underwrite a node: a utility territory, a water basin, a planning authority with a recent voting record. The node is where the project lives. The region is where the press release lives.
What A Tougher Siting Market Does To Returns
Higher friction does not automatically mean lower returns. Scarcity of permitted megawatts can support pricing for the halls that do get built. Colocation landlords with land and power already in hand may find the backlash is a moat. Developers who still need the permit wear the risk. The split inside the sector matters more than the sector label.
Watch three spreads, not one headline.
- The spread between announced capacity and permitted capacity.
- The spread between permitted capacity and energised capacity.
- The spread between energised capacity and capacity that has a paying tenant at a price that covers the new political cost.
Announcements are cheap. Electrons are not. A landlord who can show the third line is telling a different story from a sponsor who is still collecting options on fields.
A Field Guide For The Next Hearing
If you cover these projects, or finance them, the hearing is the document. I have started reading them the way I used to read bond prospectuses, looking for the clause that actually bites.
- Who speaks first, the utility or the developer? If the utility is cautious, believe the utility.
- Is water framed as consumption, discharge, or both?
- Are backup batteries and generators named, or buried in an appendix?
- Does the jobs figure distinguish construction from permanent roles?
- Is there a consent radius, a buffer, or a benefit fund with a number attached?
- Has a nearby jurisdiction already paused, queued, or conditioned similar halls?
None of this is glamorous. It is how you avoid discovering the politics on the day the financing closes.
The American Template, Copied And Edited
American counties wrote the first draft: moratoriums, noise ordinances, setback rules, fights over who funds the new line. Europe is editing that draft for denser maps and higher prices. Parts of Asia are editing it again for residential adjacency and national industrial policy that does not want to look anti-technology. The family resemblance is obvious. The local edits are where money is made or lost.
A business-friendly default, the kind advisers still associate with much of the United States, lets a sponsor outlast a campaign more often than not. Outlasting is not the same as cheap. Even a won permit can arrive with conditions that reshape the power contract. In tighter jurisdictions, outlasting may not be on offer at all. Scotland’s pause and Denmark’s queue are not invitations to wait six months and resubmit the same pack.
National Ambition Versus The Street Outside The Office
Governments want the compute. Residents want the street to stay recognisable. Both positions are coherent, which is why the conflict will not resolve with a single white paper. Korea naming data centers as a flagship project does not cancel 172 mornings of protest. A European competitiveness speech does not cancel a Scottish pause. The tension is the story, and it is widening rather than closing.
I do not think demand blinks first. Training clusters and inference halls are being ordered because customers are already paying for the output. What blinks is the schedule, and schedules are where equity stories go to be revised. A year of delay on a power-constrained site is not a rounding difference in a model that assumed straight-line energisation.
Simple delay math investors actually use:
lost year ≈ carrying cost + missed lease start + repriced equipment
political delay ≈ all of the above + a chance the site is abandoned
Abandonment is the tail. Carrying cost is the body of the distribution. Most damaged projects will not die. They will arrive later, cost more, and earn their keep in a tighter window.
Design, Distance, And The 200-Metre Rule
Consent inside a fixed radius, the idea floated in Seoul, is a fascinating piece of political engineering. It turns a diffuse planning fight into a countable neighbourhood vote. Developers will hate the uncertainty. Residents will like the leverage. If the model spreads, site selection changes overnight. A field beside a housing estate becomes unfinanceable. A field beside a substation and a motorway becomes the only file a credit committee will read.
Distance is a design choice as much as a political one. Setbacks, berms, quieter cooling, and battery rooms placed away from the fence line will not charm every campaign. They will remove the easiest photographs from the leaflet. In a fight this visual, that is not nothing.
Renewables Quotas Are Not A Free Pass
Requiring a center to buy most of its power from renewables sounds like alignment. It can also stack one scarce resource on top of another. Renewable projects have their own queues, their own local opposition, and their own grid studies. A rule that says 80 percent clean supply does not conjure the turbines. It conjures a second permitting story that has to close before the first one can honestly claim to be green.
Matching matters. A renewable contract that delivers in 2031 does not cool a hall that wanted to open in 2028. Investors who tick the green box without reading the delivery year are marking their own homework.
What “Hot And Cold” Means In A Portfolio
Hot: national subsidies, fast-track rhetoric, a minister who wants a photo with a server rack. Cold: a utility that has stopped offering dates, a council with a fresh refusal on the books, a campaign that has learned the appeal timetable. The same country can be both in the same quarter. That is uncomfortable for thematic funds that bought the map, not the node.
A practical filter I would actually use:
- Recent refusals in the same planning authority.
- Public statements from the grid operator on queue reform.
- Water-basin stress in official drought plans, not in marketing.
- Whether local consent is advisory or binding.
- How much capital is already sunk relative to the chance of a clean permit.
If three of those flash amber, the discount rate is wrong, however strong the tenant conversation looks.
The Misunderstanding Operators Complain About
Operators argue, with some justice, that the public still misunderstands the sector. Halls are not all the same. A small colocation site serving a city’s banks is not a training campus drawing the load of a steelworks. Efficiency has improved. Some sites recycle heat into district networks. Security rules, not arrogance, explain the blank walls.
The misunderstanding is real. It is also incomplete as a defence. Scale changed the politics. When the buildings were a black box, misunderstanding was cheap. Now that they sit on the critical path of an investment boom, misunderstanding becomes a veto. Education campaigns help. They do not replace a smaller draw on a stressed feeder.
Where The Next Flashpoints Are Likely
I am not in the prediction business, but patterns are allowed. Places with a recent surge in applications, a visible residential edge, and a grid operator already muttering about queues are the obvious candidates. The Nordics taught investors that renewables and cool air are not a political force field. Korea is teaching them that a national champion strategy does not silence a district. Britain is teaching them that a stalled file can sit stalled.
Secondary effects are worth a look too. If primary hubs tighten, demand leaks to the edge of established markets, smaller cities, and countries that still answer the phone. That leak creates the next backlash, because the edge is often where planning departments are smaller and rumours travel faster. The fight does not disappear when a project moves. It relocates.
A Note On Severe Weather And Other Piled-On Risks
Community opposition is not the only new pressure on these buildings. Heatwaves stress cooling. Storms stress the very grid connections the projects are queuing for. Insurers have started treating concentrated campuses as a correlation problem, not a one-off property risk. None of that replaces the planning story. It stacks on top of it. A site that barely won local consent and then loses a summer to cooling curtailment is a difficult asset to explain.
Stacking is how quiet risks become portfolio risks. One delayed hall is an anecdote. A region where weather, queues, and hearings all slip is a factor.
How Sponsors Can Lower The Temperature Without Pretending
There is a version of this that is not pure conflict. It asks more of the sponsor than a community newsletter.
- Pick sites with industrial neighbours, not bedroom windows, even if the land is dearer.
- Publish a water balance a non-engineer can read.
- Name the permanent jobs, and stop padding them with construction peaks.
- Put battery rooms and generators where a failure does not face a street.
- Fund the grid upgrade in a way the utility will confirm in public.
- Accept that some plots are unwinnable and spend the option money elsewhere.
That list will not charm every activist. It will sort serious sponsors from tourists. Tourists are who give the sector its ghost-warehouse reputation.
What I Would Want In A Memo Now
If a deal team put a campus in front of me this quarter, I would ask for five pages before the market slides. Interconnection status in the utility’s own words. A planning timeline that includes appeal risk. A water note signed by someone who has stood in the basin in August. A map of residences inside any likely consent radius. And a kill-fee view of capital already spent. If those pages are thin, the rest of the deck is theatre.
Theatre still raises money. It raises it from people who have not sat in the hearing. That gap is the opportunity for anyone willing to read the dull notices.
The Bill Does Not Vanish If The Building Moves
There is a temptation, once a district revolts, to talk about deserts, platforms at sea, or orbit. Some of those ideas will find niches. Most of the next five years of capacity will still be buildings on land, tied to wires, beside people who vote. Moving the bill is not the same as paying it. A campus shifted to a poorer planning regime still draws power and water from somewhere, and that somewhere eventually notices.
I suspect the durable projects will look a bit duller than the keynote version. Smaller steps. Longer timelines. More local power dedicated to the site. Fewer surprises. Dull is financeable. Surprise is not.
Reading The $42 Billion Without Panic Or Denial
Forty-two billion dollars of European investment touched by delay or cancellation is a large figure and an easy one to misuse. Touched is not destroyed. Some of that capital will reappear on a different plot, in a different year, under a tighter rule. Some will be written down. The American comparison, near seventy-seven billion, says the original theatre has not closed either. Together they describe a global siting market that has entered its awkward phase.
Awkward phases are when spreads open. Owners of scarce, energised capacity can charge for certainty. Sponsors of paper capacity pay for hope. If you remember one distinction from this fight, remember that one.
Digital infrastructure is more visible now, and communities want to know what is being built, why it is needed, and how the local impact is handled.
Growth executive at a major colocation operator
Visibility is permanent. The black box does not come back. Firms that talk to neighbours as if the box were still shut will keep meeting 172-day protests and emergency queue laws. Firms that treat the hearing as part of the plant, not as public relations, will still get hurt sometimes. They will get hurt less.
A Closing Look At The Scrap On The Desk
That planning notice is still in the drawer. The hearing date has passed. I do not know if the hall will be built. I do know the questions on the leaflet were better than the answers in the first brochure, and that this imbalance is now repeating from Scottish planning desks to Seoul district offices. The artificial intelligence boom can keep its demand charts. The buildings have entered politics, and politics has a slower clock than a chip order.
For investors, the useful posture is neither cheerleading nor retreat. It is a bias toward sites that have already survived contact with neighbours, utilities, and water. Everything else is a story about a future megawatt. Stories are cheap. Permitted power is not. The data center backlash spreading across Europe and Asia is not a reason to ignore the buildout. It is the reason the buildout’s map, timing, and cost of capital just became the actual trade.