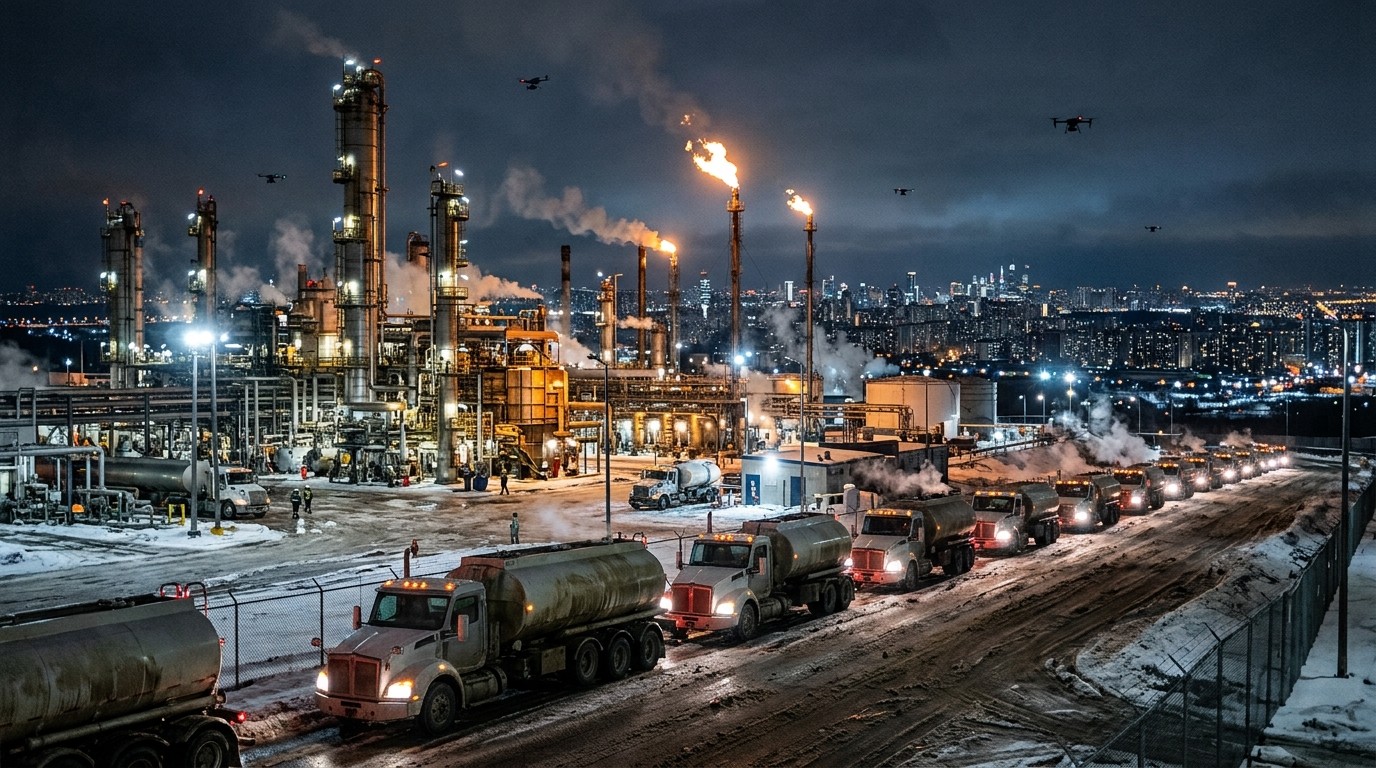

Have you noticed how quickly a single industrial target can rattle a market that already felt tight? That is the uneasy feeling hanging over diesel this week. A long-range strike on a major refinery near Moscow did not arrive in a vacuum. It landed on top of strained refining capacity, talk of longer export limits, and a Northern Hemisphere winter that is starting to look uncomfortably close.
Why This Refinery Strike Matters Far Beyond One City
The facility in question is not a symbolic plant sitting in the middle of nowhere. It processes a large volume of crude each day and feeds fuel into a dense metro region. When a site like that is hit, traders do not only ask whether flames were visible. They ask how long units stay offline, whether product can be rerouted, and how fast the loss shows up in export schedules.
I have found that energy shocks rarely stay local. Diesel is the workhorse of freight, farming, construction, mining, and a good share of winter heating in some markets. Interrupt one big node and the pressure travels through pipelines, rail cars, ports, and price screens. That is why a strike near a capital city can matter to a trucker in another hemisphere.
Ukrainian officials framed the operation as an attack on infrastructure that finances a war machine. Russian officials, as expected, treat such strikes as attacks on civilian energy security. Readers do not need a morality lecture to see the market point: physical barrels and refined product still set the tone, even when speeches dominate the news cycle.
These are billions of dollars that sustain the war machine.
– Ukrainian leadership statement after the strike
That line is political. The market translation is simpler. If a high-capacity plant is damaged, the lost output is not instantly replaced by goodwill. Refineries are complicated. Restarting units after fire, shrapnel, or emergency shutdowns can take days or much longer. Sometimes a plant comes back at reduced rates. Sometimes a secondary unit becomes the real bottleneck.
A Market That Was Already Running Hot
Before this strike, diesel and heating-oil related contracts had already been climbing. Refining spreads, the gap between crude and finished fuel, had jumped to levels that look extreme even against the last decade and a half of data. When the crack spread explodes, it is usually telling you that the system is short of conversion capacity, not just short of crude in the ground.
In my experience, people confuse a crude rally with a diesel crisis. They are related, but they are not the same animal. You can have plenty of oil and still lack the right kind of refined product in the right place. That is the awkward truth of modern energy. The world does not run on headlines about barrels. It runs on middle distillates that keep engines and boilers working.
Last week’s price action already hinted at stress in the Gulf and in Russian product flows. Add a strike on a Moscow-area plant and the market has another reason to price scarcity. Perhaps the most interesting aspect is how fast paper markets react compared with physical repair crews. Futures can reprice overnight. Welders cannot.
Export Bans Are The Quiet Multiplier
Damage to a refinery is one shock. Policy is another. Reports that Moscow could extend diesel export limits matter because they change who gets the remaining barrels. A domestic priority can be rational for a government heading into winter. For importers who leaned on those cargoes, it is a sudden hole in the calendar.
On the other side of the Atlantic, political talk about restricting US diesel exports has also surfaced. Even an “open to exploring” comment can move a tight market. Traders do not wait for a signed law. They position for the chance that barrels stay home.
- A damaged plant reduces available product at the source.
- An export limit keeps more of what remains inside one country.
- A second country debating its own ban can fragment the seaborne market further.
- Winter demand then arrives on a thinner buffer.
Stack those four and you do not get a neat textbook shortage. You get a messy one. Some regions still look fine. Others start bidding aggressively. Freight rates twitch. Inventories that looked adequate in August start looking thin in October.
Winter Is Not A Metaphor Here
Energy analysts love seasonal charts, and for once the charts deserve the attention. Northern Hemisphere winter raises heating demand, slows some logistics, and makes every delayed cargo more expensive. Diesel and heating oil sit in the same family of products. When one tightens, the other often follows.
Think about farms finishing harvest, trucking fleets restocking, and municipalities filling tanks for snow operations. None of that waits for geopolitics to calm down. The calendar is blunt. Cold weather does not negotiate.
I keep coming back to a simple question. If refining spreads were already stretched before this strike, what happens if a cold snap arrives while another plant is still limping? That is not scare talk. It is how physical markets actually behave when buffers shrink.
How A Distant Strike Reaches Households And Firms
Most people never see a distillation tower. They see a pump price, a freight surcharge, or a heating bill. The chain between those two worlds is long, but it is not mysterious.
- A refinery loses throughput after damage or a precautionary halt.
- Local supply for a metro area gets diverted from export or coastal stocks.
- Seaborne availability tightens and freight differentials widen.
- Importing regions pay up for prompt barrels.
- Retail diesel, industrial fuel, and some heating products follow with a lag.
The lag is what fools casual observers. A strike happens on a Sunday night. The supermarket shelf still looks normal on Monday. By the following month, a logistics firm is rewriting contracts and a contractor is padding bids. That delay is why energy shocks feel sudden even when the warning signs were visible.
There is also a second-round effect that does not show up in the first price spike. Higher diesel costs feed into food distribution, building materials, and almost every item that moves by truck. If you only watch gasoline, you miss half the story. Gasoline gets the political noise. Diesel does the quiet damage.
The 2008 Echo That Traders Cannot Ignore
Some commodity strategists have compared the current diesel move with the gasoline shock of 2008. The comparison is imperfect, and I would not stretch it into destiny. Still, the rhyme is useful. In that earlier episode, refined product, not just crude, became the binding constraint. Prices overshot. Demand eventually cracked. The path between those two points was ugly for businesses that could not pass costs through.
Is this 2008 again? Probably not in a copy-paste sense. The global economy, the vehicle fleet, and the sanctions map are different. What can repeat is the shape of the squeeze: crack spreads first, demand destruction later. That sequence is worth watching because policy makers often react to the second stage after the first stage has already done the harm.
When refining capacity becomes the bottleneck, crude inventories stop telling the whole story.
That is the uncomfortable lesson. A market can look well supplied in one layer and starved in another. If you only track benchmark crude, you can walk into a diesel problem with a calm expression and an empty hedge book.
Logistics, Not Just Barrels
The strike also targeted logistics linked to the broader energy system. That detail matters. Product needs more than a working tower. It needs storage, rail, road, and loading capacity. Hit the logistics layer and even healthy plants can struggle to move output.
I’ve watched markets obsess over nameplate capacity while ignoring the last mile. Nameplate is a brochure number. Useful barrels are what leave the gate. If a logistics hub is disrupted, the brochure does not deliver winter fuel.
There is a human texture here as well. Dispatchers reroute. Drivers wait. Port slots slip. Insurance premia rise on routes that suddenly look contested. None of that is as cinematic as a night strike, but it is how a “local” event becomes a global cost.
What Investors Should Actually Watch
If you follow markets rather than battle maps, a short checklist beats a flood of commentary.
| Signal | Why it matters | Risk if ignored |
| Refining spreads | Shows conversion tightness | Underestimating fuel inflation |
| Export policy chatter | Can lock barrels inside borders | Sudden regional shortages |
| Plant outage duration | Determines lost winter supply | False hope of a one-day blip |
| Inventory draws | Reveals physical tightness | Late positioning |
| Freight differentials | Maps where product is scarce | Missing regional dislocations |
None of those items require a secret model. They require patience and a refusal to treat every headline as a trading plan. A strike can be militarily significant and still be only one input in a price path. The combination with winter and export policy is the part that can turn a spike into a broader shock.
Policy Crossfire And The Risk Of Copycat Restrictions
Resource conflicts and economic measures are starting to overlap in a way that feels familiar to anyone who watched the last few years of sanctions and counter-sanctions. One government protects domestic fuel. Another considers matching the move. A third looks at strategic stock releases. The map fills with partial answers and new distortions.
There was also a public request from US political leadership that Ukraine stop striking Russian energy infrastructure while a refining crunch was already deepening. That request did not freeze the drones. Markets noticed the gap between diplomatic language and operational reality. In plain terms, energy assets remain targets even when officials say the global system cannot absorb more damage.
I do not pretend that a blog post can settle the strategic debate. What I can say is this: once energy infrastructure is treated as fair game, the economic spillover stops being a side effect. It becomes part of the campaign. Investors and households then live with the residue.
Who Feels A Diesel Shock First
Not every sector absorbs this the same way. Some can pass costs through in weeks. Others get trapped.
- Road freight and parcel networks see fuel as a direct operating cost.
- Agriculture feels it in harvest logistics and later in fertilizer and distribution.
- Construction absorbs higher machine-hour costs and delayed deliveries.
- Manufacturers with just-in-time inventories face freight volatility.
- Households in heating-oil regions meet the bill at the tank, not the terminal.
Airlines get the public drama. Trucking gets the grind. If diesel stays elevated into winter, the grind wins. That is not a prediction of collapse. It is a reminder that industrial fuel is a tax on movement. Raise the tax and the economy moves less smoothly.
Why “Record Spreads” Are A Warning, Not A Trophy
A heating-oil crack near record territory can look like a gift to refiners that still have units running. For the system as a whole, it is a distress flare. Extreme margins usually mean the market is begging for more product and cannot get it fast enough.
High margins do invite more runs, imports, and opportunistic supply. That response takes time. Ships are slow. Maintenance schedules are sticky. Insurance and sanctions compliance add friction. The lag between a screaming spread and extra barrels is where winter can do real harm.
So yes, some refiners may print excellent quarters. That does not cancel the shock for buyers. In fact, those two facts often arrive together. Profit for the plant, pain for the fleet.
A Practical Reading Of The Next Few Weeks
The honest stance is uncomfortable. We do not yet know how long the damaged units stay constrained. We do not know whether export limits get extended, tightened, or quietly eased. We do not know how cold the first stretch of winter will be. Those unknowns are the story.
Still, a few working assumptions look reasonable. First, middle distillates deserve more attention than headline crude for now. Second, any additional strike on large plants will meet a market with less patience. Third, political debate over export bans can move prices even if no ban is signed.
If you manage a business that burns diesel, this is the moment to look at contracts, surcharges, and inventory timing. If you invest, this is the moment to separate a one-day geopolitical spike from a multi-month tightness in refined product. Those are different trades and different risks.
The Broader Collision Of War, Weather, And Trade Rules
Military pressure, economic pressure, and resource pressure are lining up in the same season. That alignment is what makes this episode feel larger than a single plant. Export restrictions on energy products sit beside restrictions on other critical materials. Each measure can be defended in isolation. Together they raise the odds of retaliatory loops.
There is no clean off-ramp visible in the public chatter. That absence matters. Markets can live with conflict. They struggle with conflict plus winter plus fragmented trade rules. The combination shrinks the room for error.
I’ve found that readers want a hero and a villain. Energy markets offer neither. They offer constraints. A refinery near Moscow is one constraint. A possible diesel export extension is another. A political conversation about keeping US barrels at home is a third. Winter is the deadline that does not care who is right.
What “Economic Shock” Would Actually Look Like
The phrase gets thrown around until it means everything and nothing. A real shock in this setting would not require empty pumps on day one. It would look like a cluster of smaller breaks.
- Freight rates stay elevated after the first headline fade.
- Regional product prices diverge more than usual.
- Food and goods inflation picks up a second wind through logistics.
- Small operators with weak pricing power cut routes or hours.
- Policy makers start discussing emergency releases or temporary bans after prices have already jumped.
That pattern is how an energy problem becomes a growth problem. Not overnight. In layers. By the time the layers are obvious, the easy hedges are gone.
Keeping Perspective Without Going Numb
It is possible to over-read one strike. Plants get repaired. Cargoes get reshuffled. Demand can soften if prices stay high. Those safety valves are real. Ignoring them turns analysis into fatalism.
It is also possible to under-read the setup. A market that was already printing extreme refining spreads does not need much extra damage to stay tight. That is the needle this story is threading. The strike is new. The tightness is not.
So where does that leave a careful reader? Watch the plant status. Watch export rules. Watch inventories into the first cold weeks. Treat dramatic language as color, not as a substitute for those three.
The systems used included a mix of long-range strike tools aimed at energy and logistics targets.
– Public remarks describing the overnight operation
The catalogue of systems is a military detail. The economic detail is shorter. Distance is no longer a reliable shield for large energy assets. Once that becomes normal, every major plant sits inside the risk map, not outside it.
A Closing Read For Anyone Who Pays For Movement
Diesel is easy to ignore until it is not. It does not have the cultural glow of other commodities. It does not trend in casual conversation until a heating bill or a freight surcharge arrives. That is why a strike on a Moscow-area refinery can look remote and still be relevant.
If there is a personal takeaway here, it is this. The next few months will test whether the global refining system still has spare room. The early evidence says the room is smaller than many assumed. Winter will grade that evidence in a language everyone understands: price, delay, and availability.
No need to panic-buy a thesis. Need to stay awake. A major plant was hit while diesel was already tight, while export limits were under discussion, and while cold weather is moving onto the calendar. That combination is enough to keep this story on the desk. The question is no longer whether energy and conflict are connected. The question is how much of the winter bill that connection will write.