

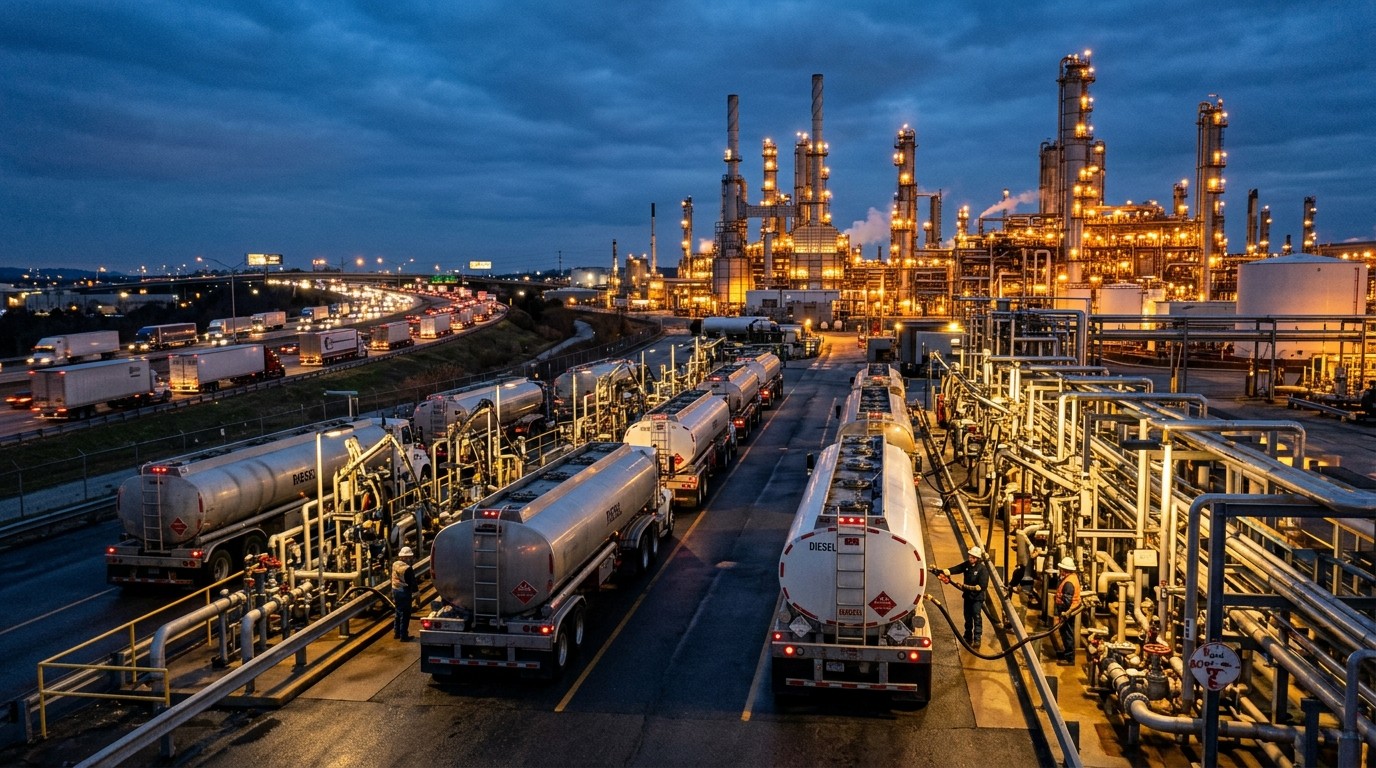

Have you ever watched a fuel price board flip higher and felt that small, stubborn knot in your stomach? I have. Diesel sits in a strange place in the public mind. It is not the glamorous headline fuel most people talk about at dinner. Yet it moves groceries, construction materials, harvests, and a good slice of the real economy. When diesel stays expensive, the pain does not stay at the pump. It travels.
That is why a rumored diesel export ban landed with such force. One week the conversation sounded like a short-term clampdown was coming. A few days later, industry leaders were being told the opposite. If you care about pump prices, freight costs, or the quiet mechanics of energy policy, this tug-of-war is worth sitting with. It is messier than a slogan. It is also more interesting.
Why The Diesel Fight Suddenly Feels Personal
Retail diesel recently hovered near historically painful levels, with the national average still close to recent peaks even after a modest dip. Crude, meanwhile, remained firm enough to keep pressure on policymakers. That combination is politically awkward. Households notice gasoline. Businesses notice diesel. Campaign calendars notice both.
I keep coming back to a simple point. Diesel is a workhorse fuel. Ban talk sounds decisive. Markets, though, rarely reward simple theater. In my experience, energy policy that ignores logistics tends to look clever on a whiteboard and clumsy on a loading rack.
Keeping more diesel inside a country does not automatically place that fuel at the pump.
That sentence is the heart of the current argument. Officials want cheaper fuel. Refiners want workable rules. Truckers want predictability. Voters want relief before the next election cycle. Those goals overlap. They do not perfectly align.
What Changed In A Matter Of Days
Midweek chatter suggested a possible 90-day curb on diesel leaving the country. The idea was blunt: hold product at home, ease local tightness, and force prices down. By late in the week, a senior lawmaker from a major refining state told industry executives he had received White House assurances that a ban would not move forward.
Notice the wording. Assurances from the White House. Not a signed order. Not a detailed memo. Not a public speech that closed every door. Still, the message was enough to calm a room full of people who actually run plants. That matters. Refining is a confidence business as much as a barrel business.
A White House official later framed the president’s stance in familiar terms. Pump prices should fall. Every option remains under review. That is the kind of sentence that keeps markets alert without locking anyone into a single tool. I find that mix of urgency and vagueness very on-brand for energy politics.
Two Camps, One Price Board
Inside the administration, the split is not mysterious. One view treats an export curb as a visible lever. Another view treats it as a self-inflicted wound. The energy secretary has been in the second camp, warning that a blanket halt would do more harm than good and pushing instead for voluntary industry steps that raise domestic availability.
He has also left a narrow opening. Exports as a category may continue, while destinations and flows could still be nudged. That is a quieter form of intervention. Less dramatic. Harder to explain on television. Possibly more workable if the goal is to avoid breaking a system that already looks stretched.
- One camp wants a fast, visible clamp on outbound diesel.
- Another camp wants more barrels at home without shutting the export valve.
- Both camps claim the same prize: lower prices at the pump.
Perhaps the most interesting aspect is how quickly the public conversation jumped from “maybe a ban” to “the ban is off the table.” Markets hate that kind of whiplash. Plants hate it even more. A refinery cannot redesign a slate overnight because a rumor had a good week.
The Refining Reality Nobody Wants To Hear
Analysts who live inside the refining complex have been blunt. A proposed export stop would likely damage domestic plants and still fail to deliver the intended relief. Why? Because product trapped in the wrong place is not the same as product available where trucks actually fill up.
Think of diesel like water in a house with old pipes. You can fill the tank in the basement and still have a dry tap upstairs. Pipelines, terminals, barge routes, and regional demand patterns decide whether extra barrels become cheaper fuel or expensive inventory sitting in the wrong region.
I’ve found that people outside the industry underestimate that plumbing. They imagine a national tank. What exists is a patchwork. Gulf Coast strength does not instantly solve a tight pocket inland. Export flows are part of how plants stay utilized and how product finds a home when local demand cannot absorb every gallon.
A ban can look like relief on paper and still leave the wrong barrels in the wrong tanks.
That is not a defense of high prices. It is a warning about tools. If the tool cannot move product to the nozzle, the politics will still demand a win. Then officials reach for the next lever. Taxes. Regulations. Temporary rule changes. Those are already in the conversation.
Taxes, Red Diesel, And Other Levers
If an export ban is truly off the table, the toolkit does not go empty. Officials have discussed allowing dyed off-road diesel onto highways in a limited way. The practical appeal is obvious. That product normally carries a different tax treatment. Opening the gate, even temporarily, could suspend some diesel taxes, including a federal levy near 24 cents a gallon.
Twenty-four cents will not rewrite a household budget by itself. Stacked on top of other costs, it is not nothing. For fleet operators running tight margins, a few dimes per gallon can decide whether a route stays profitable. For voters, any visible drop still photographs well.
Regulatory costs sit in the same drawer. Permitting friction, seasonal rules, and compliance expenses all show up in the final price, even if nobody recites those line items at the pump. I am skeptical of miracle cuts. I am not skeptical of the idea that small frictions add up.
| Policy Tool | Intended Effect | Main Risk |
| Export ban | Keep more diesel at home | Plant stress and weak local delivery |
| Tax relief | Lower the posted pump price | Budget cost and temporary impact |
| Red diesel flexibility | Expand usable supply on roads | Enforcement and market confusion |
| Voluntary rerouting | Shift barrels toward tight regions | Limited scale and slow results |
Look at that grid and you can see why a ban felt tempting. It sounds like control. Tax relief sounds like a discount. Voluntary industry changes sound like homework. Politicians prefer the first two. Operators often prefer the last one, because they know what their units can actually do this quarter.
The Global Crunch Behind The Domestic Argument
This is not only a Washington story. The global refining system looks tight well into the later years of the decade. Diesel and gasoline can stay elevated when conversion capacity is scarce. That is the unglamorous truth. You can argue about exports all afternoon and still run into a world that does not have spare distillate sitting around politely.
Some research desks have warned that stress in diesel can set up the next squeeze in gasoline. The two products share hardware. When plants chase one yield, another yield can suffer. Drivers feel that later, often after the political conversation has already moved on.
In my view, that linkage is the part casual commentary misses. People treat fuels like separate aisles in a store. Refineries treat them like outputs from the same kitchen. Change the recipe too hard in one direction and dinner gets weird.
- Global conversion capacity stays tight.
- Diesel remains the workhorse product under strain.
- Gasoline can inherit the squeeze if yields shift.
- Domestic politics then demands a faster answer than plants can give.
That sequence is why a 90-day experiment sounded both attractive and dangerous. Ninety days is long enough to scramble contracts. It is short enough to leave the structural shortage untouched. You get disruption without a lasting fix. Not a great trade, if you ask me.
What Industry Leaders Heard On That Call
The reassurance did not arrive as a press conference. It arrived on an industry call. A senator from Texas told refining and petrochemical executives that the White House had indicated a ban would not proceed. He did not name a single official as the source of the final no. He also did not claim the president personally closed the file.
That ambiguity is not a small detail. Energy markets trade on precision. Policy markets trade on implication. Between those two rooms sits a lot of nervous capital. Plants decide maintenance windows, export nominations, and inventory strategy with incomplete information. They always do. This week just made the incompleteness more obvious.
Representatives for the lawmaker and the industry group did not immediately add public color. Fine. Silence after a private briefing is normal. The substance still leaked into the wider conversation, which tells you how hungry people were for a signal.
Why Pump Politics And Plant Economics Collide
Presidents get judged on the price board. Refiners get judged on utilization, margins, and whether a unit can run without eating itself. Those scorecards are related. They are not identical. A policy that wins a week of headlines can still strand a plant with a product slate it cannot sell at home on the schedule required.
Exports are not a hobby for coastal plants. They are a release valve. When domestic demand in one grade is soft, foreign buyers keep the complex running. Shut that valve and you do not magically create a perfect domestic match. You can create a glut here, a shortage there, and a weaker incentive to keep running hard.
I have a bias here, and I will own it. I would rather see messy, partial measures that keep plants healthy than a clean-looking ban that looks tough and then backfires. Tough is easy. Durable is harder.
Price relief that damages the machines producing the fuel is not relief. It is a delay with interest.
Six Familiar Options When Oil Stays Sticky
Commodity researchers have sketched a short menu for governments facing high oil and fuel costs. Reduce fuel taxes. Ease selected rules. Encourage more domestic throughput. Manage strategic stocks with care. Talk producers into more supply. And, yes, flirt with trade restraints. None of those tools is new. The mix is what changes.
Tax cuts are the most politically readable. People see a lower number. The fiscal cost arrives later, in a quieter room. Stock releases can shave a peak and still leave the market tight if the underlying shortage is in refined product rather than crude. Talking up supply is cheap. Delivering barrels is not.
So the diesel file sits in a crowded toolbox. The export ban was the loudest item this week. It may not be the one that actually gets used. If I had to guess, tax and regulatory tinkering will keep more airtime than a hard stop at the dock. Guessing is all anyone can do until paper becomes policy.
Relief math in plain language:
  Lower tax + better logistics + running plants
  beats
  trapped barrels + weaker refining incentive
What Drivers And Fleets Should Watch Next
Forget the rumor cycle for a minute. Watch three things. First, the spread between crude and diesel. If crude eases and diesel does not, the bottleneck is downstream. Second, regional inventories, not just a national average. Averages hide pain. Third, any formal move on dyed fuel or federal tax treatment. That would show up faster than a grand industrial redesign.
Fleets already plan with ugly assumptions. Construction firms do too. Farms do it every season. If policy stays foggy, they will hedge with higher contract prices and fewer long commitments. That is how uncertainty becomes inflation in slow motion.
- Watch distillate inventories by region, not just the headline stock number.
- Watch crack spreads as a clue to refining stress.
- Watch tax talk more closely than ban talk if the latest assurances hold.
- Watch freight rates, because diesel pain often arrives there first.
Is that exciting? Not really. It is useful. Useful beats exciting when your budget depends on a tanker truck showing up on time.
A Human Read On The Political Clock
Midterms make energy policy impatient. That is not a scandal. It is a calendar. Officials know voters do not parse yield shifts. They parse the number on the sign. So the White House will keep saying every option is on the table even after one option appears to have been quietly pulled to the side.
That dual language can sound like confusion. Sometimes it is discipline. You reassure operators so they keep running. You keep pressure language in public so markets do not assume the government has gone to sleep. Whether that balance works depends on the next few prints at the pump.
If prices drift down on their own, the ban debate fades. If prices stay ugly, the file reopens. I would not treat Friday’s assurances as a permanent treaty. I would treat them as the current weather.
The Quiet Cost Of Whiplash
Policy noise has a price even when no rule changes. Traders widen spreads. Exporters hesitate. Terminals delay decisions. Maintenance schedules get conservative. None of that appears in a campaign ad. All of it can keep diesel firmer than it needed to be.
This is where I get a little stubborn. Clarity is a supply tool. If leaders want more domestic diesel, they should say what they will not do as clearly as what they might do. Ambiguity is not strategy when the audience builds steel and concrete for a living.
The industry call helped. A public, plain sentence would help more. Until that arrives, everyone is reading tea leaves in a fuel tank.
How A Ban Could Still Fail Even If It Returned
Suppose the idea comes back. What then? First, contracts already booked would need unwinding. That is friction with a bill attached. Second, foreign buyers would look elsewhere and might not return on cue. Third, domestic buyers in loose regions would not automatically absorb every extra gallon. Storage fills. Discounts appear in one place while another region stays tight.
There is also the crude side. Refineries buy crude against an expected product slate. Change the product outlet and the crude math changes. Some plants lose margin. Some cut runs. Less throughput can mean less gasoline as well as a different diesel map. The own-goal risk is real.
Energy secretaries who come from the field tend to see that quickly. Campaign operatives see a lever. Both can be acting in good faith and still talk past each other. That is the adult version of this story. Not heroes and villains. Two clocks, two incentives.
What “Voluntary Industry Measures” Actually Means
When officials ask industry to help without a ban, they usually mean a few practical things. Maximize distillate yield where units allow it. Point more barrels toward tight domestic destinations. Delay noncritical exports if local balances look ugly. Share more operational visibility so government is not flying blind.
None of that is free. Yield shifts can reduce other products. Rerouting can raise freight costs. Delaying an export cargo can strand value. Companies will do some of it if they believe the request is temporary and the alternative is worse. They will resist if they think the request is a ban in slow motion.
Trust is the hidden commodity here. The Friday message was an attempt to buy some of it back.
Households Feel Diesel Even When They Do Not Buy It
Most people do not fill a diesel pickup every week. They still pay diesel. Food distribution, parcel networks, municipal fleets, and building materials all carry that cost forward. A few extra dimes per gallon become a little more on a grocery bill, a delivery fee, or a contractor quote.
That is why the political temperature stays high even when gasoline gets the bigger microphone. Diesel is the background hum of a goods economy. When the hum gets expensive, everything feels slightly worse and nobody can point to a single villain with perfect accuracy.
So yes, the export argument is technical. The consequences are not. They show up in ordinary life, which is why the rumor had oxygen in the first place.
A Straight Answer To The Title Question
Is a diesel export ban off the table? For now, that is the working assumption inside the industry after those White House assurances. It is not a law of nature. It is a present-tense political choice. The president still wants lower pump prices. Advisers still dislike a blanket curb. Analysts still warn that the global system is tight. Those facts can live together for a while. They cannot live together forever if the price board refuses to cooperate.
If you need a practical takeaway, use this one. Do not build a strategy on the loudest rumor of the week. Build it on logistics, taxes, and whether plants keep running hard. The rest is weather.
The market will forgive a hard policy faster than it will forgive a confusing one.
I would add one last personal note. Energy arguments get tribal in a hurry. This one does not have to. You can want cheaper fuel and still admit that trapping barrels is not the same as delivering them. You can want industry flexibility and still admit that families are tired of paying crisis prices. Holding both thoughts at once is not weakness. It is how adult policy is supposed to work.
Watch the next official statement. Watch the next inventory print. Watch whether tax talk gets specific. That is the real story now. The ban was a spark. The fire, if there is one, will be decided by whether diesel actually becomes easier to buy where people need it.
Until then, the country is doing what it always does with fuel: hoping the sign goes down, arguing about who should make it happen, and discovering once again that diesel is never just diesel. It is freight, food, politics, and patience, all poured into the same tank.



