
I keep coming back to a simple question when I look at California. If the state keeps making it more expensive to hire, build, and file paperwork, why do so many companies still plant their flag there? It is not because executives enjoy extra forms. It is because the state still offers something that is hard to photocopy and ship to another zip code.
Why The Golden State Still Holds On To So Much Business
California has a strange habit. Lawmakers raise taxes, thicken the rulebook, and add new reporting duties. Then the same week, another company posts record revenue from a campus that still sits inside the state. That contrast is not a puzzle if you stop treating “business friendly” as a slogan and start treating it as a ledger. Firms stay when the benefits still outweigh the bill. They leave, or they quietly expand elsewhere, when the math flips.
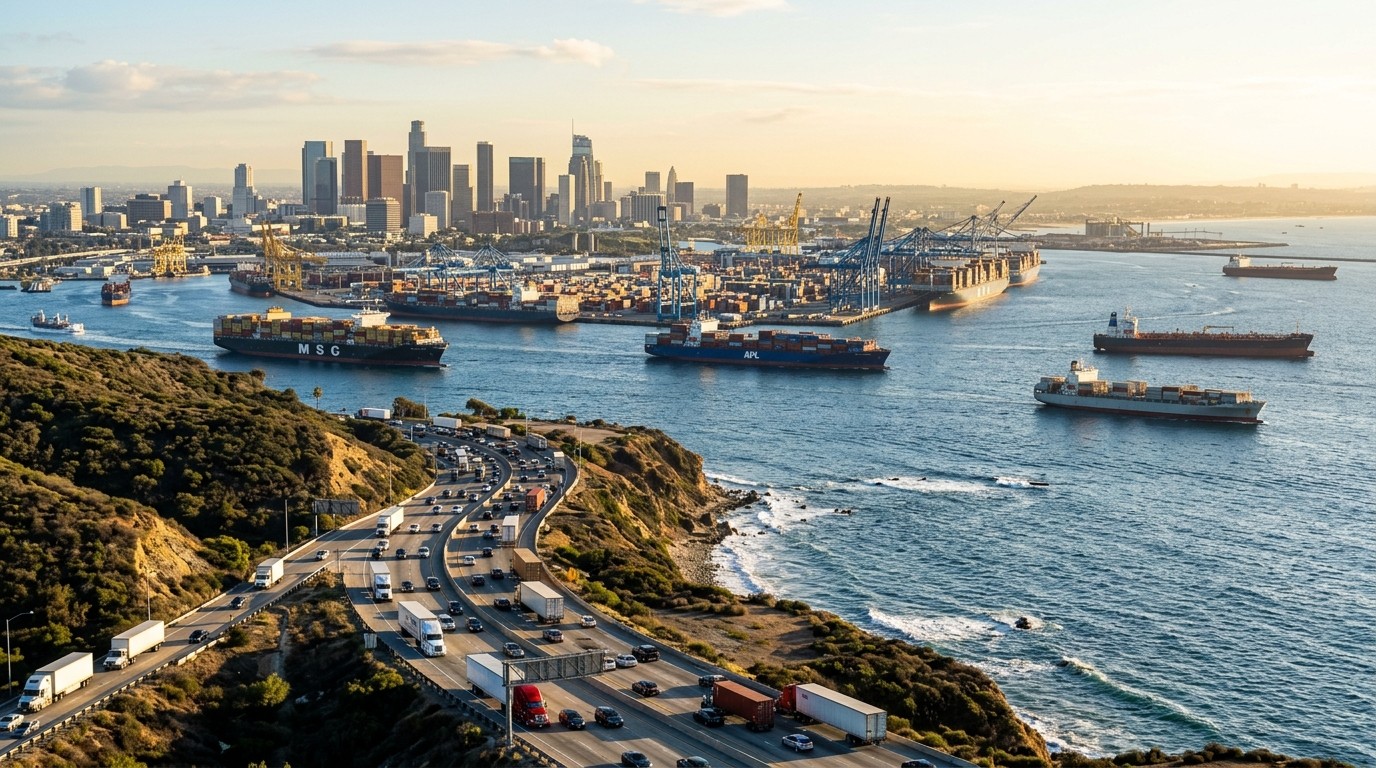
An older idea from classical economics still helps here. The division of labor only stretches as far as the market will allow. California is not a small pond. It is a dense, specialized, globally connected market. Ports face the Pacific. Universities keep feeding specialized talent into industries that already exist. Decades of capital, know-how, and supplier networks sit on top of one another. Silicon Valley did not appear after one good fiscal year. Neither did the entertainment cluster, the farm belt, or the trade machinery that moves goods through the state’s harbors.
Those layers explain a lot of patience. A company will tolerate costs in a rich market that it would never accept in a thinner one. I have found that people outside the state often miss this point. They see the headline tax rate and assume the story is over. Inside the state, managers still talk about customers, talent, and speed of deal-making. That is not romance. That is friction and access.
The Market Advantage Is Real, Not Magical
Scale matters. So does specialization. When thousands of engineers, producers, logistics planners, and investors already live within a few hours of one another, a firm can hire faster and partner faster. A port that already handles enormous cargo volume is not the same as a promising site on a map. A university pipeline that has trained generations of workers is not the same as a brochure promising “workforce development.”
California’s edge is accumulated. That word sounds dull. It is the whole game. Factories, studios, labs, law firms, and shipping desks did not land in one afternoon. They stacked. Each new firm found suppliers next door. Each new hire found a career path that already existed. Over time that stack became expensive to recreate.
A large market with deep skills can absorb costs that would crush a company in a thinner region.
Still, an advantage is not a lifetime pass. States that arrived later do not need to copy every California asset. They only need to close enough of the gap that lower costs start winning the next investment. Workforces can be trained. Capital can move. Networks can form in Austin, Phoenix, Las Vegas, or Nashville. California got there first. That is not the same as owning the future.
The Departures That Actually Matter
Some firms have already decided the premium is too high. A major electric vehicle company moved its headquarters to Texas. A century-old energy giant shifted its headquarters to Houston. A large software firm left for Austin. These were not desperate outfits hunting for cheap rent. They were successful businesses with options. That is the part worth sitting with.
A struggling shop fleeing high rent tells you one story. A wealthy firm choosing another state tells you another. The second story says even a rich market has a price. Once that price feels arbitrary, pride in a California address stops being a strategy.
In my experience, the loud headquarters move is not even the most important signal. It is the easiest one to film. The quieter decision is where the next warehouse, plant, or data hall gets built. A company can keep a handsome office in Los Angeles and still put the growth in Nevada. No banner headline. No farewell party. Just a capital budget that lands somewhere else.
- Headquarters can stay while expansion leaves.
- One missed factory can matter more than one famous exit.
- Thousands of quiet site choices add up faster than speeches.
- Talent still matters, but so does the cost of keeping that talent on payroll.
Multiply those quiet calls across industries and years. You get a slower kind of loss. Tax receipts look fine for a while. Employment in flagship sectors still photographs well. Underneath, the next increment of growth is already shopping for a different climate.
How Costs Creep In Without A Single Dramatic Law
People love a villain bill. One statute. One signature. One night of cable debate. Real cost usually arrives as a pile. A higher rate here. A new disclosure there. A hiring rule that sounds modest until the legal team prices the risk. None of those items, taken alone, sends a billion-dollar firm packing. Together they change the discount rate managers apply to California projects.
Consider a proposal that would ask certain large companies with old corporate roots to hunt through historical records for ties to slavery and then report findings to the state. Whatever one thinks of the moral aim, records do not search themselves. Lawyers read. Archivists dig. Compliance staff document. For a giant firm the cash outlay may look small next to annual revenue. That is exactly why lawmakers underestimate it. The expense is not only money. It is attention, legal exposure, and one more reason to put the next dollar of growth on a different map.
I’ve sat with enough operators to know how this conversation goes in a conference room. Nobody pounds the table about one form. Someone asks a colder question. If we build the next site here, what else will we be asked to do in three years? Uncertainty has a cost of its own. Firms can plan around a high but stable burden. They hate a burden that keeps growing in unpredictable directions.
What California Still Sells Better Than Most Places
Start with trade. Facing Asia is not a branding line. It is geography plus infrastructure plus habit. Importers, exporters, freight forwarders, and customs specialists already know the dance. That ecosystem is expensive to assemble from scratch. A rival state can build a dock. It cannot instantly invent the surrounding service layer.
Then there is talent density. Not every worker needs to be a celebrity engineer. Specialized labor includes the person who already knows how a studio budget works, how a chip design review runs, how a produce shipper times a harvest, how a venture round gets documented. Those skills cluster. Clusters cut search costs. They also raise wages, which is part of the state’s bill. The same feature that attracts firms also makes payroll painful.
Capital is sticky in a different way. Investors like to sit near the deals they already understand. That does not mean money cannot fly. It means the first meeting still happens more easily in rooms that already exist. Over time that convenience becomes culture. Culture is not destiny, but it is a head start.
| Advantage | Why It Still Matters | How Fragile It Is |
| Market size | Customers and partners are already nearby | Other states can grow demand over time |
| Specialized labor | Hiring is faster in a deep talent pool | Remote work and training can spread skills |
| Trade infrastructure | Ports and logistics networks are hard to copy quickly | Rival gateways can chip away at volume |
| Accumulated capital | Know-how and suppliers sit in one place | New clusters can form after enough relocations |
Look at that table long enough and a pattern shows up. Every California strength is real. Every one of them can be eroded if the price of access keeps rising while other regions get “good enough.” Good enough is the phrase that should keep Sacramento awake. Competitors do not need to become California. They need to become close enough that the cost gap does the rest.
The Quiet Math Behind A Headquarters Decision
A headquarters is a symbol. It is also a payroll, a lease, a tax nexus, and a political address. When a firm moves the letterhead, it is making a statement about future optionality. When it keeps the letterhead and shifts the factory, it is making a statement about cash.
I tend to watch the second move more closely. Expansion is where the future lives. A state can boast about famous logos on downtown towers and still lose the next decade of industrial capacity. That is a boring way to decline. It is also a common one.
Think about a distribution center. The customer still buys the brand. The warehouse jobs, property taxes, and supplier contracts land in another state. Repeat that across logistics, manufacturing, and back-office functions. California keeps the glossy part of the identity. Rival states keep the payroll growth.
- Compare the full cost of a California hire, not just the wage.
- Price the delay caused by permits and reviews.
- Ask where the next increment of capacity should sit.
- Leave a visible office if the market still justifies it.
- Put scalable assets where the all-in cost is lower.
That sequence is not ideological. It is how capital committees talk when the cameras are off. Perhaps the most interesting aspect is how rarely the public debate matches that sequence. The public debate wants a morality play. The committee wants a net present value.
Regulation As A Stack, Not A Single Wall
One rule can be justified. Ten rules can still be justified one by one. The firm does not experience them one by one. It experiences a stack. Employment rules, environmental reviews, disclosure duties, industry-specific mandates, and local overlays all sit on the same project timeline. Delay is a cost. Legal uncertainty is a cost. The staff required to interpret the stack is a cost.
California often talks as if durability of its clusters means immunity. Hollywood will not rebuild overnight in another city. The ports will not float to the desert. That is true and incomplete. A studio can shoot more days elsewhere. A shipper can route more volume through another gateway. A tech firm can keep a research salon in the Bay Area and put the heavy hiring in Texas. The cluster does not have to vanish to shrink.
There is a human habit here that I find almost touching, and a little dangerous. Success makes leaders believe the next burden will also be absorbed. Past endurance becomes proof of future endurance. Markets do not work that way forever. They work that way until they don’t.
Durability can hide erosion. A cluster can look intact while its next decade of growth is already leaving.
Why Rival States Do Not Need A Perfect Copy
Texas does not need San Francisco weather. Arizona does not need a century of studio history. Nevada does not need the same university density on day one. They need reliable power, faster permits, lower tax friction, and a workforce that can be trained at a tolerable cost. That package is not glamorous. It wins site fights.
Remote collaboration changed the old map as well. Not every team must sit in one metro to function. That weakens one of California’s classic arguments: you must be here to hire the people who insist on being here. Some of those people will still insist. Others will take the same job with a different backyard and a lower housing bill.
Housing is part of the business climate even when it never appears in a corporate code section. If workers cannot live near the job without heroic commutes, the employer pays in wages, turnover, and recruiting time. A state can tell itself it is only regulating companies. It is also pricing the labor those companies need.
The Political Temptation To Keep Pushing
When a state is rich, the temptation is obvious. Add one more mandate. The firms look profitable. The cause looks worthy. The immediate departure risk looks low. That last point is the trap. Low immediate risk is not the same as low long-run risk.
Lawmakers can point to companies that stay and call that proof. They can point to startups that still incorporate locally and call that vitality. Both observations can be true in the same year that expansion capital is leaking. A healthy present and a weaker future can share a calendar.
I do not think every California rule is foolish. Some protect health, safety, or market transparency. The issue is the absence of a running total. Nobody in the room is forced to ask a blunt question: after this addition, what is the all-in price of staying, and how does that price compare with Phoenix or Dallas for the next plant?
A simple way managers score a state:
  Market access
  Talent depth
  Tax and compliance load
  Permit speed
  Predictability
If the last three keep worsening, the first two have to work harder every year.
What “Leaving” Looks Like When Nobody Packs The Logo
The public loves a moving truck. Reality is messier. A firm can:
- Keep a flagship office for clients and recruiting.
- Shift manufacturing to a lower-cost state.
- Put customer support in a cheaper metro.
- Incorporate new subsidiaries elsewhere.
- Hire the next two hundred people outside California.
Each of those choices is a partial exit. Add them together and the state’s claim on future prosperity gets thinner. That is why the interesting question is not “Has California collapsed?” It has not. The interesting question is “How many more times can the price of staying be raised before the next increment of growth declines the invitation?”
Some companies have already answered. Others still like the market enough to pay. The split is the story. It is not collapse versus paradise. It is a moving equilibrium.
Talent, Universities, And The Limits Of Prestige
Prestige still pulls people. Famous campuses still mint specialists. That pipeline is a genuine asset. It is also portable in pieces. Graduates can leave. Faculty research can partner with labs in other states. A company can recruit from a California campus and relocate the hire two months later.
So the university advantage is real and leaky at the same time. California trains. Other states can employ. If local costs make it hard to keep young workers after graduation, the training engine starts exporting talent. That is a generous hobby for a high-cost region, and a risky economic model.
I’ve found that prestige arguments age badly when housing and taxes do the talking. A twenty-six-year-old will romanticize a coastal job until the rent math becomes a second job of its own. Firms feel that pressure in offers, bonuses, and attrition. The state feels it later, in a thinner middle of the labor market.
Agriculture, Entertainment, And Trade Are Not The Same Bet
Not every California industry has the same mobility. Soil, climate, and water rights are not as footloose as a software team. A vineyard cannot pack itself into a moving container as easily as a cloud workload. That difference matters. Some sectors are anchored by nature. Others are anchored only by habit and network effects.
Entertainment looks anchored until production incentives elsewhere get rich enough. Trade looks anchored until another port becomes reliable and cheaper on the full trip. Tech looks anchored until a critical mass of engineers decide they can do the work from a city with shorter drives and lower state tax. Anchors rust at different speeds.
Policy that treats all of these sectors as equally captive is going to misprice risk. The captive sectors can be squeezed longer. The mobile ones will bargain with their feet, or with their next site plan.
A Fair Reading Of The Companies That Stay
Staying is not proof that costs do not matter. Staying can mean the local market is still unique. It can mean the switching cost is still high. It can mean management is waiting for one more data point. It can even mean inertia, which is a force in large organizations. Inertia works until a new CEO wants a clean story for investors.
There is also a customer reason. If your buyers, studios, or suppliers are concentrated in California, leaving can damage relationships. Proximity still has a commercial value. That value should be counted honestly. It should not be treated as infinite.
According to many operators I have heard over the years, the mood inside firms is less “we love the politics” and more “we can still make the numbers work.” That is a colder loyalty. Cold loyalty lasts until a spreadsheet says otherwise.
What Lawmakers Should Be Measuring Instead
Headcount of famous companies is a lazy metric. Better questions exist.
- Where did new industrial square footage go last year?
- How long did major permits actually take?
- What share of new corporate jobs landed out of state for firms that still keep a California office?
- How predictable is the next five years of tax and compliance policy?
- Are mid-size firms expanding locally or only the giants with no easy substitute market?
Those measures are less cinematic. They tell you whether the state is monetizing an old advantage or building a new one. A place can look crowded and still be losing the future. Airports look crowded too. That does not mean every passenger is coming back next year.
If I were writing a briefing memo, I would put one line at the top. Do not ask how much business can afford. Ask how many times you can raise the toll before the next project chooses a different road.
The Price Of Staying Is A Moving Number
Costs are not only statutory. Energy prices move. Insurance markets tighten. Local rules vary by county. Housing shortages change wage demands. A firm that accepted the California premium five years ago may be looking at a different premium today even if the famous tax rate barely changed.
That is why “yet” belongs in the title of this whole debate. Businesses have not left in a single wave. Many have not left at all. The word that should worry a high-cost state is not exodus. It is erosion. Erosion does not trend on the same day. It shows up in site-selection shortlists that keep getting shorter for California and longer for everyone else.
I do not see an overnight emptying of the state. I see a contest between inherited advantages and accumulated friction. Inherited advantages are impressive. Accumulated friction is patient. Patient forces often win the long file.
A Practical Way To Think About The Next Decade
Imagine two folders on a chief financial officer’s desk. One is labeled California. It contains unmatched market access, dense skills, and a thick compliance binder. The other is labeled Sun Belt. It contains a thinner market, a rising talent pool, and a lighter binder. The decision is not which folder is prettier. The decision is which folder maximizes the next ten years of after-tax, after-delay return.
For some consumer brands, the first folder still wins. For a new plant with thin margins, the second folder starts to look adult. For a headquarters with symbolic value, the answer can split: keep the nameplate, move the engine.
That split is already happening. It will keep happening unless the price of the first folder stops rising faster than its unique value. There is nothing mystical about this. Households make the same choice when rent outruns the charm of a neighborhood. Companies are just households with better lawyers.
California does not need to become cheap. It needs to stay worth the premium.
Where The Argument Usually Goes Wrong
One camp says any criticism of costs is an attack on public purpose. Another camp says any firm that stays is a hypocrite. Both miss the ledger. A company can dislike a rule and still need the market. A state can chase a social goal and still overcharge for the privilege of access. Adults can hold both facts at once.
Another error is treating one famous relocation as proof of collapse, or treating one new campus as proof of immunity. Single events are color. The series of capital decisions is the plot.
A third error is assuming networks cannot form elsewhere because they took a long time to form here. That is like saying a forest cannot grow because the old forest is tall. New clusters are messy and slower at first. Then they are not.
The Human Texture Behind The Spreadsheets
Executives are not only calculating rates. They are also calculating aggravation. How many hours will counsel spend on the next disclosure? How many months will a retrofit sit in review? How hard will it be to explain the next surprise rule to a board that already asked why the company pays more to operate in one state than in three others combined?
Aggravation sounds soft. It is not. It changes the emotional discount applied to a location. People put growth where the process feels navigable. They delay growth where the process feels like a second business.
Workers have their own ledger. Weather, culture, and industry status still attract. Commute time, rent, and tax withholding still repel. The firm sits in the middle of those two ledgers and tries not to lose the people who make the cluster valuable in the first place.
So Why Haven’t They All Left?
Because the market is still vast. Because the ports still face the ocean that carries so much of the country’s trade with Asia. Because specialized labor and accumulated know-how are still concentrated. Because switching costs remain high for many industries. Because some customers still want you in the room. Because a coastal address still helps recruiting in certain fields. Those are serious reasons. They are also reasons with a ceiling.
The ceiling is the point at which a “good enough” rival plus a lower bill beats a superb market plus an ever-rising bill. California has not hit that ceiling in every sector. It has hit it for some headquarters. It is approaching it for some expansion projects. That mixed result is exactly what a mature, high-cost region should expect when it keeps testing the willingness to pay.
I keep thinking the useful question is not whether the state is finished. It is not. The useful question is how many additional turns of the cost dial remain before more firms decide the future is easier to build somewhere else. Some already decided. More are still doing the arithmetic. The answer will not arrive as a single press release. It will arrive as a pattern of quiet site choices that never trend and still change the map.