
Have you noticed how quickly nuclear fuel went from a sleepy back-office topic to a national-security file sitting on the same desk as grid reliability and industrial policy? I have. One minute the conversation is about reactor restarts and small modular designs. The next, officials are saying the renaissance dies if the fuel does not show up. That is the uncomfortable truth hanging over the United States right now: uranium enrichment capacity is the bottleneck nobody wanted to talk about until the clock started ticking.
Why Washington Suddenly Wants Enrichment Yesterday
The commercial reactor fleet still needs enriched uranium. Advanced designs want something even pickier: HALEU, high-assay low-enriched uranium that sits above the usual commercial assay. Domestic production of that product has been thin for years. Imports filled the gap. Then geopolitics slammed the door partway shut, waivers kept the lights on, and now those waivers have an expiration date that energy officials insist they do not plan to stretch.
In my experience watching energy markets, governments rarely panic in public until the spreadsheet stops balancing. This time the spreadsheet is simple. If imported Russian-origin enriched material is truly off the table after early 2028, someone has to replace it with Western and preferably American molecules. Hope is not a procurement strategy. Plants, centrifuges, licenses, and workers are.
If we are going to have this nuclear renaissance, we are not going to be able to do it without fuel.
That line from a senior energy official is blunt on purpose. Reactors without fuel are expensive sculptures. Utilities without predictable supply sign fewer long-term power deals. Developers of advanced reactors cannot close financing if the fuel story is a shrug. So Washington is doing what capitals do when a strategic industry atrophied: write large checks and demand faster calendars.
The Waiver Clock Is The Real Deadline
After 2022, fuel prices jumped across the nuclear chain. A ban on Russian enriched uranium followed. The immediate scare that American reactors would miss deliveries faded almost as fast as it arrived, because waivers went out to brokers and utilities. That was the pragmatic move. It also created a false sense of calm.
Calm is expensive when it delays construction. Officials now say those waivers are meant to expire at the start of 2028, with no extension in the plan. Whether that posture holds is a political question. For investors and project teams, the working assumption has to be that 2028 is real. That is why the Department of Energy is leaning on developers to compress schedules that, left alone, would slip into the next decade.
Perhaps the most interesting aspect is how little slack remains. Licensing, supply chains for specialty metals, skilled technicians, and power for the plants themselves do not appear overnight. You can announce a facility in a press release. You cannot announce a trained centrifuge hall into existence.
Throwing Money At A Physical Problem
To close the capacity gap, federal money arrived in very large lumps. Awards on the order of $900 million apiece went to three names trying to stand up new enrichment: a historic American fuel company, a French industrial champion, and a secretive startup with Silicon Valley backing. Equal dollars. Very unequal public promises on annual output.
I find that contrast hard to ignore. Taxpayer capital is not infinite, even when the check looks round. If one bidder sketches a much larger annual volume for the same support, people will ask why the others are aiming so small. Fair question. Also an incomplete one, because licensed operations, existing hardware, and regulatory history still matter.
- Domestic fuel security after import restrictions tighten
- HALEU for advanced reactors that cannot run on standard LEU
- Commercial LEU for the existing gigawatt-scale fleet
- A manufacturing base that can expand instead of remaining a broker model
Those four needs overlap, but they are not the same product, not the same plant design, and not the same customer contract. Mixing them in one headline is how markets get confused.
The Incumbent With A License And A History
One of the award winners traces its corporate ancestry all the way back to the wartime program that first industrialized enrichment on American soil. For more than a decade after the last fully domestic enrichment plant shut down, the company lived more as a broker than a factory. It bought and sold material, kept relationships with European and other suppliers, and waited for policy to swing back toward onshore production.
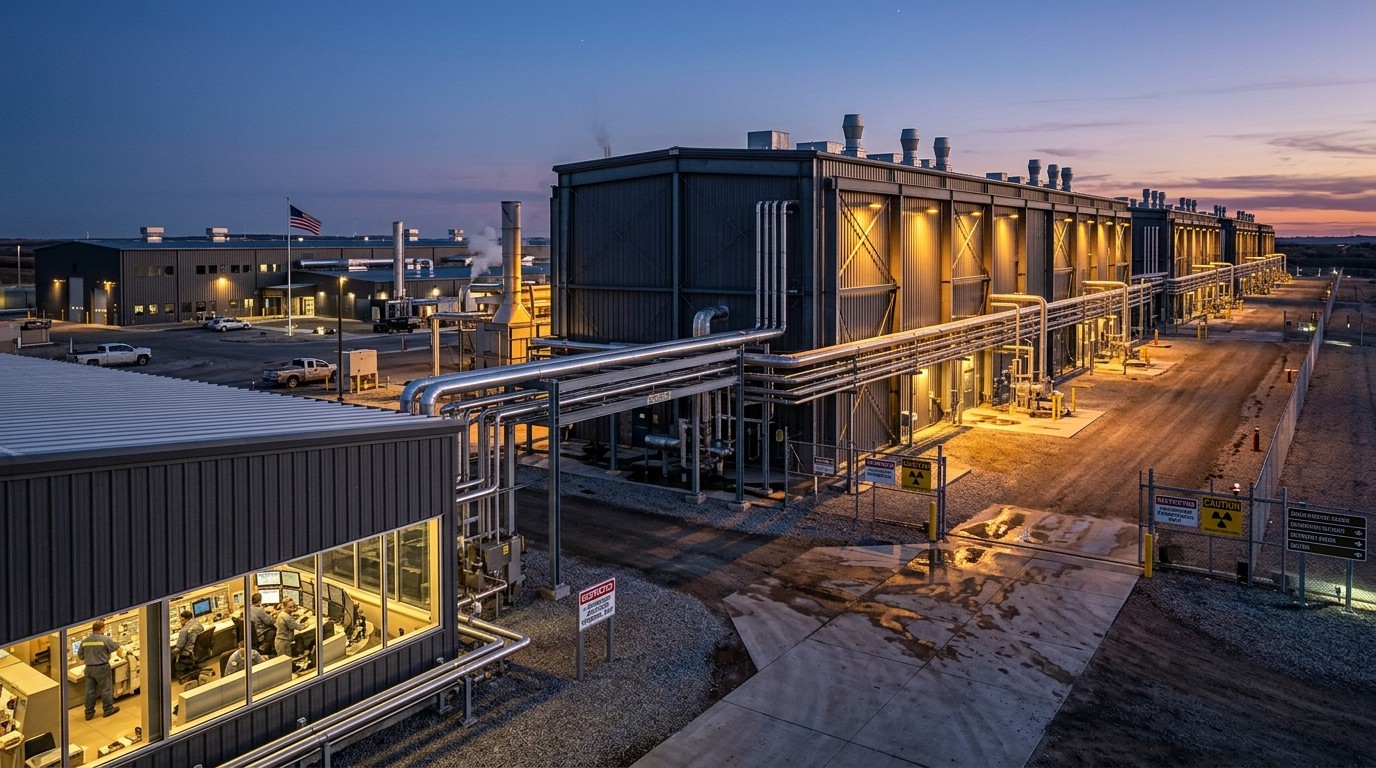
That waiting period was not wasted on paperwork. The firm is still the only U.S. site licensed by the nuclear regulator to produce HALEU-level material, and it has been making higher-assay product for roughly three years. That operational scar tissue matters. First-of-a-kind machines look elegant in a rendering. They look different after three years of vibration, maintenance, and assay control.
Recent offtake deals with advanced reactor developers point to deliveries by the end of this decade. The volumes discussed in public guidance remain modest next to the national gap: an initial annual rate measured in the low teens of metric tons, with fuller cadence after 2030 in earlier comments. First new capacity is still talked about around 2029. If 2028 is the hard stop for waivers, that calendar is tight. Painfully tight.
Credit where it is due. A licensed HALEU line is not a slide deck. Manufacturing expansion plans in the hundreds of millions of dollars show the company knows the government prefers an American-owned operator when it can get one. Preference, though, is not a substitute for tons delivered on time.
The French Industrial Answer
France did not forget how to enrich uranium. Its state-backed fuel group has fed a huge national reactor fleet for decades. It already tried a U.S. expansion once and walked away when post-Fukushima politics made nuclear unfashionable. That era is over. The company is back with a Tennessee project aimed at replacing Russian-origin imports for American customers.
Foreign ownership is a political bruise. Energy security speeches love the word domestic. Utilities love electrons that arrive. If a proven European operator can put Western-origin SWU into American cores faster than a greenfield startup, policymakers will swallow the flag math. They already did when they cut the check.
I’ve found that industrial execution often beats origin stories. Centrifuge halls are unforgiving. A team that has run them at commercial scale for years starts with fewer unknown unknowns. That does not make the Tennessee schedule automatic. Local permitting, labor, and grid interconnection can still chew months.
The Quiet Startup With Outsized Ambition
Then there is the newcomer almost nobody in the old nuclear village can describe in detail. Backed by a well-known technology investor and led by an engineer with launch-industry DNA, the company has stayed quiet on purpose. Traces of site work in Kentucky and talk of activity in California, Utah, and Washington State were about all the public record offered for a long time.
Reporting around the award process finally sketched a team mix of outsiders and nuclear veterans. It also surfaced a pointed comparison. When the founder first shopped the sector, the centrifuge approach used by the listed American incumbent did not look commercially competitive to him. That is a diplomatic way of saying he wanted a different machine.
The number that made people sit up was capacity. For the same nine-figure federal package, the startup was described as offering on the order of 355 metric tons of HALEU a year. The incumbent’s public figure for early annual output was about 12 metric tons, with later scale-up. Almost thirty times the ambition on identical headline dollars is the kind of ratio that does not stay in a footnote.
Does that 355-ton figure mean day-one production in 2029? The available write-ups do not nail that down. Still, the gap as printed is large enough that energy officials asking everyone to go faster looks less like theater and more like arithmetic.
The startup has also been tied to supply talks with the same advanced reactor names chasing the incumbent, plus at least one unnamed utility. If those contracts are real and the plant actually appears, commercial quantities stop being a slogan.
| Player type | Public strength | Open question |
| Licensed U.S. incumbent | HALEU license and operating years | Speed and scale of new tons |
| European industrial group | Decades of fleet-scale enrichment | U.S. build politics and timing |
| Well-funded startup | Very large capacity target | First commercial plant proof |
Why The Rivalry Feels Personal
Industry chatter keeps circling a frosty relationship between the listed American fuel firm and the startup. That is normal. Incumbents hate being told their machine is yesterday’s design. Founders hate being told nuclear is too special for outsiders. Both can be a little right and a little proud.
From a buyer’s chair, pride is irrelevant. Utilities and advanced reactor shops will sign with whoever can put compliant material on a truck. Preference for American ownership is real inside government procurement. Preference does not enrich a kilogram by itself.
If the incumbent wants to remain the face of American-owned enrichment, build times have to fall and published goals have to rise. That is not a hot take. It is what the award comparison already implies.
HALEU Is Not Just A Fancy Acronym
Standard light-water fuel lives in a familiar assay band. Many next-generation designs want fuel enriched well above that band but still below weapons-grade. That middle product is HALEU. Few Western plants make it in meaningful volume today. That scarcity is why a three-year operating record at higher assay is valuable, and why a 355-ton ambition, if delivered, would change the conversation overnight.
Without HALEU, some advanced reactor timelines are fiction. Developers can collect letters of intent all day. They cannot load a core with a press release. Fuel is the unglamorous twin of the reactor beauty contest.
- Secure feed material and conversion that is not trapped in a single geopolitically exposed route
- Stand up centrifuges that hold assay, reliability, and cost at commercial scale
- Finish licensing so product can actually leave the site
- Sign offtakes that survive construction delay and price swings
- Train a workforce that does not exist in large numbers in the United States right now
Miss any one of those five and the award money becomes a very expensive learning experience. Hit all five and the United States gets something it has not had in a long time: optionality.
What The Market Got Wrong After 2022
When prices ripped across the nuclear fuel cycle, a lot of commentary treated enrichment like a commodity ticker. It is not quite that. SWU is a service wrapped around classified-adjacent technology, export controls, and decade-long plant lives. Spot panic faded because waivers existed. Structural scarcity did not fade.
I keep coming back to that distinction. Traders can be right about a short squeeze and still miss the industrial rebuild. The rebuild is where the DOE is now pointing, a little impatiently.
There is also a habit of treating every advanced reactor announcement as incremental demand that will surely appear. Some will. Some will slip. Enrichment investors should underwrite the existing fleet first, then layer credible HALEU offtake on top. The fleet is already running. The experimental machines are not.
Policy Preference Versus Physics
Washington would rather see American-owned plants fill the gap than foreign-owned ones. Understandable. The last purely domestic enrichment complex went dark more than ten years ago. Rebuilding that muscle is a strategic goal, not a branding exercise.
Physics does not care who owns the shares. A kilogram is a kilogram if the assay, contamination limits, and shipping papers check out. If the American-owned plan arrives late and small, officials will still need Western-origin supply from allies. That is why a French project sits in the same award class as the hometown names.
In my view, the grown-up policy is both/and for a few years, then a hard look at who actually poured concrete. Nationalism without tonnage is just a speech.
Equal public money for wildly different annual capacity claims is the kind of comparison that forces every board to defend its timeline.
Paducah, Tennessee, And The Map Of A Comeback
Geography still matters in this industry. Older gaseous diffusion sites left behind skilled towns, transmission, and a kind of institutional memory even after the machines stopped. Kentucky’s Paducah name keeps coming up in prep work for the startup. Tennessee is the French second attempt. Other Western states appear in the rumor mill for supporting operations.
Communities that once lived on enrichment want the jobs back. They also remember boom-and-bust cycles. A serious project needs more than a ribbon. It needs a multi-year hiring plan and a reason for technicians not to leave for data centers and battery plants that pay well and explain easier at a barbecue.
That labor competition is under-discussed. Nuclear manufacturing does not win on vibes. It wins on wages, training pipelines, and a sense that the plant will still be there in fifteen years.
Contracts Are Starting To Look Like Demand
Paper offtakes used to be cheap. Lately they look a little more specific. The licensed American producer has pointed to agreements with several advanced reactor developers targeting late-decade deliveries. The startup has been described as signing with overlapping names plus a utility that has not been identified in public summaries.
Overlapping customers are not a scandal. They are a hedge. Developers will dual-source if they can. They remember what single-source fuel risk feels like. For enrichment companies, overlapping names mean the fight is not only versus imports. It is versus each other for the first credible Western HALEU barrels.
Watch the delivery windows, not the logos. End of decade is close if you still need to pour a hall.
What Faster Actually Means On The Ground
When energy officials tell companies to accelerate, they are not asking for a new font on the Gantt chart. They are asking whether long-lead equipment can be ordered before every permit is framed on the wall. Whether modular construction can shrink the calendar. Whether regulators can review in parallel instead of in a single-file line.
None of that is free of risk. Parallel work spends money that might be stranded. Serial work misses the waiver cliff. Pick your poison. The DOE’s public posture suggests it would rather see money spent early than see 2028 arrive with empty promises.
I’ve found that the projects that finish in heavy industry are usually the ones that treat schedule as a design constraint, not a press-kit decoration. Enrichment is heavy industry wearing a policy suit.
Investors Should Separate Three Stories
There is a listed-company story about manufacturing expansion and a rare HALEU license. There is an allied-industrial story about a second U.S. attempt by a company that already knows how to run enrichment at fleet scale. There is a venture-style story about a team that thinks the incumbent machine set is not the winning cost curve.
Those stories can all be true in the same year and still produce very different equity outcomes. Capacity claims need discounted timelines. Licenses need discounted construction risk. Foreign ownership needs discounted political risk. None of those discounts is zero.
Simple filter for fuel headlines:
  1. Is this LEU for the living fleet or HALEU for machines not yet built?
  2. Is the date before or after the waiver cliff?
  3. Is the volume measured in demonstration kilograms or commercial tons?
  4. Who actually owns the plant when politics get loud?
Use that filter and half the noise falls away. The other half is still worth reading, because this market moves on a handful of plants, not on a thousand tickers.
The Renaissance Depends On Boring Machines
Nuclear advocates love renderings of sleek small reactors. Fair enough. The unsexy truth is that the renaissance is a fuel-cycle rebuild first. Conversion, enrichment, deconversion, fabrication. Miss enrichment and the rest of the chain kinks.
That is why a demand from energy officials to go faster is more than a news-cycle nudge. It is an admission that the policy goal and the physical calendar are not yet friends. Awards of nearly a billion dollars each were the opening bid. Speed is the follow-up memo.
Will 2028 really be clean of extensions? I would not bet my house on political purity. I would also not underwrite a plant on the assumption that waivers last forever. The conservative plan is to treat the date as firm and be pleasantly surprised if diplomacy buys extra innings.
A Few Things That Still Need Saying Out Loud
First, producing a little HALEU and producing a lot of HALEU are different businesses. Demonstration success is not a plant. Second, centrifuge design arguments will continue because cost per SWU decides who still exists in 2035. Third, allied supply is not the enemy of American reindustrialization if the alternative is a dark reactor.
Fourth, communities hosting these plants deserve straight talk on schedule. Over-promising revival and under-delivering is how you poison the next permit. Fifth, advanced reactor customers should keep dual-track fuel strategies until metal exists, not just term sheets.
- Schedule risk still dwarfs commodity-price risk for new halls
- Licensed operating history is a genuine asset, not nostalgia
- Capacity claims need the same skepticism as resource estimates in mining
- Workforce and power supply can stall a beautiful design
- Policy preference will fade if trucks do not move
Where This Leaves The Next Eighteen Months
Watch hiring pages more than keynote slides. Watch long-lead procurement. Watch whether offtake dates slip in quiet amendments. Watch whether officials keep repeating that 2028 waivers will not be rolled. Repetition is a tell.
If the startup’s large-volume target survives contact with engineering, the competitive map changes. If the licensed incumbent compresses its ramp and lifts its sights, it keeps the leadership argument. If the French project clears local hurdles faster than expected, utilities will not wait for a patriotic ribbon-cutting.
The call from the Department of Energy is not mysterious. Build enrichment faster, because fuel is the part of the nuclear comeback that cannot be sketched in software. Three well-funded answers are on the table. Only delivered tons will decide who actually answered.
And that, more than any slogan about a renaissance, is the plot from here to the end of the decade.