

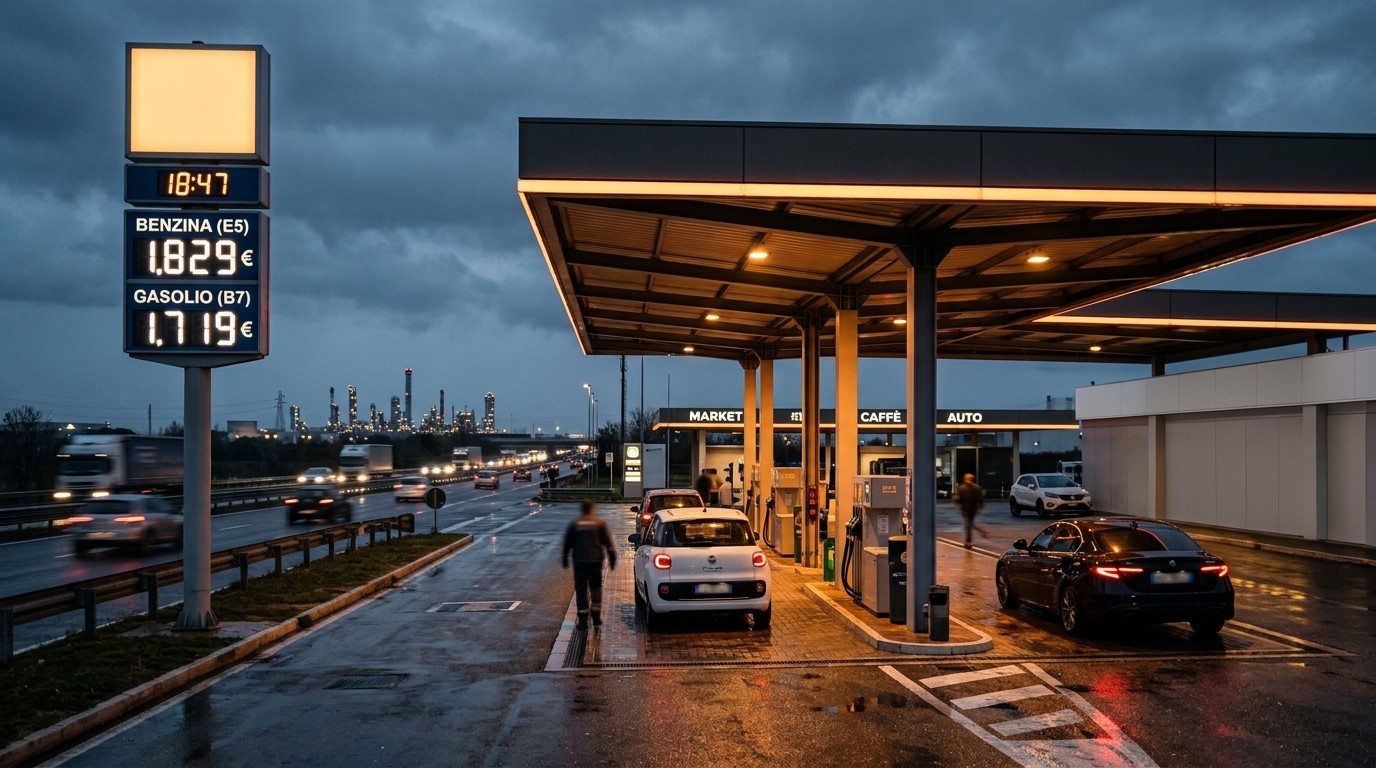

Have you noticed how a single price board at a motorway station can tell you more about Europe than a stack of policy papers? I have. Last week I kept glancing at pump numbers the way some people check weather apps, and the story was the same almost everywhere: refined fuel is getting tighter, costs are creeping, and drivers are the ones who feel it first. Then an Italian energy major decided to put a lid on the pain, at least for a while.
Why A Temporary Pump Cap Suddenly Matters
Starting September 28, Eni will cap fuel sold through its Enilive service stations. Diesel is limited to €2.19 per liter. Petrol is limited to €1.99 per liter. The company says those ceilings sit roughly €0.17 per liter below current average pump levels. That is not pocket change if you fill a tank twice a week.
The measure is slated for 30 days at first. It could stretch through the end of 2026 if market conditions and supply trends stay ugly. In my experience, energy firms rarely volunteer a cap unless two things line up: political heat at home, and a wholesale market that has already started to bite.
Eni tied the move to excise-tax relief already in force in Italy. The stated aim is simple enough. Soften the hit on households and businesses. Keep recommended pump prices from tracking every spike in international product markets. Since March, the company says it has already been absorbing part of the increase rather than passing the full wholesale jump straight to drivers.
When refined-product availability tightens and regional capacity shrinks, the pump becomes the last visible pressure valve.
The Refining Crunch Behind The Price Board
Europe did not wake up last Tuesday and discover it had fewer refineries. The squeeze has been building for years. Nearly 30 European plants have closed over the past decade and a half. Each closure removes a buffer. Each remaining site has to work harder when imports wobble or geopolitics knocks a shipping lane off balance.
That is the unglamorous core of this story. Crude can be available. Finished diesel and gasoline can still be scarce. Refining is the missing middle. If you take capacity out and then ask the system to absorb a disruption, prices do what prices do. They rise until someone, somewhere, decides the political cost of that rise is too high.
I keep coming back to a plain fact. A market that once had spare barrels of conversion capacity now leans on imports and on a thinner set of surviving plants. That is fine in a calm year. It is not fine when product balances tighten across the continent at the same time.
What Drivers Will Actually See At Enilive
Caps sound neat on a press note. On the forecourt they are messier. A ceiling only matters if the posted price would have gone higher. If wholesale values ease, the cap can look generous. If they keep climbing, the retailer eats the gap.
Eni framed the diesel and petrol limits as a relief step, not a permanent price freeze. That distinction matters. A freeze pretends the wholesale market does not exist. A cap admits it does, then tries to shield the customer for a defined window.
- Diesel ceiling: €2.19 per liter at Enilive sites
- Petrol ceiling: €1.99 per liter at Enilive sites
- Gap versus recent averages: about €0.17 per liter
- First window: 30 days, with a possible run through late 2026
Will every station in Italy match those numbers? Of course not. This is a company-level recommended structure for its own retail network. Independent sites, other brands, and motorway operators can still post whatever their contracts and margins allow. That is why a cap can feel local even when the shortage is continental.
How Wholesale Costs Leak Into Everyday Driving
Pump prices are a stack. Crude is only the bottom layer. Then come refining margins, freight, blending specs, taxes, and the retailer’s own spread. In Europe, taxes already take a large bite. When the product layer on top of crude jumps, the remaining room for a retailer shrinks fast.
Perhaps the most interesting aspect is how uneven that stack has become. One week diesel cracks look firm while gasoline looks sleepy. Another week the two flip. A national cap has to pick numbers that survive both moods. Eni’s pair of ceilings tries to do that without pretending the two fuels move as twins.
I have found that people talk about “oil prices” when they really mean the finished barrel they put in a van. Those are not the same market. A refining crunch is a product-market story first. The crude tape can look calm while diesel still feels expensive at the nozzle.
Why European Capacity Keep Shrinking
Ask ten planners why plants close and you will hear ten overlapping answers. Aging assets. Thin margins in quiet years. Tougher environmental rules. Competition from larger, newer complexes outside the region. A policy push toward lower-carbon fuels that makes a conventional site look like a stranded bet.
None of those reasons is silly on its own. Together they produce a map with fewer dots. Fewer dots means less surge capacity. Less surge capacity means a tighter market when a unit trips, a strike hits, or a cargo is delayed.
Eni is not pretending the old map can be redrawn overnight. It is keeping refining-related work alive in Italy through Enilive, including biorefineries in Venice and Gela, plus a transformation of the Livorno industrial site and other domestic facilities. The bet is hybrid. Keep some processing on home soil. Shift more of the slate toward biofuels and lower-carbon products.
You can close a refinery in a year. You cannot rebuild the optionality it provided in a quarter.
Biofuels, Conversion, And The Italian Industrial Map
Venice and Gela are useful symbols. They show a company trying to keep kilns warm while changing what goes through them. A biorefinery is not a magic replacement for a full-conversion oil complex. It can still hold skilled jobs, permits, pipelines, and a measure of domestic processing that would otherwise vanish.
Livorno’s transformation fits the same logic. Keep the site. Change the mission. Argue that Italy should not outsource every molecule and then act surprised when imports get pricey. I am sympathetic to that argument even when the chemistry is slower than the slogans.
Lower-carbon products will not erase diesel demand next month. Fleets still roll. Heating seasons still arrive. Agriculture still needs middle distillates. The transition and the crunch are happening in the same calendar, which is exactly why a retail cap can look like a bridge rather than a solution.
Geopolitics, Imports, And A Thinner Safety Net
European fuel balances now depend more on cargoes that have to cross water. That is not automatically a problem. It becomes one when several shocks arrive together. A disrupted supply route. A sanctioned barrel that used to find a home. A rival region that suddenly wants the same diesel cargo you were counting on.
Last week’s chatter about a possible U.S. export restraint was a reminder, not a verdict. Even talk of an export ban can change the tone of the Atlantic product trade. U.S. diesel can soften at home while European prices stay firm. That kind of decoupling is awkward for importers who treated the two basins as loosely connected.
Does that mean Italy is about to run dry? No. It means the buffer is thinner, the option set is smaller, and a retailer with a national footprint feels pressure to do something visible. A cap is visible. Investments in biorefineries are slower and harder to photograph.
| Pressure Point | What It Does To Pumps | How Long It Lasts |
| Lost regional refining capacity | Raises baseline product tightness | Structural, years |
| Import or freight disruption | Adds sudden spikes on top | Weeks to months |
| Tax relief plus retail cap | Blunts the visible retail jump | Policy window |
| Biofuel and site conversion | Keeps some domestic processing | Multi-year build |
Who Pays When A Company Absorbs The Gap
Someone always pays. If recommended pump prices stay below wholesale-plus-tax reality, the difference sits on the retailer’s books. That can be a marketing cost. It can be a political cost. It can also be a margin that later has to be recovered when the cap expires.
Eni says it has been eating part of the increase since March. That claim is easy to respect and hard to audit from the outside. What we can say is this. A 30-day cap is a defined risk. An open-ended cap through 2026 is a different animal. Markets move. If product cracks stay wide, the bill grows.
Households and small firms still benefit in the window. A courier, a farm, a heating-oil adjacent business that watches diesel like a hawk will notice €0.17. So will a family that drives between cities because the train timetable is a joke. Relief is relief, even when it is temporary.
The Awkward Politics Of Energy Affordability
Governments like cheap fuel until they need expensive fuel to fund the budget. Retailers like free pricing until a minister starts talking about “excessive spreads.” Drivers like a cap until the station across the road quietly limits hours or grades.
Italy’s existing excise relief gave Eni a political hook. The company could present the cap as a partner move rather than a solo discount war. That framing helps. It also ties the retail gesture to a tax setting that can change.
I do not buy the idea that a cap “fixes” a refining shortage. It does not add a hydrocracker. It does not summon extra gasoil from thin air. What it can do is buy time and keep the social temperature down while the product market works through a tight patch.
Retail Networks As Shock Absorbers
Large integrated groups have a peculiar advantage here. They sit on both sides of the fence. Upstream and refining can be having a decent year while the retail banner is asked to look kind. That internal offset is not available to a pure forecourt operator living on a thin cents-per-liter spread.
Enilive is the public face of that trade-off. The brand has to look fair on the high street while the industrial system behind it is being reshaped. If the cap is extended toward 2026, the brand becomes part of energy policy whether anyone admits it or not.
Smaller dealers will watch the experiment closely. If customers start routing trips to capped sites, traffic migrates. If wholesale stays elevated, those same dealers cannot copy the gesture without help. That is how a corporate cap can quietly redraw local competition.
Diesel Versus Petrol: Two Markets, One Headline
Diesel is the workhorse. It moves goods. It powers a lot of older fleets. When middle distillates tighten, the pain shows up in freight invoices and farm budgets, not just weekend drives.
Petrol is more consumer-facing in many cities, especially as some drivers shift toward hybrids or smaller engines. A €1.99 petrol cap is easy to remember. A €2.19 diesel cap is the one logistics managers will circle in a notebook.
Setting both ceilings at once is a communications choice as much as a market choice. It tells the public the company sees the whole forecourt, not just the fuel that photographs well in a city-center campaign.
Simple pump stack:
  Product cost
+ Freight and logistics
+ Taxes and duties
+ Retail operating spread
= What you pay
A cap only squeezes the last line.
Could The Cap Last Into 2026?
Extension is the real cliffhanger. Thirty days is a campaign. Twenty-seven months is a regime. Eni left the door open and tied it to “fuel-market conditions and supply trends.” That phrase can mean almost anything, which is useful if you want flexibility and annoying if you want certainty.
Watch three things. First, European product inventories and refining runs. Second, the tone of Atlantic diesel trade, including any policy noise around exports. Third, whether Italian tax relief stays in place. If any of those three break the wrong way, the cap either becomes expensive or becomes a political necessity.
In my view, the honest base case is a rolling review, not a dramatic unveiling of a multi-year freeze on day 31. Markets hate drama. Retail networks hate surprises even more.
What This Signals For The Wider European Fuel Trade
Italy is not an island in product terms. A cap in one large network does not reset Rotterdam. It does, however, advertise a problem that other capitals already know. Conventional capacity is thinner. Import dependence is higher. Voters still drive.
Other majors will not rush to photocopy the same numbers. Their tax systems differ. Their retail mix differs. Their exposure to diesel versus gasoline differs. Still, the template is now public. Visible relief plus a reminder about closed refineries. That pairing will travel.
Investors reading the same news will split it in two. Downstream retail looks constrained. Conversion and biofuel projects look like the strategic answer the company wants to talk about instead. Both readings can be true on the same day.
Practical Takeaways If You Drive Or Dispatch In Italy
Do not treat the cap as a nationwide law. Treat it as a branded ceiling at Enilive sites for a defined stretch of time. Compare neighboring boards. Watch whether discounts on the shop side quietly fade while the pump looks cheaper. Retailers have more than one lever.
- Note the start date and the 30-day review point.
- Track diesel separately from petrol; they will not move as twins.
- Assume independent stations may not match the ceiling.
- Plan fleet fills around network coverage, not headlines.
- Revisit the numbers if tax relief changes.
None of that is glamorous. Filling a tank never is. It is still how most of the real economy meets the refining system.
A Longer View On Transition Versus Tightness
Europe wants lower-carbon fuels and fewer old plants. Europe also wants affordable mobility. Those wishes collide in the middle distillate barrel. Close capacity too fast and the import bill grows. Keep dirty assets forever and the climate file looks like theater.
Eni’s Italian projects try to walk that line. Keep processing. Change feedstock. Argue that domestic industry still has a role. I find that more serious than slogans about “just switching” as if molecules were software updates.
The cap is the short chapter. The site conversions are the long one. Readers who only remember the €1.99 number will miss the industrial point. Readers who only talk about biorefineries will miss the fact that people still have to get to work next Tuesday.
The Human Texture Of A Technical Market
Energy writing can get abstract in a hurry. Cracks, runs, utilization, barrels per day. Then you watch a parent do mental arithmetic at a pump on a Sunday night and the abstraction collapses. Affordability is not a spreadsheet tab. It is whether the extra euros wreck the month.
That is why a cap, even a modest one, gets attention. It translates a refining map into a number a driver can read without a briefing note. I would rather see spare capacity than a ceiling. Spare capacity is not what Europe currently has in abundance.
So we get the second-best tool. A temporary lid. A reminder that almost 30 plants are gone. A promise that some Italian sites will keep working under a different flag. Imperfect. Human. Very European, if I am allowed a little editorial shrug.
Questions The Next Month Should Answer
Will wholesale product values ease enough that the cap looks symbolic? Will they stay firm enough that Enilive’s margin comment from March starts to look expensive? Will other networks feel forced to answer? Will the extension talk fade after the first review?
Those are not trick questions. They are the difference between a one-off gesture and a new way of managing retail fuel in a tighter continent. I will be watching the boards, not the slogans.
A price cap can soften a season. Only capacity, imports, and policy can shape the decade.
Closing Thoughts Without The Usual Clean Bow
Eni’s move is easy to summarize and hard to dismiss. Diesel at €2.19. Petrol at €1.99. About seventeen cents of daylight versus recent averages. Thirty days on the clock, with a possible road all the way to the end of 2026. Behind those figures sits a thinner European refining system, a company that says it has been absorbing costs since March, and an industrial plan that leans on biorefineries and site conversions rather than a return to the old map.
If you wanted a neat ending, I do not have one. Tight product markets rarely offer neat endings. They offer choices. Absorb the cost. Pass it on. Cap it for a while. Build something slower that might help later. Italy is watching one company try a mix of the last two. The rest of Europe should pay attention, not because the same numbers will appear on every board, but because the shortage those numbers are answering is not uniquely Italian.
Fill up if you need to. Read the small print on how long the lid lasts. And keep an eye on the plants that still run, because that is where this story actually lives when the campaign lights dim.



