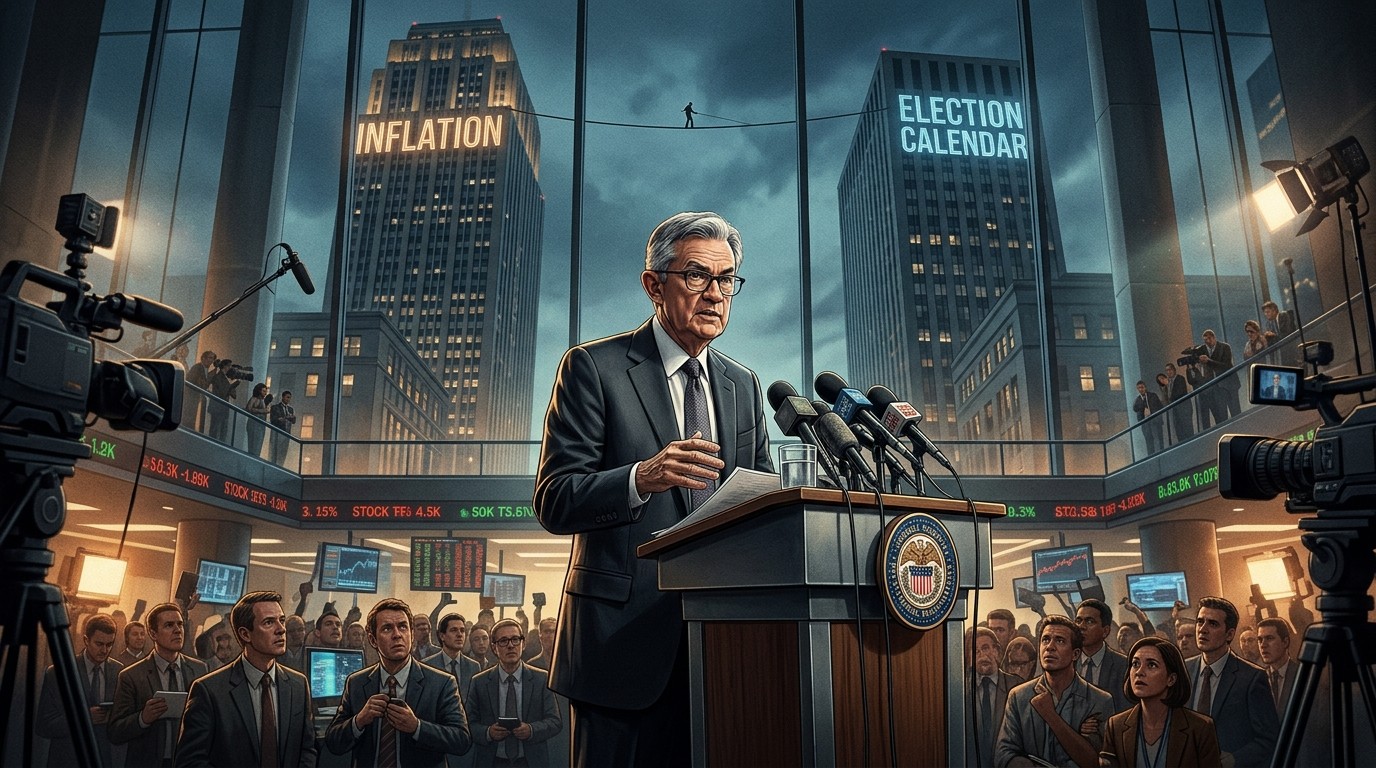

Have you ever watched someone try to walk a tightrope while the wind keeps shifting direction? That is exactly the feeling hanging over the latest Federal Reserve decision. The Chair walked into the press conference knowing every word would be dissected for signs of political influence. Inflation numbers came in warmer than hoped, yet the committee still chose to hold rates steady. The calendar shows midterm elections just days away. Suddenly the official explanations feel a little thinner than usual.
Why This Particular Pause Feels Different
For months the message stayed consistent. Officials kept stressing the need for a timely return to the two percent inflation target. Then September data arrived hotter than expected. Under normal circumstances that print might have tilted the scales toward another increase. Instead the committee opted for patience. Markets had already priced in a hold, so the decision itself surprised almost no one. The real test came in the explanation that followed.
I have followed these meetings for years and the tone this time carried an extra layer of careful wording. Every sentence seemed measured against the risk of appearing political. The Chair needed to convince the public that the pause reflected economic judgment alone. At the same time the proximity of the election made that claim harder to sell. One well-timed question from the press corps could have forced an awkward moment into the open.
The Calendar Problem Nobody Wants to Name
Less than a week separates the decision from the midterm vote. Cost of living sits near the center of campaign conversations. A rate hike right now would have signaled that inflation remains stubborn. It also would have tightened financial conditions further into an election focused on affordability. Acknowledging that reality would undercut the long-standing claim of complete independence. So the official line stays focused on data dependence and the value of waiting for more information.
The statement itself added a familiar phrase about the accumulation of more information helping determine the appropriate stance. That language gives the committee room to move later without looking inconsistent. Yet every one of those arguments existed a month ago. The only new element is the calendar. That fact sits in the background of every answer given during the press conference.
A decision to leave rates unchanged less than a week before the midterm elections that goes unexplained would only encourage thoughts that policy is being driven by considerations other than employment and inflation.
That observation from a well-known market economist captures the core tension. Silence would have been worse. A long answer about optionality and incoming data buys time. Still, the more the Chair leans on a December move, the clearer it becomes that the only real barrier today was the timing of the vote.
What Changed Inside the Committee
Two members dissented. One of those names carries its own history of independent thinking. The other joined in the call for action. Interestingly, a couple of officials who had previously favored a different path returned to the majority. That shift reduced the appearance of deep division. It also made the hold decision look more collective than it might have otherwise.
In my view the reduced number of public disagreements helps the Chair’s narrative. A broader split would have invited more questions about whether politics played any role in the final tally. With fewer dissenters the story becomes easier to present as careful consensus. Whether that consensus reflects pure economic assessment remains the question many observers still ask.
Markets already performed some of the tightening work. Pricing for a December increase stayed firm. That reality lets the committee claim it is guiding toward further action rather than avoiding it. The argument sounds reasonable on the surface. Dig a little deeper and the same tools were available last month. The difference is the date on the calendar.
The Familiar Playbook Makes Another Appearance
Expect the usual sequence of explanations. One elevated inflation print does not equal a new trend. Policy operates with long and variable lags. The committee prefers to see the next round of data before adjusting the path. December remains fully priced, so the Fed can argue it is preparing the ground for a hike rather than refusing one. Each of those points has appeared in previous statements. Their reappearance feels almost automatic.
I find the lag argument particularly convenient. It is true that monetary policy works with delay. Yet the same lag existed when officials were hiking aggressively. Selective application of the concept raises eyebrows. Still, it remains a standard line that is hard to disprove in real time. The data-dependence claim serves a similar purpose. It sounds disciplined while preserving maximum flexibility.
- One hot print does not establish a lasting trend
- Policy effects arrive with long and variable lags
- October numbers will provide additional clarity
- December pricing already reflects market expectations
Those four points form the core of the public defense. They are difficult to attack directly. They also fail to address the timing coincidence that everyone notices. The more the Chair repeats them, the more the calendar itself becomes the unspoken subject of the conversation.
How Hard Will the Chair Lean on December
This is the real tell. If the press conference features strong pre-commitment language about the next meeting, the pause starts to look more like a temporary pause for political cover. If the language stays vague and fully data-dependent, the committee preserves deniability. Either path carries risk. Explicit guidance makes the calendar problem more obvious. Soft language leaves markets guessing and risks a sharper reaction later.
Perhaps the most interesting aspect is how little new information the Chair can actually point to between now and December. Another inflation report will arrive. Employment numbers will update. Financial conditions may shift. Yet none of those releases change the fundamental political calendar that shaped today’s decision. The gap between what is said and what is understood remains wide.
Investors have grown skilled at reading between the lines. They watch not only the words but the emphasis and the body language. A defensive tone invites more scrutiny. A confident tone risks looking disconnected from the political reality surrounding the meeting. Walking that line requires careful balance.
Market Reaction and the Work Already Done
Equity and bond markets largely shrugged at the formal decision. Pricing had already adjusted. In that sense the market performed the tightening that the committee chose to postpone. That dynamic allows officials to claim they are following rather than leading. It also reduces the immediate cost of holding steady. The risk arrives later if the next data confirm the hotter inflation path and the committee then feels forced to move more aggressively.
I have seen this pattern before. When markets do the heavy lifting, policymakers gain short-term breathing room. The longer-term credibility question stays open. If the public begins to believe that election calendars influence the path of rates, the independent status of the institution takes a quiet hit. Rebuilding that perception takes time and consistent action that looks clearly non-political.
The Question That Could Define the Press Conference
Somewhere in the room a reporter is preparing the sharpest version of a simple question. What will the committee know in December that it does not already know today, other than the election result? The answer will almost certainly circle back to data dependence and the value of optionality. The length of that answer may matter more than its content. A short, confident reply suggests the Chair is comfortable with the narrative. A longer, more technical reply may signal underlying discomfort.
In my experience the best questions in these settings are the ones that force officials to confront the obvious without allowing easy escape. The calendar is obvious. Pretending it is not part of the conversation only draws more attention to it. The Chair’s task is to acknowledge the timing without admitting any influence. That distinction is subtle and easy to blur under live questioning.
The reduced number of dissents helps on this front. A broader split would have given the press more angles to explore. With most of the committee aligned, the story stays focused on collective judgment rather than internal political calculation. Still, two dissenters keep the door open for continued debate inside the building.
Looking Ahead to the Next Data Cycle
October inflation numbers will arrive before the next meeting. Employment reports will update. Financial conditions may ease or tighten depending on how markets interpret the current guidance. Each of those releases will be examined for clues about the December path. The committee has already signaled that more information will help determine the appropriate stance. That language now becomes the measuring stick for whatever comes next.
If the next inflation print cools, the pause will look prudent in hindsight. If it stays elevated, the decision will look more like a missed opportunity to stay ahead of the problem. Either outcome will be filtered through the political lens created by the current timing. That is the lasting consequence of holding rates steady so close to an election focused on prices.
Policy makers prefer to operate with maximum flexibility. The current environment reduces that flexibility. Every future move will be examined for residual political calculation. Restoring a cleaner separation between economic assessment and electoral calendars will require several meetings that look clearly data-driven and free of convenient timing.
Why Independence Still Matters to Markets
Investors price policy based on the belief that decisions follow economic rather than political logic. When that belief weakens, risk premiums can rise. The current episode has not yet produced a major shift in those premiums. The danger lies in the accumulation of similar moments. One pause near an election can be explained away. A pattern of convenient timing becomes harder to dismiss.
I have found that market confidence in central bank independence is easier to maintain than to rebuild. Once participants begin to assign political motives to rate decisions, the interpretation of every future statement changes. Guidance that once looked technical starts to look strategic. That shift can alter the effectiveness of policy communication itself.
The Chair understands this risk. The careful language and the emphasis on incoming data are designed to protect the institutional reputation. Whether the effort succeeds depends less on today’s words and more on the sequence of decisions that follow over the next several meetings.
Practical Implications for Investors Right Now
Portfolio positioning already reflects a high probability of a December move. That pricing limits the immediate upside from any surprise hawkish turn in the press conference. At the same time, a softer-than-expected tone could ease financial conditions further and support risk assets in the near term. The key variable remains the strength of the inflation data still to come.
- Watch the December probability embedded in futures markets for shifts after the press conference
- Monitor the next inflation release for confirmation or contradiction of the recent hotter trend
- Assess whether financial conditions ease or tighten in response to the guidance
- Evaluate the tone of subsequent speeches from other committee members for signs of growing or shrinking consensus
Those four checkpoints will shape the path between now and the next formal decision. None of them removes the calendar from the conversation. They simply give investors a structured way to track how the committee manages the residual political questions.
The Broader Context of Credibility
Central banks operate on a foundation of perceived competence and independence. Both elements face pressure when inflation proves sticky and when decisions align with electoral calendars. The current episode tests the second element more than the first. The committee has already demonstrated willingness to hike when data demanded it. The open question is whether it will continue to do so when the political cost is higher.
Perhaps the most useful way to view the situation is as a stress test of communication strategy. The official narrative emphasizes patience and data. The market narrative quietly notes the election date. Bridging those two stories requires consistent follow-through that looks immune to political convenience. The next few meetings will reveal whether that consistency holds.
In the end the Chair faced an unenviable task. Holding rates steady was the path of least immediate resistance. Explaining the decision without acknowledging the calendar required careful language and disciplined delivery. The market has already moved on to the next data points. The institutional reputation will be judged over a longer horizon.
What Success Looks Like from Here
A successful outcome for the committee would include cooler inflation readings, a measured December increase if data support it, and a gradual fading of the political questions that surround today’s decision. An unsuccessful outcome would feature continued elevated inflation, delayed action that looks increasingly political, and a lasting shift in how markets interpret every future statement.
The difference between those two paths will not be decided in a single press conference. It will emerge from the sequence of choices that follow. For now the committee has bought itself time and preserved flexibility. The cost of that time will become clearer only after the election dust settles and the next round of economic data arrives.
I remain curious to see how hard the Chair leans on the December meeting in the remaining answers. The stronger the pre-commitment, the more the calendar becomes the central character in the story. The softer the language, the longer the ambiguity persists. Either choice carries consequences that extend well beyond the current meeting.
Investors and citizens alike will keep watching. The tightrope remains in place. The wind has not stopped shifting. The next steps will determine whether the institution walks safely to the other side or finds itself explaining the same coincidence all over again.
Final Thoughts on the Balancing Act
Monetary policy rarely occurs in a vacuum. Political calendars exist. Inflation data arrive on their own schedule. The art of central banking lies in navigating both realities without letting one dominate the other in the public eye. Today’s decision tested that art under unusually bright lights.
The official explanation will satisfy some observers and leave others unconvinced. That split is inevitable. What matters more is the pattern that develops from here. Consistent, data-driven action over the coming months can restore confidence. Convenient timing that repeats itself will erode it. The committee holds the tools to shape either outcome.
For anyone watching the process, the lesson is straightforward. Listen carefully to the words. Watch the subsequent decisions even more carefully. The gap between the two will reveal whether the pause was simply prudent patience or something more closely tied to the calendar. That gap is where the real story continues to unfold.