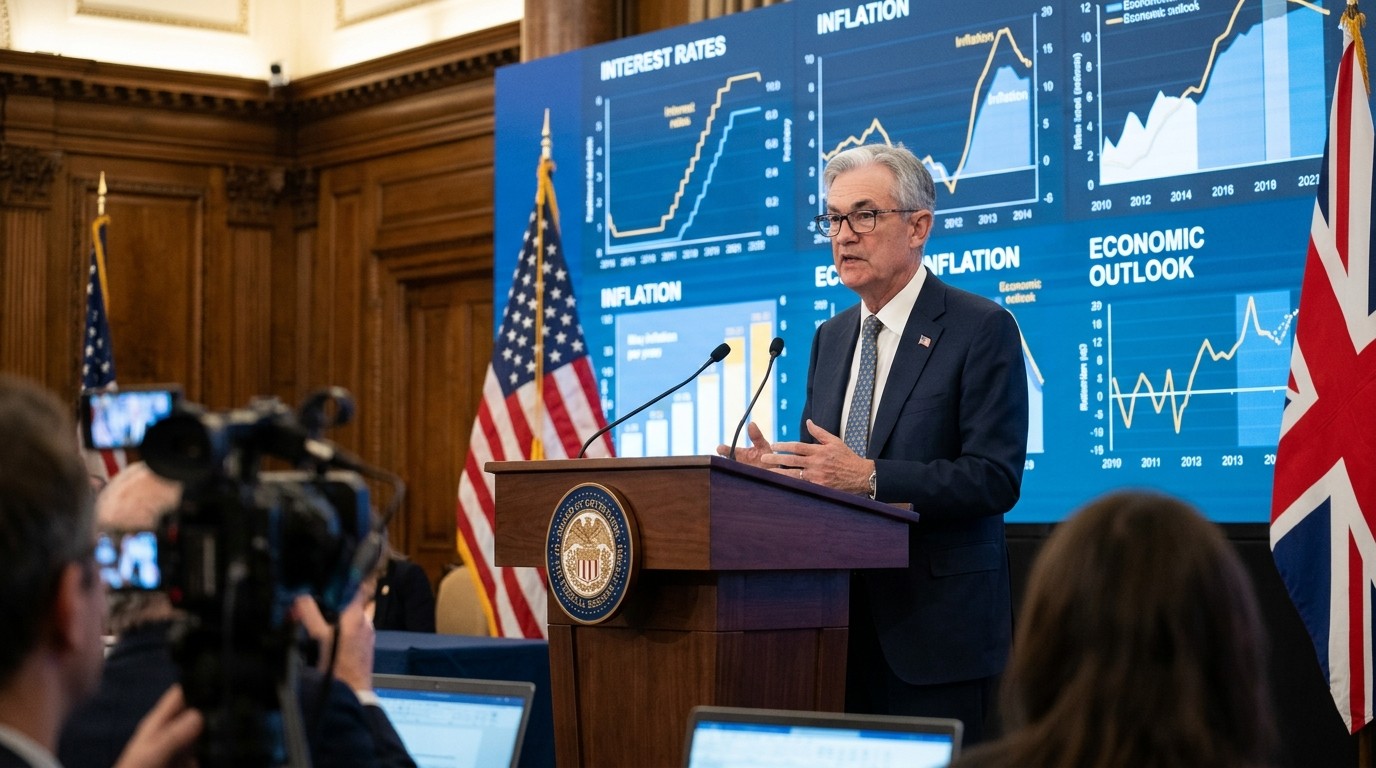

Have you ever watched the markets hold their breath waiting for a single speech from a central banker? That is exactly what happened this week when a key Federal Reserve voice made it clear that a December rate increase is very much on the table. The comments landed with weight because they came at a moment when investors had started to wonder whether the pause in October might stretch longer than expected. Suddenly the conversation shifted back toward tightening, and the possibility of an even larger move if the next inflation numbers refuse to cooperate.
Why December Suddenly Looks Like a Live Meeting Again
The policymaker in question stated plainly that he is leaning toward a quarter-point rise in December. He went further and said that if the upcoming inflation data come in hotter than anticipated, a half-point increase should be seriously considered. That kind of language is not casual. It signals that the bar for another hold is higher than many had assumed after the October decision.
What makes the remarks especially notable is the emphasis on credibility. The central bank had already guided markets toward additional firming. Failing to deliver, according to this view, would cause expectations to unwind quickly and effectively loosen policy at the wrong time. In other words, the timing of individual moves matters less than making sure the overall path is delivered within a reasonable window.
The Credibility Argument That Changed the Tone
I have followed these policy discussions for years, and the credibility point rarely gets stated this bluntly. The idea is straightforward yet powerful. Once officials have signaled that further rate increases are likely, markets build that path into asset prices. If the increases never materialize, rates fall almost immediately. That unintended easing would work against the goal of bringing inflation back to target.
While the precise timing of the hikes does not matter, ensuring that the promised hikes are implemented in a reasonable period of time does.
That single sentence captures the core of the argument. It also explains why a larger move might be needed if data deteriorate. A modest quarter-point step in the face of stronger inflation readings could look insufficient and raise fresh doubts about resolve. The preference, at least from this corner of the committee, is to avoid that risk altogether.
What the October Hold Actually Signaled
The decision to leave rates unchanged in October was never presented as a permanent pause. Officials stressed that more information would help clarify the appropriate path. Two members dissented, preferring action at that meeting, which already showed that views inside the committee were not uniform. The latest comments reinforce that the door remained open the entire time.
Markets had priced in a high probability of a December move even before these remarks. After the speech, the odds of a half-point increase stayed near zero, but the chance of a quarter-point step held firm. That pricing suggests investors still see the larger option as a low-probability contingency rather than the base case. Still, the fact that a senior official is willing to discuss it out loud is new information.
Inflation Data Will Decide the Size of the Move
The next consumer price index report arrives at a critical moment. It is one of the final major inflation readings before the December gathering. Soft numbers would still leave the door open for a standard quarter-point rise in this official’s view. Hotter numbers would raise the stakes considerably and make the larger option more attractive.
In my experience watching these cycles, the market reaction to each print has become almost as important as the print itself. Traders parse every tenth of a percent and then immediately reprice the entire path of policy. That feedback loop is exactly why clear communication about follow-through has become so central to the current discussion.
A Healthy Economy Complicates the Picture
The same remarks described growth as progressing at a healthy pace and the labor market as solid, even if the hiring and firing dynamic has slowed. That combination creates a genuine policy tension. Stronger activity supports the case for higher rates, yet it also means any overtightening could eventually show up in weaker demand. The challenge is to keep inflation moving lower without tipping the expansion into unnecessary weakness.
Other officials have recently stressed the danger of allowing the economy to run too hot. Once overheating takes hold, the cost of cooling it can be severe. That warning sits alongside the current call for continued firming and creates a picture of a committee still weighing two risks rather than chasing a single clear signal.
How Markets Are Interpreting the Shift
Price action after the speech was relatively contained, which itself is informative. Traders already expected a December move with high confidence. The new element was the explicit discussion of a half-point possibility. That idea did not gain much traction in futures pricing, but it did remind everyone that the range of outcomes remains wider than a simple binary hike-or-hold decision.
Perhaps the most interesting aspect is how quickly the narrative can pivot. Only a short time ago the conversation centered on how long the pause might last. Now the focus is on whether the next step will be standard size or something more forceful. That kind of rapid reassessment is typical when policymakers speak with unusual clarity.
The Broader Path Still Matters More Than Any Single Meeting
One theme that came through repeatedly is that consecutive meetings are not required. The important thing is that the total amount of tightening reaches the level needed to restore price stability. That flexibility gives the committee room to skip a meeting if data improve, yet it also places greater weight on delivering when the data do not cooperate.
I find this framing useful because it reduces the drama around any individual decision. The real question becomes whether the cumulative path remains consistent with the goal. Markets understand that logic, which is why they tend to react more strongly to changes in the expected terminal rate than to the precise timing of intermediate steps.
Labor Market Conditions Still Support Caution
The description of the job market as solid but less dynamic fits the recent pattern of lower hiring and lower firing. Unemployment has stayed relatively contained, yet the pace of job creation has cooled. That environment reduces the urgency for aggressive further tightening while still leaving little room for complacency on the inflation front.
In practical terms, a soft landing remains the hoped-for outcome. Achieving it requires rates high enough to restrain demand without generating a sharp rise in joblessness. The current discussion suggests that at least some policymakers believe a bit more restraint is still needed before that balance can be declared secure.
What a Half-Point Increase Would Signal
A fifty-basis-point move in December would represent a clear escalation. It would tell markets that the data had deteriorated enough to require a faster response. It would also demonstrate a willingness to accept short-term market volatility in order to protect longer-term credibility. Those are heavy messages, which is why the official framed the larger option as conditional rather than preferred.
Most observers still assign low odds to that outcome. The more likely path remains a standard quarter-point step, provided inflation does not surprise sharply higher. Yet the mere fact that the larger option is being discussed publicly keeps it on the radar and prevents markets from becoming too comfortable with the status quo.
Communication Strategy Has Become Central
Clear guidance before and during the October meeting helped markets understand that further firming remained possible. The latest remarks build on that foundation by stressing the need to follow through. When communication is consistent, the precise calendar of moves becomes secondary. When communication is undercut by inaction, the opposite occurs and policy effectively eases through the back door.
That insight feels especially relevant right now. After a long period of rapid increases, the committee has shifted to a more data-dependent stance. Data dependence only works if the response function remains predictable. The current emphasis on delivering promised hikes is an attempt to keep that response function intact.
Implications for Investors and Borrowers
For those managing portfolios, the message is to remain prepared for higher rates for longer. Equity valuations that assumed an early and aggressive easing cycle may need adjustment. Fixed-income strategies that positioned for rapid rate cuts could face further pressure if the December move materializes and is followed by additional firming later.
Borrowers face a similar reality. Mortgage rates, auto loans, and business credit all remain sensitive to the policy path. A December increase would likely keep those costs elevated into the new year. The possibility of a larger step, however remote, adds another layer of uncertainty that households and firms must factor into their planning.
The Risk of Waiting Too Long
One subtle warning in the recent comments is that higher rates will be needed sooner rather than later. Delaying action risks allowing inflation expectations to drift or demand to reaccelerate. Either development would ultimately require even more restrictive policy. The preference is to act while the economy still shows resilience rather than after imbalances have grown more severe.
That perspective helps explain the willingness to discuss a half-point option. It is less about wanting a dramatic move for its own sake and more about preserving the option to respond forcefully if the data demand it. Keeping that option open is itself a form of risk management.
Comparing Views Across the Committee
Not every official shares the same degree of urgency. Some continue to stress patience and the value of accumulating more evidence. Others have highlighted the cost of allowing overheating to take root. The range of opinions is normal at this stage of the cycle, yet it also means that the December outcome is not locked in. Data between now and the meeting will matter a great deal.
What stands out is the willingness of at least one influential voice to put a larger move on the table. That openness may encourage others to consider the full range of possibilities rather than defaulting to the smallest available step. In a committee that operates by consensus, even a single clear statement can shift the center of gravity.
Looking Ahead to the December Decision
The meeting itself is still several weeks away. Between now and then, another inflation report, additional labor market data, and various speeches will fill the calendar. Each release will be examined for clues about the balance of risks. The base case remains a quarter-point increase, but the conversation has broadened enough that a hold or a larger move can no longer be dismissed out of hand.
I have found that these intermediate periods often prove more informative than the meetings themselves. Officials use the time to refine their thinking in public, and markets use it to test assumptions. The latest remarks have already performed that function by reopening the debate about the appropriate size of the next step.
Why Follow-Through Matters for Long-Term Stability
Credibility is not an abstract concept in monetary policy. It is the foundation that allows relatively small rate changes to influence behavior across the entire economy. When households and firms believe the central bank will do what it says, inflation expectations stay anchored and financial conditions adjust smoothly. When that belief weakens, larger and more disruptive moves become necessary later.
The current emphasis on delivering promised increases is an attempt to protect that foundation. It recognizes that markets have already incorporated further firming into their outlook. Honoring that outlook preserves the transmission mechanism. Ignoring it would force the committee to work harder in the future to regain lost ground.
Practical Takeaways for the Months Ahead
- Expect the December decision to remain data-dependent, with inflation readings carrying extra weight
- Recognize that a quarter-point move is still the most likely outcome under current conditions
- Keep the half-point possibility in view as a contingency rather than a base case
- Watch for any shift in the broader path of rates rather than focusing solely on the next meeting
- Prepare for the possibility that restrictive policy lasts longer than earlier forecasts suggested
These points are not predictions. They are simply the logical implications of the latest public comments. Conditions can change quickly, and new information could alter the calculus. Still, the direction of travel has become clearer than it was only a short time ago.
The Human Element Behind the Policy Debate
It is easy to treat these discussions as purely technical. In reality they involve real judgments about trade-offs that affect millions of people. Higher rates help cool inflation but also raise the cost of credit for families and businesses. The officials making these calls are aware of both sides of the ledger. The latest remarks show one of them concluding that the risk of under-delivering on the inflation fight currently outweighs the risk of overtightening.
That judgment can always be revised. Fresh data could shift the balance. For now, though, the public signal is that further action remains more likely than not, and that the size of the action will depend on how the numbers evolve.
Putting the Latest Comments in Context
Central bankers rarely speak in absolute terms. They prefer conditional language that leaves room for new information. The latest statements fit that tradition while still conveying a clear lean. The official is prepared to support a December increase even if inflation comes in softer than expected. He is prepared to support a larger increase if inflation comes in hotter. That two-sided readiness is what stands out.
In a world where every speech is parsed for hidden meaning, such directness is useful. It reduces the chance of misinterpretation and keeps the focus on the underlying economic logic rather than on subtle shifts in wording. Markets may not have dramatically repriced the path, but they have been reminded that the range of possible outcomes is still wide.
Final Thoughts on the Road to December
The coming weeks will bring more data, more speeches, and more market reactions. Through it all, the central message from at least one influential voice remains consistent: the promised firming needs to be delivered if credibility is to be preserved. Whether that delivery takes the form of a standard quarter-point step or something larger will depend on the numbers that arrive between now and the meeting.
For anyone watching the policy path, the practical approach is to stay flexible. Assumptions that once seemed solid can shift with a single data release or a single set of remarks. The latest comments have already demonstrated how quickly the conversation can evolve. The only constant is the commitment to returning inflation to target while keeping the expansion on a sustainable footing. Everything else remains subject to revision as the evidence accumulates.
That is the real takeaway. The December decision is not yet written, but the framework for making it has become clearer. Markets, households, and firms now have a sharper sense of the considerations that will shape the outcome. In a process that often feels opaque, that added clarity is valuable in its own right.