
Sitting here looking at the latest rate decision still leaves me with that familiar mix of relief and unease. The central bank did exactly what most people expected and left borrowing costs alone. Yet the real story is not the hold itself. It is the sharp split in how people are reading the same set of numbers and the same set of speeches. One camp already sees a December increase as almost inevitable. The other thinks the whole hawkish tone is little more than stagecraft before reality forces a softer approach. I keep coming back to the same question: which side is reading the room correctly this time?
Why The Latest Rate Hold Feels Anything But Settled
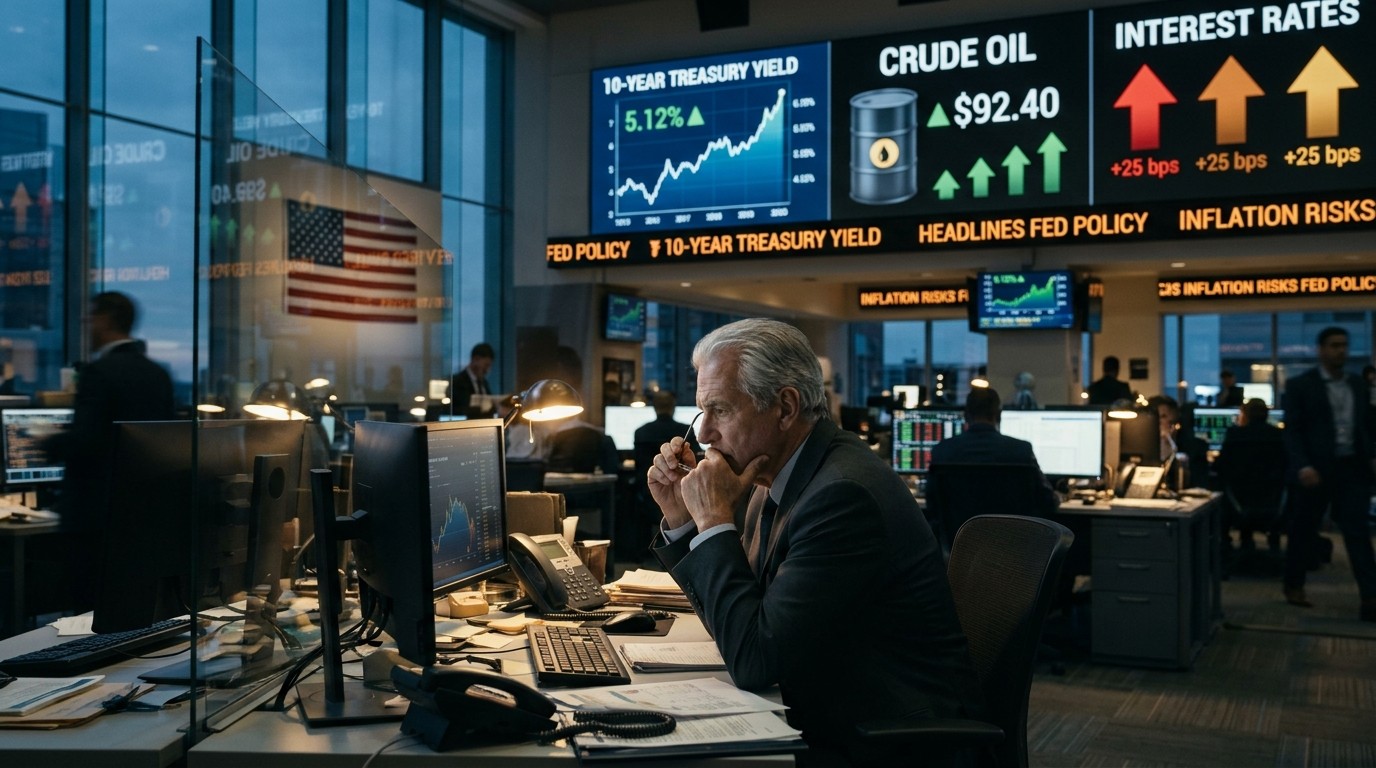
Markets rarely get a clean story, and this week proved no exception. The decision to stay put was widely anticipated, yet the conversation immediately shifted to what comes next. Energy costs have been climbing hard enough that some experienced bond managers now talk openly about inflation numbers starting with a four again. That kind of language tends to move the needle. It also explains why pricing tools currently assign nearly four-out-of-five odds to a rate increase at the next gathering.
I find myself circling back to one particular warning that stood out. A veteran fixed-income investor known for calling major turns in the bond market put it bluntly. The current oil price, once you factor in the extra charges layered on top, behaves more like a much higher number from earlier years. Headline consumer prices, in his view, could easily print above four percent and stay there for several months if energy does not retreat meaningfully. That is not a casual observation. It is the kind of comment that forces people to revisit their base cases.
Today’s oil price really is equivalent to a much higher commodity spot level because of all the surcharges coming in. We are going to start seeing the headline measure left of the decimal point begin with a four, and it is going to look that way as long as energy stays roughly where it is now.
That assessment lines up with the current market wager. The probability of a December move higher sits close to eighty percent in the most watched forecasting tool. Two policymakers also leaned more restrictive during the recent gathering. Still, a quieter group of analysts remains unconvinced. They describe the tougher language as something closer to performance than conviction. Their bigger worry sits further out the curve: long-term government bond yields that refuse to come down and that keep adding pressure to an already heavy fiscal load.
Energy Prices And The Inflation Feedback Loop
Energy is never just another line item. When it rises, it feeds into almost every other cost with a lag that is hard to ignore. Shipping, food production, manufacturing inputs, even the simple act of driving to work all feel the difference. If oil stays elevated, the broad price index has a tough time settling back toward the two percent comfort zone that officials prefer. I have watched this movie before. Temporary supply shocks sometimes prove less temporary than hoped.
The current situation carries an extra layer of complication. Geopolitical friction around key shipping lanes has already tightened the physical market. That tightness does not vanish overnight. Meanwhile companies that locked in longer-term financing a few years ago now face refinancing walls just as borrowing costs remain high. The combination creates a structural headwind along the entire yield curve. In my view that is the piece too many casual observers still underweight.
- Oil trading near levels that effectively price in heavy additional charges
- Headline inflation at risk of printing above four percent for several months
- Refinancing needs from earlier low-rate debt coming due in waves
- Persistent elevation in both ten-year and thirty-year yields
Ten-year and thirty-year government paper both sit above five percent. Year-to-date the ten-year has climbed roughly a quarter while the longer bond is up about eleven percent. Those are not trivial moves. They raise the cost of servicing existing debt and they complicate any plan that relies on rolling over large volumes of maturing securities at manageable rates. The longer this continues, the greater the risk that fiscal pressures force a different conversation inside the central bank.
The Quiet Debate Over Forward Guidance
Inside the institution itself the temperature is not entirely calm either. The current chair has made no secret of his preference for less detailed road maps. He argues that markets too often treat forecasts as ironclad promises and then punish any deviation. Several colleagues take the opposite view. They believe the public deserves a clear explanation of the thinking behind every adjustment. That philosophical gap matters more than it might first appear.
External voices have already begun to weigh in. The treasury secretary publicly backed the chair’s early stewardship and expressed confidence that the dual goals of maximum employment and stable prices can still be balanced. At the same time the same official urged an open mind about the temporary nature of recent supply shocks, pointing to earlier episodes when aggressive tightening into energy spikes produced its own set of problems. The message was careful, but the implication was hard to miss: keep options open.
When authorities elsewhere raised rates into a similar energy shock, the later outcome was not ideal. An open mind about the transitory character of the supply disruption still seems wise.
I keep returning to that tension. On one side sits a market that has already priced a high chance of tighter policy before year-end. On the other sits a fiscal reality that grows more uncomfortable the longer yields remain elevated. Somewhere in the middle sits a leadership team still sorting out how much guidance is helpful and how much simply creates false certainty.
What Elevated Long-Term Yields Actually Signal
Yields above five percent on both the ten-year and the thirty-year are not background noise. They reflect a market that demands compensation for inflation risk, for duration risk, and for the sheer volume of paper that still needs to be absorbed. When the government borrows at these levels for extended periods, the interest bill starts to crowd out other priorities. That dynamic has a way of concentrating minds inside both the treasury and the central bank.
Some observers already talk about the possibility of a more serious sovereign funding stress if the trend does not reverse. I am not ready to go that far, but I do take the warning seriously. The combination of large refinancing needs from the low-rate vintage of a few years ago and the current level of yields creates a real squeeze. Hyperscale technology firms and other heavy borrowers are also competing for the same capital. The result is a crowded market that leaves less room for error.
Perhaps the most interesting aspect is how quickly the narrative can flip. A meaningful drop in oil could ease the inflation path and open the door to a more patient stance. Conversely, another leg higher in energy costs would make the December pricing look conservative rather than aggressive. Right now the data still lean toward the latter, but markets have a habit of forcing the issue faster than models predict.
Two Competing Stories About The Next Few Months
Story number one is straightforward. Inflation reaccelerates because energy stays sticky. Officials respond by delivering the increase that markets already expect. The yield curve stays elevated or even steepens further as investors demand more compensation. Fiscal pressure intensifies and the conversation eventually turns to whether policy has overshot.
Story number two is more nuanced. The hawkish signals prove temporary. Softening data or a pullback in commodities allows the central bank to stay on hold longer than the current pricing assumes. Long-term yields finally peak and begin to ease, giving the fiscal side breathing room. In that version the December move never materializes and the market has to reprice the entire path lower.
I lean slightly toward the first story in the near term, mainly because energy markets do not reverse on a dime and because the current pricing already embeds a high bar for disappointment. Still, I would not bet the farm on either outcome. The range of plausible paths remains unusually wide.
| Factor | Supports Rate Hike | Supports Longer Hold |
| Energy prices | High and sticky | Potential pullback |
| Market pricing | Near 80 percent for December | Can reverse quickly |
| Long-term yields | Above 5 percent, fiscal pressure | May force eventual pivot |
| Policy communication | Some hawkish signals | Preference for less guidance |
Practical Implications For Investors Right Now
What does all of this mean if you are trying to position a portfolio rather than simply watch the debate? First, duration risk is not free. Bonds that looked attractive when yields were lower now carry meaningful price risk if the path tilts tighter. Second, sectors sensitive to financing costs, especially those with heavy refinancing calendars, deserve closer scrutiny. Third, any relief rally in longer yields could be both powerful and short-lived depending on the next inflation prints.
I have found that the most useful approach in these moments is to stress-test both narratives rather than commit fully to one. Keep enough flexibility to adjust if oil breaks lower or if another geopolitical flare-up pushes it higher. Liquidity still matters. The ability to move without paying a steep premium becomes valuable when consensus shifts overnight.
- Review exposure to longer-duration fixed income and size it deliberately
- Monitor weekly energy price trends as a leading signal for inflation data
- Watch the evolution of market-implied probabilities rather than any single forecast
- Stay alert to any change in the tone of official communications after the next data releases
None of this is especially original advice, yet the discipline of revisiting it each time the path grows murkier remains useful. Markets have a way of punishing the assumption that the current setup will simply persist.
The Longer Shadow Of Fiscal Reality
Beyond the next meeting sits a deeper question that rarely receives the attention it deserves. How long can long-term yields remain this elevated without forcing a more fundamental reassessment of the policy mix? Interest costs are already a rising share of the budget. If the average rate on the outstanding debt continues to climb, the arithmetic eventually becomes difficult to ignore.
Some market participants already describe the situation as a slow-motion crowding-out of private investment. Others see the potential for a more abrupt adjustment if foreign demand for government paper softens at the same time that domestic needs remain high. I am not predicting a crisis, but I am acknowledging that the room for error has narrowed. Policy that looks appropriate in isolation can look less so once the fiscal feedback loop is included.
That is why the debate over forward guidance carries extra weight. Clearer communication might help markets price the path more accurately, reducing the chance of a sudden yield spike. Less guidance might preserve flexibility but at the cost of greater day-to-day volatility. Neither choice is costless.
Reading Between The Lines Of Recent Comments
When experienced bond managers start talking about inflation numbers that begin with a four, it pays to listen even if the base case still looks different. Their track record on major turns is better than most. At the same time, the caution from those who see the current hawkish tone as partly performative also deserves space. Both sides can be partially right at different horizons.
The near-term risk tilts toward higher rates if energy stays firm. The medium-term risk tilts toward eventual pressure for easier policy if yields refuse to cooperate with fiscal needs. Holding both thoughts at once is uncomfortable, yet it seems more realistic than picking a single clean narrative and defending it at all costs.
In my experience the periods when official policy and market pricing diverge the most are exactly the periods when the eventual resolution produces the largest moves. We may be entering one of those stretches. Whether the resolution arrives in December or later, the adjustment is unlikely to be quiet.
Where Attention Should Focus Next
The next few inflation reports will matter more than usual. So will any shift in the physical oil market. So will the tone of the next set of official remarks. Beyond those familiar markers, the behavior of the long end of the curve remains the under-appreciated signal. If ten-year and thirty-year yields continue to grind higher even after a rate increase, the fiscal conversation will intensify. If they roll over, the pressure eases and the path toward easier policy becomes more plausible.
I plan to watch the interplay between those three variables more closely than any single headline. Energy, inflation prints, and the long end of the curve together tell a more complete story than any one of them in isolation. That is where the real information is likely to surface first.
For now the central bank has chosen patience. Markets have chosen a different interpretation. History suggests one of those views will have to adjust, and the adjustment rarely arrives without some turbulence. The only real question is how soon and how large that turbulence proves to be.
The coming weeks should bring clearer evidence. Until then the prudent course remains the same: stay flexible, keep risk sizes modest relative to conviction, and remember that the most confident voices in either direction are often the ones who end up adjusting the most. That has been true through more cycles than I care to count, and it feels true again now.